Forget Fixed Income: This Ultra-Safe Dividend Stock Could Be Retirees’ Best Friend
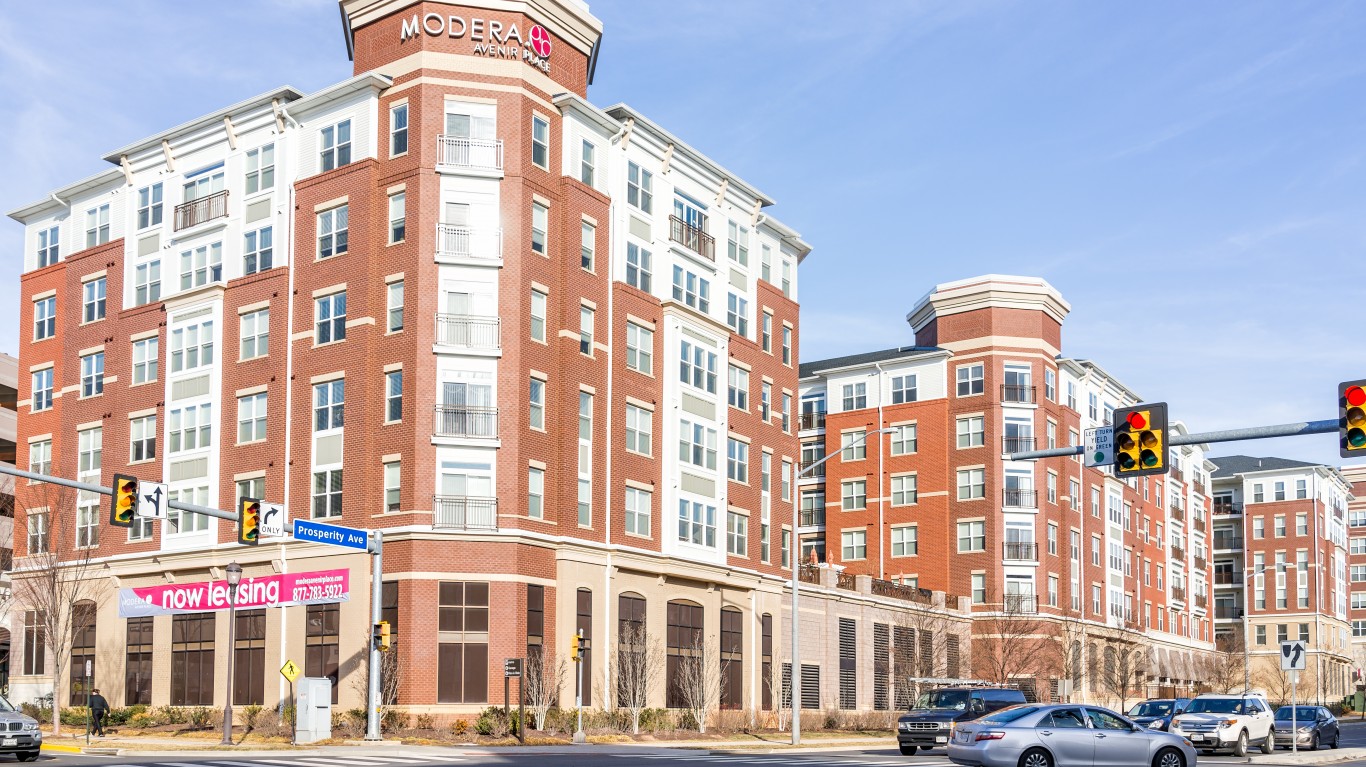
If Mid-America Apartment Communities (NYSE:MAA) lives up to its billing as a retiree’s hedge against a hawkish Fed, the dividend has to be the load-bearing wall. With the 10-year Treasury at 4.49% and the Warsh Fed potentially pivoting back toward…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

If Mid-America Apartment Communities (NYSE:MAA) lives up to its billing as a retiree’s hedge against a hawkish Fed, the dividend has to be the load-bearing wall. With the 10-year Treasury at 4.49% and the Warsh Fed potentially pivoting back toward hikes, MAA’s ~4.6% yield on Sun Belt apartments needs to be durable. Let’s see if it is.
Dividend Snapshot
| Metric | Value |
|---|---|
| Annual Dividend | $6.12 per share |
| Dividend Yield | ~4.6% |
| Consecutive Quarterly Payments | 128 |
| Consecutive Annual Increases | ~15 years |
| Most Recent Raise | ~1% (Dec 2025) |
| Aristocrat Status | No (not yet) |
Core FFO Cleanly Outruns the Payout
REIT dividends are funded by cash flow rather than GAAP earnings, so the headline payout ratio looks scary until you adjust. The $6.12 dividend against FY2025 GAAP EPS of $3.78 is over 100%, normal for a depreciation-heavy REIT. What matters is Core FFO.
| Metric | Value | Assessment |
|---|---|---|
| FFO Payout Ratio (2025) | ~70% | Healthy |
| AFFO Payout Ratio (2025) | ~78.6% | Adequate |
| 2026 FFO Payout (Guided) | ~71.7% | Healthy |
Management’s 2026 Core FFO midpoint of $8.53 leaves roughly $2.41 per share above the dividend. That cushion absorbs the $0.25/share interest expense headwind from refinancing without breaking a sweat.
Balance Sheet Built for a Hawkish Fed
| Metric | Value | Assessment |
|---|---|---|
| Net Debt/EBITDA | 4.5x | Manageable |
| Avg Debt Maturity | 6.1 years | Strong |
| Effective Rate on Debt | 3.9% | Locked in low |
| Liquidity | ~$840M cash + revolver capacity | Solid buffer |
With debt locked at 3.9% for an average of 6.1 years, a Warsh rate-hike scenario pressures the refinancing math at the margin while leaving the dividend intact.
A 27-Year Streak Without a Cut
| Year | Annual Dividend |
|---|---|
| 2026 | $6.12 |
| 2025 | $6.06 |
| 2024 | $5.88 |
| 2023 | $5.60 |
| 2022 | $4.78 |
MAA paid through 2008-2009 without a cut and has hiked every year since 2010. Recent growth has decelerated to ~1%, which is the fair tradeoff for a payout that’s never been broken.
Management’s Dividend Doctrine
CEO Brad Hill on the Q1 2026 call: “We’re really focused on generating high-quality compounding earnings growth that supports a steady and growing dividend. We really think that’s the best way to drive total shareholder return over the full cycle.” COO Tim Argo reported Q1 2026 occupancy at 95.5% and net delinquency at just 0.3% of billings. Those are the numbers that fund the check.
Verdict: Safe, With Slow Growth Baked In
Dividend Safety Rating: Safe. The ~72% FFO payout, 4.5x leverage, and Sun Belt demand backdrop (deliveries down 40% YoY) all point one way. The income case holds up for investors who can accept low-single-digit raises while supply digests through 2027. The risk case sharpens if a hawkish Fed crushes job growth in Texas and Florida, since blended lease pricing is already running negative 0.3%. On balance, this dividend is built to outlast the rate cycle.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.