This AI Stock Could Be Worth Far More Than Investors Think
Broadcom just posted AI revenue growth of 221% year over year and guided for even bigger numbers ahead, yet the stock sits well off its highs and trades at a fraction of its closest custom-chip rival's multiple. Something in that…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Broadcom (NASDAQ:AVGO | AVGO Price Prediction) has become the second most valuable custom AI chip franchise on the planet, yet the stock is down over the past month and trading well below its 52-week high. Our proprietary model says that disconnect is an opportunity.
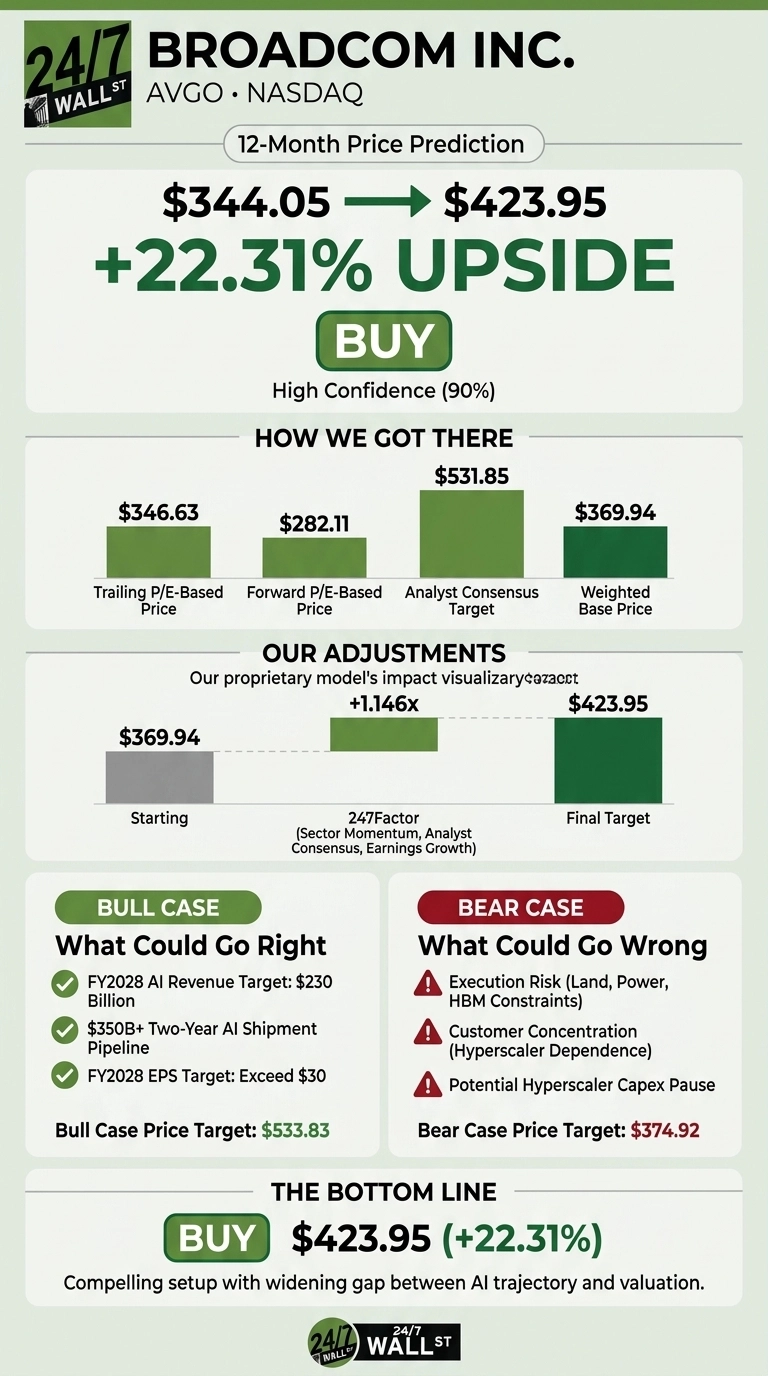
Our 24/7 Wall St. price target for Broadcom is $423.95, implying 22.31% upside from the current $344.05 quote. The recommendation is a buy with high confidence at 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $344.05 |
| 24/7 Wall St. Price Target | $423.95 |
| Upside | 22.31% |
| Recommendation | BUY |
| Confidence Level | 90% |
A Pullback Inside a Blowout Quarter
AVGO is down 3.87% over the past week and 12.45% over the past month, leaving it roughly flat year to date and well off the 52-week high of $494.18. That weakness followed a fiscal Q3 report that was exceptionally strong. Revenue reached $29.591 billion, up 85.5% year over year, with non-GAAP EPS of $3.32 beating consensus.
The AI story was even bigger. AI semiconductor revenue hit $16.70 billion, up 221% year over year, and management guided Q4 AI revenue to $21.7 billion. CEO Hock Tan said “Q3 demand was simply hot and we’re just getting started.”

Why Bulls See a Breakout Ahead
The bull case is written in Broadcom’s own long-term guidance. Management now targets fiscal 2027 AI revenue of $115 billion and fiscal 2028 AI revenue of $230 billion, with a $350 billion two-year shipment pipeline across six XPU customers including Google, OpenAI, Meta, and Anthropic.
Tan told investors Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.” The Wall Street consensus target sits at $531.85, with 37 Buy and 8 Strong Buy ratings. Our bull scenario pegs AVGO at $533.83 over 12 months.

What Could Go Wrong
Execution risk is the biggest concern. Tan flagged that “land power and shell” constraints dictate when capacity actually deploys, and HBM memory, substrates, and leading-edge wafers could each become bottlenecks. Customer concentration is real: hyperscaler XPU programs drive the model, and any pause at Google, Meta, or OpenAI would ripple through the numbers.
Our bear scenario lands at $374.92, still above today’s price. It should be noted that the margin dilution bears cite higher memory content per XPU, and CFO Amie Thuener said Broadcom expects to “sustain operating margin even as mix of products dilutes the gross margin.”
How Broadcom Compares to NVIDIA, AMD, and Marvell
| Company | Forward P/E | Analyst Target |
|---|---|---|
| Broadcom | 19x | $531.85 |
| NVIDIA | 24x | $327.18 |
| AMD | 33x | $615.07 |
| Marvell | 56x | $284.64 |
NVIDIA (NASDAQ:NVDA) is the AI GPU standard and trades at 24x forward earnings on quarterly revenue growth of 105.9%. NVIDIA carries a richer multiple than AVGO despite Broadcom’s faster sequential AI acceleration, which makes our target look conservative on a relative basis.
AMD (NASDAQ:AMD) is the merchant AI accelerator alternative, but at 33x forward earnings with just 50.1% revenue growth, AMD is being valued more optimistically than AVGO for slower growth.
Marvell Technology (NASDAQ:MRVL) is the closest custom-ASIC comp and trades at a stunning 56x forward earnings on 36.5% revenue growth. Against this peer set, our 24/7 Wall St. price target for AVGO looks reasonable and arguably conservative.
Why the Setup Looks Compelling
The 24/7 Wall St. price target is $423.95, a buy with 90% confidence. The tipping factor is the widening gap between Broadcom’s fiscal 2028 AI trajectory and its comparatively modest forward multiple.
I’d be a buyer here if the Q4 earnings report confirms the $21.7 billion AI guide. I’d stay on the sidelines if hyperscaler capex pauses or if land, power, and HBM constraints slip the 2027 ramp.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $423.95 |
| 2027 | $429.13 |
| 2028 | $500.32 |
| 2029 | $559.32 |
| 2030 | $600.00 |
These projections assume Broadcom continues executing on custom AI accelerator ramps for its six XPU customers. Significant upside could come from the fiscal 2028 $230 billion AI target holding, while downside would follow any hyperscaler capex reset.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.