Broadcom’s AI Opportunity Is Bigger Than Its Stock Price Suggests
Broadcom just posted its ninth straight earnings beat while AI revenue exploded triple digits year-over-year, yet the stock has barely moved in 2026. Something has to give, and our model has a strong opinion on which direction.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Custom AI silicon has moved from a side business to the largest single growth engine at any US chip company outside NVIDIA. Yet Broadcom (NASDAQ:AVGO | AVGO Price Prediction) shares have drifted sideways for most of 2026, which is exactly the setup our proprietary model looks for.
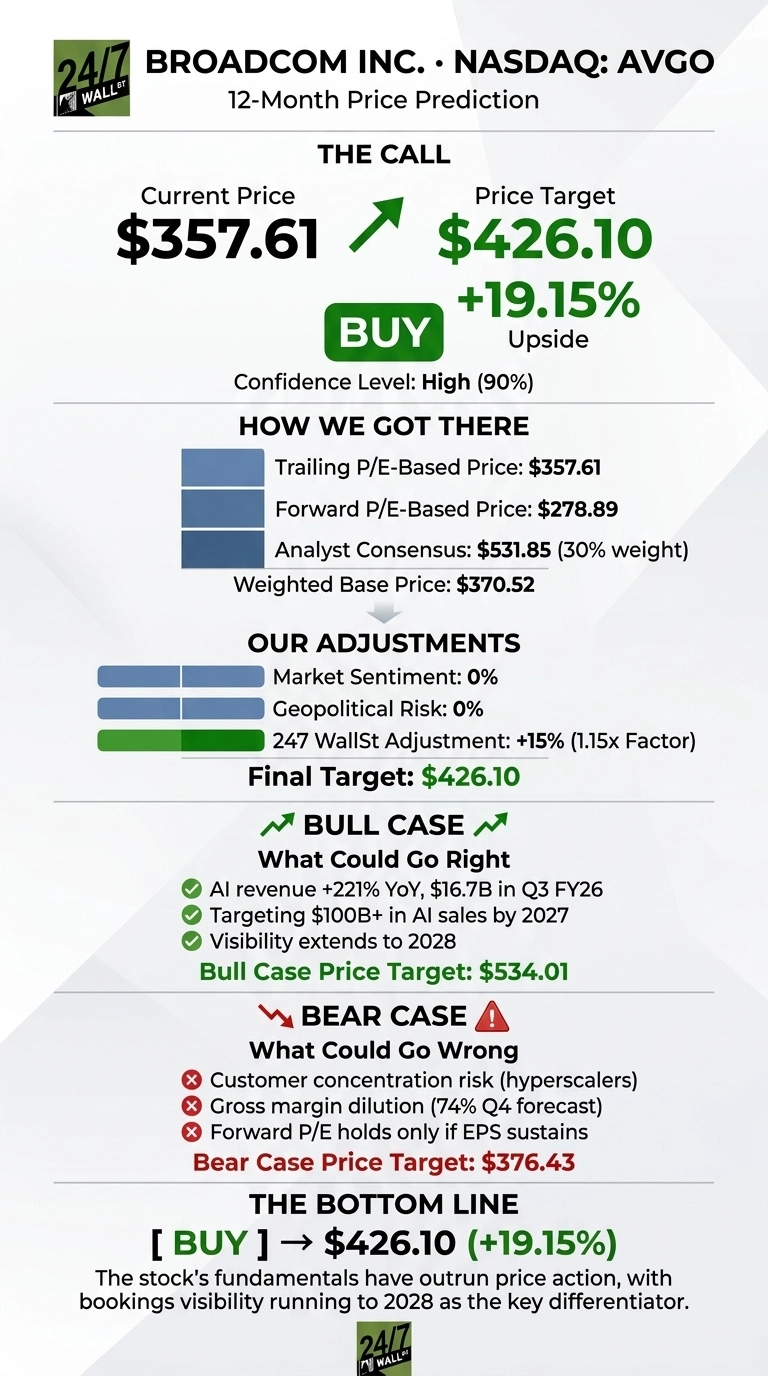
Broadcom trades at $357.61 as of the September 18, 2026 close. Our 24/7 Wall St. price target for Broadcom is $426.10, an implied upside of 19.15% over the next twelve months. Our recommendation is buy, and our model confidence sits at 90%, which we classify as high.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $357.61 |
| 24/7 Wall St. Price Target | $426.10 |
| Upside | 19.15% |
| Recommendation | BUY |
| Confidence Level | 90% |
An AI Story the Chart Isn’t Telling
Broadcom is up just 3.71% year-to-date and 4.31% over the past year, with shares down 1.34% in the last month. That is a striking disconnect from the underlying business.
Fiscal Q3 2026, reported September 2, 2026, delivered revenue of $29.59 billion, up 85.5% year-over-year, with non-GAAP EPS of $3.32, the ninth straight beat. AI semiconductor revenue reached $16.70 billion, up 221% year-over-year, and management guided Q4 AI revenue to $21.7 billion, up 236%. CEO Hock Tan has publicly targeted exceeding $100 billion in AI sales by 2027.

Why Bulls See a Breakout Ahead
The bull case rests on customer roster strength. On the Q2 fiscal 2026 call, Tan disclosed a Meta partnership to deploy 3 gigawatts through the end of 2028, an OpenAI commitment of 1.3 gigawatts in 2027 as part of a broader 10 gigawatts by 2029 agreement, and $6 billion in additional purchase orders from two unnamed customers.
Tan stated, “Demand for XPUs and networking is simply insatiable.” Consensus analyst target of $531.85 implies 48% upside. Our bull-case scenario projects $534.01 within twelve months if AI bookings accelerate.

Risks Worth Watching
The bear thesis centers on customer concentration. Broadcom has flagged concentration in a limited number of hyperscale AI customers as a primary risk. Any capex reset from Google, Meta, or OpenAI would flow directly through. A forward P/E of 19 holds only if $14.64 forward EPS sustains.
Gross margin is expected to compress toward 74% as AI silicon becomes a larger mix. CFO Kirsten Spears countered that “Structurally, the semiconductor margins remains very stable and very solid,” attributing dilution to mix rather than pricing. Our bear-case one-year price sits at $376.43, still above current levels.

How Broadcom Compares to NVIDIA and Marvell
NVIDIA (NASDAQ:NVDA) closed at $222.27 with consensus fiscal 2027 EPS of $9.31, putting its forward P/E near 24. Broadcom’s forward P/E of 19 is a real discount to the merchant-GPU leader, validating our conservative price target.
Marvell Technology (NASDAQ:MRVL) is the closest custom-silicon and AI networking pure-play. It closed at $244.25, up 1.45% on the same session Broadcom rose 2.97%. Marvell competes for the same hyperscaler ASIC sockets, which shows AVGO faces credible competition in AI while Broadcom’s scale advantage justifies its premium.
Broadcom Price Prediction 2026-2030
Our $426.10 target and buy rating reflect a stock whose fundamentals have outrun price action.
The bull case holds if Tan’s $100 billion AI target by 2027 is credible. The bear case gains ground if hyperscaler capex plans pull back in 2027. Bookings visibility running to 2028 is the tie-breaker.

| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $374 |
| 2027 | $428 |
| 2028 | $476 |
| 2029 | $524 |
| 2030 | $591 |
These projections assume Broadcom continues executing its custom-silicon roadmap with existing hyperscale customers. Significant upside or downside could result from either an accelerated OpenAI ramp or a broad hyperscaler capex pause.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.