PM vs. MO: The Smoke-Free Dividend Winner in This Tobacco Showdown
Philip Morris and Altria both just raised their dividends, but the gap between them runs far deeper than yield percentages and payout sizes. Which tobacco giant actually deserves a spot in a retirement portfolio built to last a decade?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Philip Morris (NYSE:PM | PM Price Prediction) or Altria (NYSE:MO): which tobacco dividend belongs in a retirement portfolio right now? Both raised their payouts within the past month, and the size of those raises tells the story. Philip Morris lifted its quarterly dividend from $1.47 to $1.60 on September 18. Altria moved from $1.06 to $1.11 on August 27. One company funds its check from a growing global smoke-free business. The other funds it from a shrinking U.S. cigarette market.


Growth Trajectory: Philip Morris Has the Longer Runway
Philip Morris raised its 2026 adjusted diluted EPS guidance to $8.26 to $8.41, or 9.5% to 11.5% growth, and targets 9% to 11% annual adjusted EPS growth ex-currency through 2028. Second-quarter revenue hit $11.19 billion, up 10.4%. Smoke-free products now generate 41.5% of net revenues, and international smoke-free gross margin expanded 190 basis points to 70%. Every IQOS or ZYN sale carries higher economics than the cigarette it replaces, which is why this mix shift matters. The FDA also granted modified-risk authorization to 20 ZYN variants in June 2026.
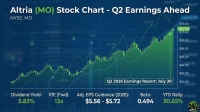
Altria raised its 2026 guidance to $5.61 to $5.72, just 3.5% to 5.5% growth. Industry domestic cigarette volumes fell an estimated 5% in the second quarter, while Marlboro’s retail share slid 1.5 share points as discount share grew 2.6 share points. Its e-vapor push has produced $2.2 billion in cumulative impairments, with no re-entry date announced. Winner: Philip Morris.
Current Income: Altria Pays More Today
Altria yields 6.15% versus 3.08% for Philip Morris. Altria’s forward annualized dividend is $4.44 on a $68.88 share price, while Philip Morris pays $6.40 on a $191.50 stock. Altria has committed to mid-single-digit annual dividend growth through 2028, and management called the payout its “primary vehicle” for shareholder returns. The catch: after the dividend, Altria has typically had only about $1 billion in excess cash. For a retired person who needs cash flow this year, though, the math favors Altria. Winner: Altria.
Valuation and Risk: Philip Morris Offers More Growth per Dollar
Altria trades at 12x forward earnings against 21x for Philip Morris. That discount reflects decline. On a growth-adjusted basis, Philip Morris carries the lower PEG ratio at 2.292 versus 2.642, and a lower beta of 0.395 versus 0.494. Analysts lean the same way: Philip Morris has 3 Strong Buy and 9 Buy ratings, while Altria has 4 Buy, 8 Hold, 1 Sell and 1 Strong Sell. Over ten years, Philip Morris shares returned 214.34% against 118% for Altria.


Philip Morris does carry greater leverage: net debt of $43.1 billion and net debt to adjusted EBITDA of 2.35x, versus Altria’s 1.9 times. Management targets roughly 2.0x by year-end 2026, backed by expected operating cash flow of about $13.5 billion. Winner: Philip Morris.
Verdict: Philip Morris Owns the Dividend Growth Race
Philip Morris looks like the stronger option for any retirement investor with a horizon of ten years or more. Its quarterly payout has rose from $1.02 in 2016 to $1.60 today, and the engine behind it is accelerating. With 93% of first-half revenue earned outside the U.S. and smoke-free products gaining share of sales every quarter, its dividend rests on a business that is expanding. Altria’s payout rests on a U.S. cigarette base that declines every year.
Altria fits one profile: the retired person already drawing income who needs the highest yield today and accepts low-single-digit growth. Everyone else may prefer Philip Morris. Altria is one of the market’s true Dividend Kings, and a free report you can grab here ranks ten of them by current valuation. Keep an eye on Philip Morris’s deleveraging progress, the U.S. ZYN rebound and FDA action on IQOS Iluma. For Altria, track discount-segment share and its e-vapor re-entry.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.