He Gave Each Grandchild $19,000, Now Medicaid Could Refuse Nursing Home Payments
A grandfather writes his grandchildren perfectly legal checks and files nothing with the IRS, yet those same gifts can freeze his nursing home coverage right when the bills start arriving. Two federal agencies run two completely separate rulebooks, and most…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The IRS annual gift-tax exclusion and Medicaid’s transfer rules are separate systems. A $19,000 gift can require no federal gift-tax return yet still trigger scrutiny, and potentially a long-term care penalty, if Medicaid is needed within the lookback period.
The $19,000 Gift Looks Completely Safe
A widower in his late seventies wants to help his grandchildren while he is still around to see them enjoy it. In 2026, he writes each one a $19,000 check. From a federal gift-tax standpoint, that number is not random. The IRS annual exclusion remains $19,000 per recipient in 2026.
For present-interest gifts, a donor can generally give up to that amount to each recipient without using any of the donor’s $15 million 2026 lifetime basic exclusion and without filing Form 709, assuming no other filing rule applies. On the tax side, everything can look perfectly clean.
Then a stroke changes the plan. Long-term nursing care enters the picture, Medicaid becomes relevant, and the exact same checks can suddenly matter for a completely different reason.
The IRS and Medicaid Are Using Two Different Rulebooks
This is the part that catches families off guard. The IRS annual exclusion is a gift-tax rule. Medicaid’s transfer rules are eligibility rules for a needs-based health program. One agency does not give the other a free pass.
A $19,000 gift may create no federal gift-tax filing requirement, but Medicaid can still review it as a transfer for less than fair market value when someone later applies for long-term care coverage. There is no federal Medicaid rule saying gifts are automatically protected simply because they fit under the IRS annual exclusion.
That means the phrase “tax-free gift” can be technically true and still be dangerously incomplete for an older person who may need long-term care.
The Five-Year Lookback Can Reach Back to the Checks
Federal Medicaid law generally requires states to examine transfers made during the 60 months before an institutionalized applicant applies for long-term care Medicaid. Assets transferred for less than fair market value during that window can trigger a period in which Medicaid will not pay for nursing facility or certain other long-term care services.
The details still vary by state. Resource limits, penalty divisors, application procedures, and some exceptions are not identical everywhere, so a universal “$2,000 asset limit” or one-size-fits-all penalty calculation can be misleading.
What does not change is the basic problem: a gift made years before anyone expected nursing-home care can still fall inside the financial history Medicaid reviews.
A Gift Inside the Lookback Is Not Automatically a Penalty
There is an important protection families should not miss. Federal law says a transfer penalty should not apply if the applicant can make a satisfactory showing that the assets were transferred exclusively for a purpose other than qualifying for Medicaid.
That matters in a scenario like this one. A healthy grandfather who routinely gave money to his grandchildren before an unexpected stroke may have evidence that Medicaid planning had nothing to do with the gifts. Whether that argument succeeds depends on the facts, documentation, and the state’s process, so the checks should not be described as automatically penalized.
The safer way to say it is that the gifts can trigger scrutiny and can produce a penalty unless an exception or defense applies.
The Penalty Clock Starts When the Money Is Needed Most
The timing rule is what makes this so painful. For transfers made after Feb. 8, 2006, the penalty generally does not simply run out while the person is healthy at home. Under federal law, it begins no earlier than the point when the applicant is otherwise eligible for Medicaid and would be receiving institutional-level care but for the transfer penalty.
In plain English, the family can discover the problem precisely when the applicant is already in the nursing home and the bills are arriving.
CMS guidance also makes an important distinction: during the penalty period, Medicaid payment is unavailable for the affected long-term care services. The person may still remain eligible for other Medicaid state-plan services.
Three Grandchildren Can Turn $57,000 Into Months of Ineligibility
The federal formula starts with the total uncompensated value transferred and divides it by the applicable average private-pay nursing-facility cost used by the state.
If this grandfather gave three grandchildren $19,000 each, the transfers total $57,000. If his state’s applicable divisor were $12,000 per month, the result would be 4.75 months in which Medicaid would not pay for the affected long-term care services. Four grandchildren would mean $76,000 of transfers and, using that same illustrative divisor, about 6.33 months.
Those are examples, not a national penalty schedule. The divisor that matters is the one the applicant’s state is using, and federal law says states may not simply round away a fractional penalty period.
Medicare Is Not the Backup Plan for Custodial Nursing Care
A common assumption is that Medicare will pick up the nursing-home bill if Medicaid does not. Usually, it will not. Medicare can cover qualifying short-term skilled nursing facility care, generally for no more than 100 days in a benefit period, but it does not pay for long-term custodial nursing-home care when that is the only care needed.
That helps explain why Medicaid matters so much in long-term care. KFF’s 2025 data shows Medicaid as the primary payer for about 63% of residents in certified U.S. nursing facilities.
So when a Medicaid transfer penalty hits, there may not be another federal program waiting to absorb the private-pay bill.
Private-Pay Nursing Home Costs Make a Few Months Expensive
The latest CareScout Cost of Care survey puts the 2025 national median at $10,798 per month for a private nursing-home room and $9,581 for a semi-private room. That is roughly $129,575 and $114,975 per year, respectively.
Location can make the numbers much uglier. CareScout’s 2025 state data puts the median private-room cost in Oregon at $221,372 per year and Washington at $191,625.
That is why a transfer penalty lasting four, five, or six months can become a six-figure planning problem surprisingly quickly. The exact amount a facility charges will vary, but the national medians show the size of the risk.
California Is an Exception, but Even Its Rules Are Changing
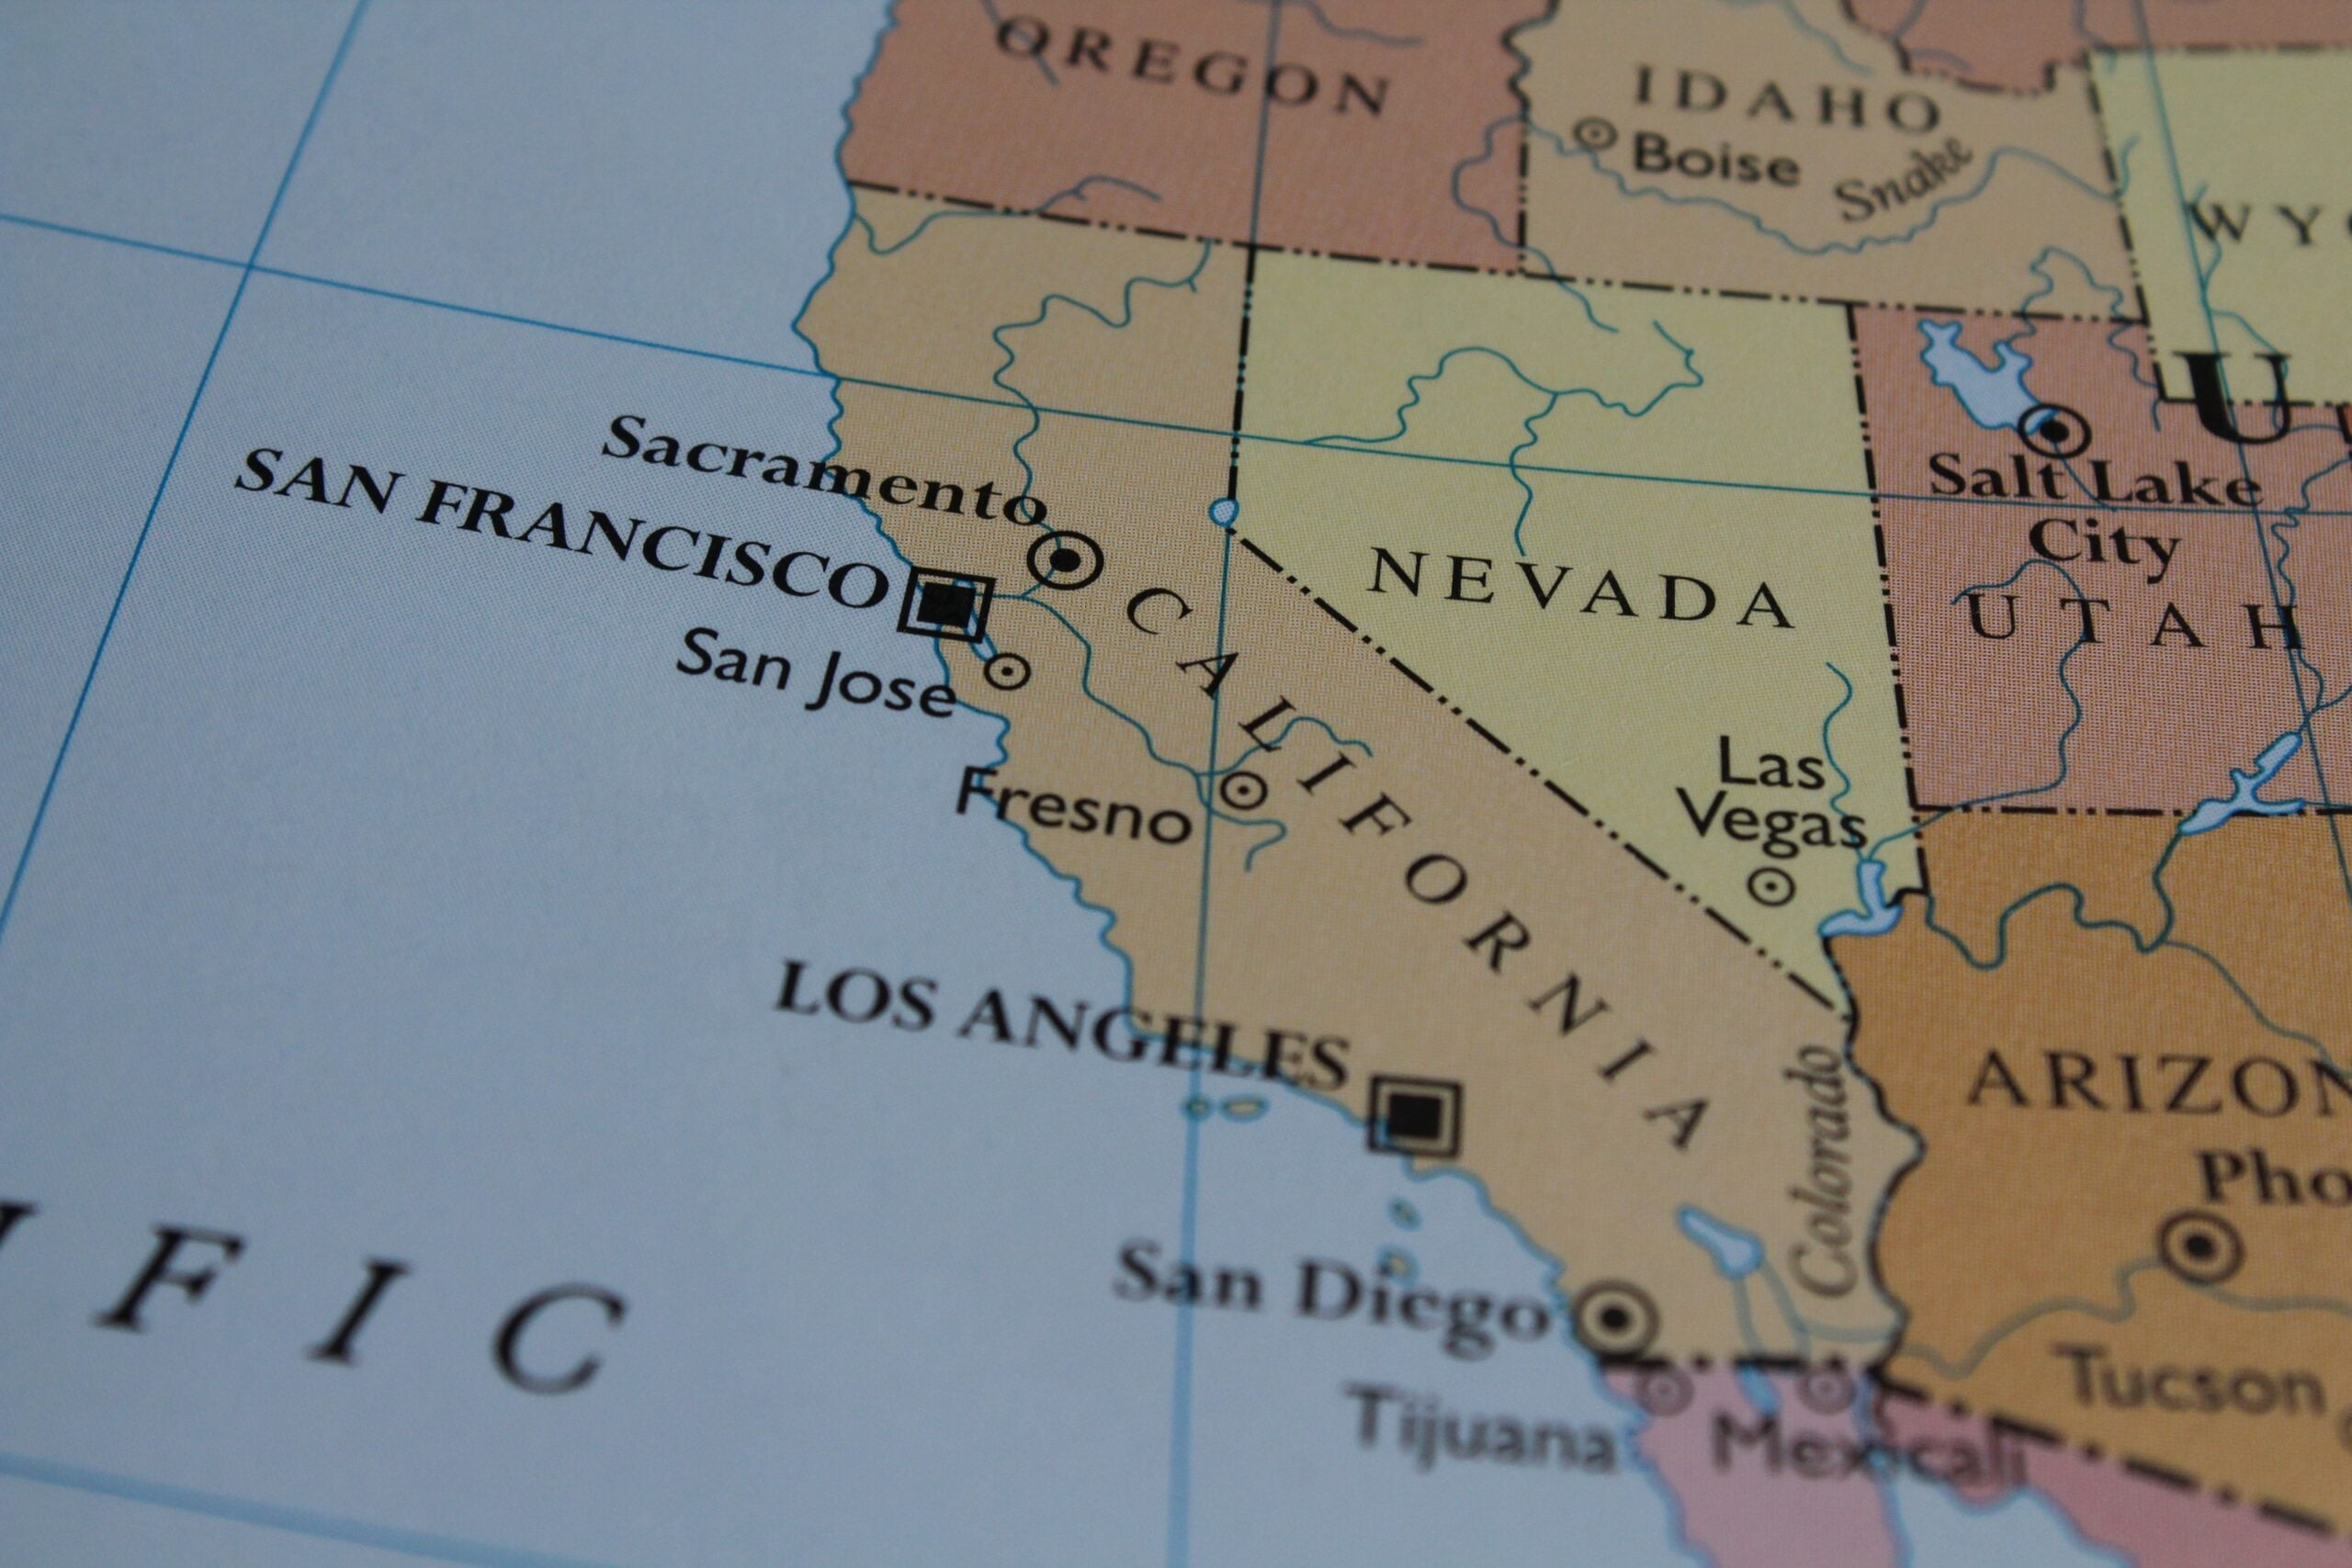
Most of the country operates under the federal five-year lookback framework, but California’s Medi-Cal rules are a notable exception. California uses a shorter 30-month framework for long-term care transfers, and the state is currently rebuilding that lookback after its asset test was suspended in 2024 and 2025.
Transfers made from Jan. 1, 2024 through Dec. 31, 2025 are not included. Transfers made on or after Jan. 1, 2026 can count, and the review period is expanding month by month. California says the full 30-month review will apply to long-term care applications and entries beginning July 1, 2028.
It is a perfect example of why Medicaid planning has to be state-specific instead of built from a national rule of thumb.
The Nursing Home Cannot Simply Make the Family Personally Liable
The original version of this story went too far by saying the nursing-home bill is simply handed back to the family. A Medicaid penalty creates a payment problem for the resident, but relatives are not automatically personally liable just because they are relatives.
Federal nursing-home rules prohibit a certified facility from requiring a third party to personally guarantee the resident’s bill as a condition of admission, expedited admission, or continued stay. A representative with legal access to the resident’s money can be required to use the resident’s funds appropriately, but that is different from promising to pay from the representative’s own pocket.
A facility can pursue payment from the resident’s available resources and, under applicable rules, nonpayment can eventually become grounds for transfer or discharge after proper notice. Families often step in voluntarily, but the law does not simply turn the grandchildren into guarantors.
Some Transfers Are Protected, and Returned Assets Can Change the Result
Federal Medicaid law contains several transfer exceptions. Transfers to a spouse, certain transfers involving a blind or disabled child, and specific transfers of a home to qualifying family members can avoid the penalty when the statutory requirements are met.
There is another escape hatch that matters after a mistake: federal law says the penalty should not apply if all assets transferred for less than fair market value have been returned to the applicant. Treatment of partial returns and the mechanics of curing a transfer are more state-specific.
States must also have an undue-hardship process for cases where imposing the penalty would endanger the applicant’s health or deprive the person of necessities. That is not a casual exception, but it means a denial notice is not always the last word.
Before Writing the Check, Run the Medicaid Math Too
The lesson is not that grandparents should stop helping their families. It is that “$19,000 is allowed” answers only the federal gift-tax question. It says almost nothing about what the transfer could mean if long-term care Medicaid enters the picture within the next several years.
Before a large gift leaves the account, an older donor should know the state’s lookback rules, the applicable resource rules, the current penalty divisor, and whether there is enough money left to privately fund care if Medicaid is delayed. Keeping records showing why gifts were made can also matter if the state later reviews the transfers.
An elder-law attorney licensed in the donor’s state can model the Medicaid side while a tax professional handles the gift-tax side. Two rulebooks are involved here. The expensive mistakes happen when a family checks only one of them.
Contact [email protected] for any questions or corrections.