5 Dividend Stocks That Turn Boring Warehouses Into Retirement Income
Warehouses handling every online order and factory shipment are back in high demand, and five industrial REITs are converting that traffic into growing dividend checks. Which one offers the fattest yield, and which hides a rent problem that could catch…

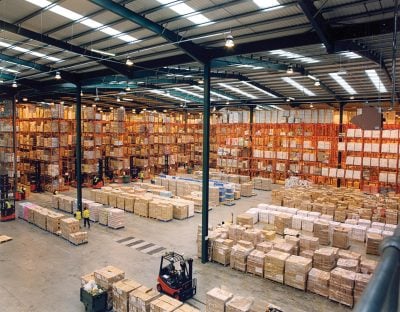
Industrial and logistics REITs own the warehouses, distribution centers and last-mile buildings that every online order, factory part and data center component passes through, and demand for that space is growing again. U.S. net absorption reached 66 million square feet in the second quarter, the highest level since 2022, and market vacancy fell to 7.2%, according to Prologis management. All five names below are equity REITs that own physical buildings. None is a mortgage REIT, so none carries the interest rate and credit risk that comes with lending against property. Dividend safety is measured on funds from operations (FFO), which adds depreciation back to earnings, and each section leads with that coverage figure.
Prologis Pairs Global Scale With a Data Center Kicker
Prologis (NYSE:PLD) is the largest industrial and logistics REIT in the world, with a market cap of roughly $121.3B. Its third-quarter results, reported October 15, 2026, showed Core FFO of $1.60 per diluted share, revenue of $2.39B (+7.8% YoY), average occupancy of 95.1% and cash same-store NOI growth of 5.9%. Net effective rent change on new leases came in at 38.0%. The company’s chief executive, Daniel S. Letter, described the demand backdrop this way: “Customers are running lean on inventory, and excess capacity within their networks has largely cleared. We see healthy demand supported by e-commerce, advanced manufacturing and the build-out of the data center supply chain.”
Yield: The quarterly dividend is $1.07, or $4.28 annualized. At $127.88, that works out to about 3.35%. The payout has risen from $0.53 per quarter in 2019.
Coverage: Prologis narrowed and raised its 2026 Core FFO guidance to $6.25 to $6.29 per share. The annualized dividend uses about 68.3% of the midpoint, which leaves plenty of room to cover the payout and fund development.
Bull case: The data center power pipeline is 5.8 GW, and the $2.1B of data center development starts so far this year are 100% pre-leased. Management estimates that “each $1 trillion of data center capex will generate 30 to 40 million square feet of incremental logistics demand.”
Risk: The pending SEGRO combination has shareholder approval but still has to close, and it would add to currency exposure that already spans 20 countries. Shares slipped 1.98% on the day the results came out.
First Industrial Pushed Through a Double-Digit Dividend Raise
First Industrial Realty Trust (NYSE:FR) owns logistics facilities in top U.S. markets and has a market cap of about $7.70B. In-service occupancy finished the second quarter at 94.9%, up from 94.2% a year earlier. Cash same-store NOI grew 6.7%, and signed 2026 leases carry a cash rental rate increase of 39%. A full-building lease on a 708,000 sq ft Central Pennsylvania facility came with a cash increase of over 60%.
Yield: The dividend went up 12.4% this year, from $0.445 to $0.50 per quarter ($2.00 annualized). At $58.19, the yield is about 3.44%. The next payment lands on October 19, 2026.
Coverage: 2026 NAREIT FFO guidance is $3.08 to $3.16 per share, and that range already absorbs proxy-fight costs. The dividend uses about 64.1% of the midpoint. Second-quarter FFO was $0.82 per share, compared with $0.76 a year earlier.
Bull case: Big buildings are scarce. Activity for spaces above 1.2 million square feet rose 117%, and management added that “tenants have fewer choices, and they have to make decisions quicker.” A $131M Phoenix land sale and a $250M buyback program give the company more capital to work with.
Risk: Guidance assumes in-service occupancy will “dip to around 93.5% at the end of 3Q”, with a recovery that depends on development leasing landing mostly in the fourth quarter. A contested proxy campaign has also cost $5.6M in advisory fees.
EastGroup Just Raised Its Payout Again
EastGroup Properties (NYSE:EGP) owns shallow-bay, last-mile industrial buildings across the Sunbelt and has a market cap of about $10.37B. The operating portfolio was 96.8% leased at the end of the second quarter, with average occupancy of 95.6%. Cash same-property NOI rose 8.3%, and signed leases totaled a record 3.9 million square feet. Chief executive Marshall Loeb said “the leasing environment has normalized compared to the protracted decision making we experienced much of last year.”
Yield: EastGroup paid $1.75 per share on October 15, 2026, up from $1.55, a 12.9% raise. The forward annual rate is now $7.00, for a yield of about 3.63% at $192.91. The second-quarter payment was its 186th consecutive quarterly distribution.
Coverage: 2026 FFO guidance has a midpoint of $9.59, and the new dividend uses about 73.0% of it. That is the highest share in this group, mostly because of the fresh raise. The balance sheet backs it up: debt to EBITDA is 3 times, nothing is drawn on the credit facility and Moody’s upgraded the company to Baa1.
Bull case: Data center suppliers have become a new tenant group, accounting for about 40% of first-quarter development leasing and 20% in the second quarter. Development start guidance went up to $325M.
Risk: Management named consumer weakness as the main thing that could go wrong, through softer tenant demand, tenant credit problems and slower leasing decisions.
STAG Industrial Swapped Monthly Checks for Quarterly Ones
STAG Industrial (NYSE:STAG) owns single-tenant warehouses across the country and has a market cap of about $6.91B. Operating occupancy stood at 95.5% in the second quarter. Same-store cash NOI rose 3.4%, and cash leasing spreads were 19.8%. Core FFO came in at $0.65 per share, up 3.2%.
Yield: Retirees who planned around monthly checks should note the change. STAG paid $0.124167 per month through December 2025 and has paid $0.3875 per quarter since March 2026. The annualized rate is $1.55, which yields about 4.32% at $35.87.
Coverage: 2026 Core FFO guidance is $2.61 to $2.65 per share, and the dividend uses only about 58.9% of the midpoint. That is the widest cushion on this list. Net debt to adjusted EBITDAre is 5.2x, and refinanced term loans now mature in January 2032.
Bull case: The acquisition pipeline holds $4.0B of deals. STAG has also leased 2.3 million square feet to data center-related tenants since the start of last year, at lease terms of about seven years and with rents rolled up 33%.
Risk: Internal growth trails its peers. Cash same-store guidance is 3% to 3.5%, while interest expense rose to $37.5M from $33.6M. The stock is up just 1.53% over the past year.
Rexford’s Top Yield Comes With a Southern California Discount
Rexford Industrial Realty (NYSE:REXR) owns only infill Southern California industrial property and has a market cap of about $8.29B. Its second-quarter GAAP net loss of $506.9M, or ($2.26) per share, came from a $624.75M non-cash impairment on assets flagged for sale. Core FFO actually rose 6.8% to $0.63. Average same-property occupancy was 95.7%, but comparable cash rental rates fell 11.3%.
Yield: The quarterly dividend is $0.435 ($1.74 annualized), for a yield of about 4.68% at $37.21. That is the highest yield in the group, and it reflects a lower share price: the stock is down 27.55% over five years. This year’s raise was small, from $0.43 to $0.435.
Coverage: 2026 Core FFO guidance was raised to $2.38 to $2.43, and the dividend uses about 72.3% of the midpoint. The payout is covered, with less room than at STAG or First Industrial.
Bull case: Rexford plans to sell about $2 billion of non-core assets, has authorized a $1.0B buyback and is keeping a pipeline worth about $50 million of annualized NOI. 99.6% of its debt is fixed-rate. Chief executive Laura Clark said the sales “will further strengthen our portfolio, enhance cash flow durability and increase financial flexibility.”
Risk: Rents keep resetting lower. The portfolio’s cash mark-to-market is about negative 4%, and management said releasing spreads “will stay under pressure for a bit.”
How the Five Rent Checks Compare
Each of these five REITs covers its dividend from FFO with room to spare. STAG has the widest cushion, and EastGroup and First Industrial have the fastest recent dividend growth. Rexford pays the highest yield because the market is pricing in Southern California rent rollbacks, and its fourth-quarter dispositions will show whether that discount is deserved. The next things to watch are First Industrial’s third-quarter occupancy dip and whether Prologis closes the SEGRO deal.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.