5 Overlooked Dividend Stocks Paying More Than 6% Right Now
Five smaller dividend stocks are quietly paying above 6% right now, but the headline yield is the least interesting thing about them. What separates the ones worth owning from the ones setting an income trap comes down to a few…

Most income investors know the big-cap dividend names. These five sit lower on the radar. All five are smaller or specialized NYSE payers in experiential real estate, open-air retail, net-lease industrial, oil and gas royalties, and middle-market lending, and each reported results in its latest quarter that directly affect whether the payout holds. The smallest, CION Investment Corporation (NYSE:CION), has a market cap of just $336 million and only two analyst ratings on file. At current prices, all five yield above 6%. The yield gets it on the list. Coverage, balance sheet, and payout history decide how it ranks, so each section below starts with safety.
CTO Realty Growth
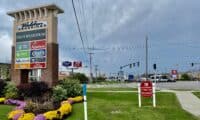
CTO Realty Growth (NYSE:CTO) trades at $20.07 and pays a $0.38 quarterly dividend ($1.52 annualized). That works out to an ultra-high yield of about 7.57%. Its market cap is roughly $774 million, which puts it among the smaller listed shopping-center REITs.
Dividend Safety Read
Coverage looks solid. Management raised 2026 Core FFO guidance to $2.11 to $2.14 per share and narrowed AFFO guidance to $2.22 to $2.25. At the center of that AFFO range, the dividend uses about 68% of cash earnings. The payout has been $0.38 every quarter from March 2023 through September 2026, so the record shows a flat, regular payout. Leverage is moderate, with net debt at 5.9x pro forma adjusted EBITDA, and CTO closed a $1.0 billion amended unsecured credit facility.
Bull Case
Core FFO rose 10% year over year to $0.53 in the third quarter, and revenue grew 24.3%. CTO has invested $472 million so far this year at a 9.4% weighted average yield, mostly in Sun Belt open-air centers. 88% of leases carry contractual rent bumps, and the chief executive pointed to a “$5.6 million signed-not-open leasing pipeline” as support for growth into 2027. All five analysts covering the stock rate it a Buy, with a $24 average target. Shares are up 28.31% over the past year.
Risk to Watch
Total portfolio occupancy fell 180 bps to 92.4% because Zona Rosa was acquired only 67% rented. CTO has also issued 6.2 million shares through its ATM program this year, which dilutes existing holders. AMC, rated CCC+, accounts for 2.5% of base rent.
EPR Properties
EPR Properties (NYSE:EPR) pays a monthly dividend of $0.31, or $3.72 annualized. At $60.50, that is roughly a 6.15% yield. With a $4.56 billion market cap, EPR is the largest name here and the least unknown. Its focus on theaters, ski resorts, and eat-and-play venues sets it apart from conventional REITs.
Dividend Safety Read
2026 FFOAA guidance was raised to $5.49 to $5.57 per share, so the annualized dividend uses about 67% of the center. Tenant rent coverage across the portfolio stands at 2.1x. The monthly payout was raised from $0.295 to $0.31 beginning with the March 31, 2026 ex-date. That continues a run of increases from $0.25 in 2021 to $0.275, then $0.285. Net debt to adjusted EBITDA is 5.0x, and interest coverage is 4.0x.
Bull Case
Third-quarter FFOAA rose 8.8% to $1.49 per share, and the provision for credit losses fell to $0.8 million from $9.1 million. EPR added Live Nation and Life Time as new tenant relationships and raised its investment spending guidance to $675 million to $725 million. Theatre box office is up about 20% year to date, which helps the largest tenant group while management diversifies away from it. Shares have gained 27.97% year to date.
Risk to Watch
Concentration remains the main issue. Theaters make up about 34% of base rent, and the top 10 tenants account for 68%. EPR also has $450 million of 4.75% senior notes due December 15, 2026. The new $1.6 billion credit agreement gives it room to handle that maturity.
Broadstone Net Lease
Broadstone Net Lease (NYSE:BNL) just raised its quarterly dividend to $0.295 from $0.2925, payable January 15, 2027. The forward rate of $1.18 against a $18.35 share price yields about 6.43%. The market cap is around $3.68 billion, which is small relative to its larger net-lease peers.
Dividend Safety Read
Maintained 2026 AFFO guidance of $1.55 to $1.57 means the new dividend uses about 76% of the center. The portfolio is 100.0% occupied, rent collection was 99.9%, and the weighted average lease term is 9.3 years. Tenant risk is spread out: the top 10 tenants make up only 20.6% of base rent. The payout has risen from $0.25 on the March 2021 ex-date to today’s $0.295, with regular raises along the way.
Bull Case
AFFO rose 5.4% to $0.39 per share. BNL broke ground on $325.8 million of build-to-suit at an 8.4% initial cap rate. The biggest is a $303 million advanced-technology facility in Colorado for a Fortune 20 investment-grade tenant, which is expected to become BNL’s largest tenant once rent starts. The committed build-to-suit pipeline totals $456 million, and rent on the new projects is expected to begin in March and June 2027.
Risk to Watch
Leverage rose to 6.6x net debt to adjusted EBITDAre from 5.7x because the revolver funded development. On a pro forma basis, with the forward equity settled, it is 5.4x. Floating-rate debt makes up 30.7% of the total, and 7.1% of base rent expires in 2027.
Kimbell Royalty Partners
Kimbell Royalty Partners (NYSE:KRP) pays a variable quarterly distribution, so its yield depends on which payments you count. Trailing 12-month distributions of $1.60 against a $16.32 unit price give a trailing yield of about 9.80%. The most recent payout was $0.47, up 15% from $0.41. Kimbell’s market cap is about $1.65 billion.
Dividend Safety Read
As a royalty owner, Kimbell does not pay drilling or operating costs, which keeps the model lean. The Q2 distribution used 75% of cash available for distribution, and the rest went to paying down debt. The company carries $478.7 million in debt, or 1.4x net leverage, and raised the borrowing base to $660 million. The payout history shows how much it can swing: $0.13 in mid-2020, $0.55 in August 2022, and $0.35 in late 2025. The payout is variable and moves with commodity prices and cash flow.
Bull Case
Q2 set records. Oil, gas, and NGL revenue exceeded $100 million for the first time, production reached 25,830 Boe/d, and 91 rigs were active on Kimbell acreage. Kimbell announced more than $360 million in acquisitions in 90 days, including Mesa Royalties. Units are up 50.74% year to date. Third-quarter results and the next distribution are due with the November 5, 2026 earnings call.
Risk to Watch
Q1 showed the downside: EPS came in at $0.04, missing the $0.21 estimate, after an $18.7 million derivative loss. Kimbell is also a K-1 issuer. An estimated 47% of the Q2 distribution is a return of capital, which reduces your cost basis rather than counting as current income. That makes tax reporting more complicated than with a standard 1099 dividend.
CION Investment Corporation
CION pays $0.10 a month, or $1.20 annualized. At $6.83, that is a yield of about 17.57%, the highest on this list. That yield comes with the most risk of the five.
Dividend Safety Read
Net investment income covered the distribution only 0.97x in Q2 and 0.83x in Q1, so earnings fell short of the payout in both quarters. CION already cut its distribution this year, from $0.36 quarterly in 2025 to the current monthly rate. Payments are declared through the December 28, 2026 payment date. Leverage is declining: net debt to equity fell to 1.52x from 1.62x, and the Series A Notes were repaid at par on August 31, 2026.
Bull Case
NAV rose 3.5% to $13.57 per share, roughly double the share price. Non-accruals fell to 1.44% of fair value, and 80.8% of the portfolio is first-lien senior secured. The board added $50 million to the buyback, bringing the total authorization to $130 million. The chief executive said, “We continue to believe our stock is significantly undervalued relative to our net asset value.”
Risk to Watch
Shares are down 18.84% year to date. Weighted average leverage at portfolio companies rose to 5.07x, and their interest coverage fell to 1.87x. Third-quarter results on November 5, 2026, will show whether coverage returns above 1.0x.
Five Income Streams Most Portfolios Miss
CTO, EPR and Broadstone show the strongest coverage in this group: each pays out roughly two-thirds to three-quarters of its cash earnings, and that cash flow keeps growing. Kimbell adds commodity-linked upside and takes a variable check in return. CION offers the biggest yield and the deepest NAV discount, and November 5 will show whether its distribution coverage is improving. Across all five, payout coverage matters more than the headline yield (we put the seven warning signs that a big yield is about to be cut into a free dividend trap guide if you want the full checklist).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.