A Stock That Has Raised Its Dividend Every Year Since 1963 Just Hit a Record High. It Handed a Couple Living on the Checks a $67,000 Reason Not to Sell

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

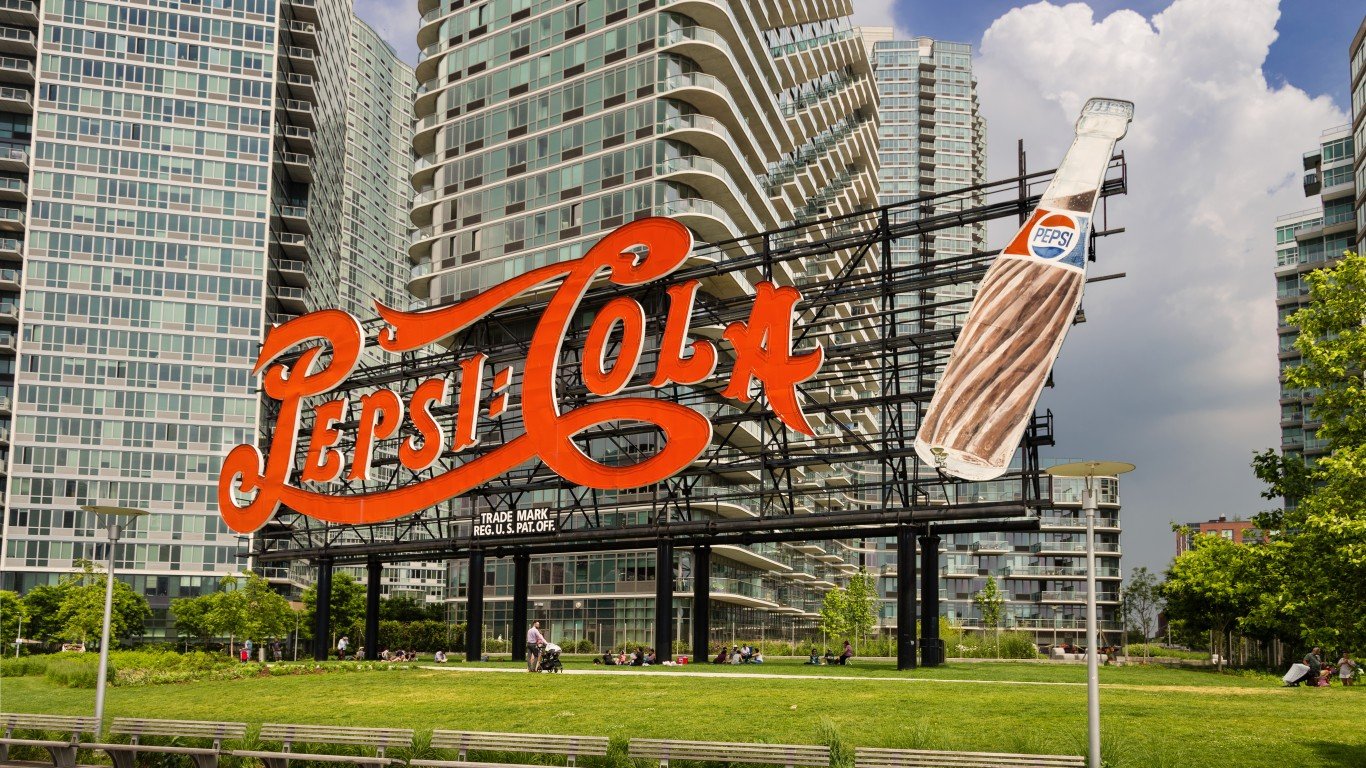
A beverage maker that has raised its dividend every year since 1963 closed Friday at a record $99.25 a share, up 42% this year. For a retired couple who own 20,000 of its shares and live on the checks, the record high raises a question they have not had to ask in years: whether to sell some. The answer in their numbers is a $67,000 reason to leave the shares alone, and it starts with a federal income tax bill of $0 on about $100,000 a year of income.
The couple is a scenario, built to show the arithmetic. He is 70 and she is 68. At the end of 1999 he bought 10,000 shares for about $580,000, the 2012 split doubled the count to 20,000, and he never sold. At Friday’s close the lot is worth about $1,980,000. They collect $4,000 a month in Social Security between them and keep $300,000 in Treasury bills and CDs, which earn about $12,000 a year. The dividend on the 20,000 shares is $42,400 a year, $10,600 every quarter. Everything else, their house and their cars, is paid for.
A record high in a stock you bought for the checks reads as a signal to take some money off the table, and that is a fair reading; the limit is that the tax bill on a 27-year-old gain is the biggest number in the decision, and no tax rule makes 87% of your money in one stock safe. Here is what the shares pay, what they did to this couple for a decade, what the IRS takes from a household living on the dividends, and what cashing in a quarter of the position at the top would cost.
What the checks pay
The beverage maker pays $0.53 a share every quarter, $2.12 a year, after a 3.9% raise in February. That was the 64th straight annual increase. On the couple’s 20,000 shares the dividend is $42,400 a year, and at Friday’s price the yield is 2.1%. A 10-year Treasury pays 5.1%, so if you are buying today you are paying for the record of raises, not for the income.
The couple’s own yield is a different number. In 2000 the same lot paid $6,800. In 2016 it paid $28,000. This year it pays $42,400, 6.24 times the first year’s check and 7.3% on what they paid in 1999. Over 27 years the dividends alone have returned $620,800, more than the $580,000 they put in, and the shares are still worth 3.4 times their cost.
The decade the price went nowhere
The purchase was badly timed. The beverage maker had been a market darling in the 1990s, and from the end of 1999 the shares fell for three years. By March 2003 the lot was worth 36% less than the couple paid, and the price did not close above the 1999 level for good until September 2010, 10.7 years later.
What they had during those years was the check. From 2000 through 2010 the shares paid $127,200 in dividends, 22% of the cost, and the amount rose every year. That is the case for a stock like this in a retirement plan: the income arrived while the price went nowhere, and it grew. If you own a dividend stock that has gone sideways for years, that is the number to look at before the price.
The tax bill on living off the checks
Their income this year comes to $102,400: $48,000 of Social Security, $42,400 of dividends and $12,000 of interest. Here is the federal return, married filing jointly, 2026 rules.
Social Security first. Their provisional income is $78,400 (the dividends and interest plus half the benefits), so 85% of the benefits over the $44,000 line plus $6,000 comes in as taxable: $35,240 of the $48,000. That puts adjusted gross income at $89,640.
Then the deductions. The standard deduction is $32,200, plus $1,650 for each spouse over 65, plus the $6,000 senior deduction for each of them, which is available in full because their income is under $150,000. That is $47,500 off the top, which is more than the $47,240 of Social Security and interest combined. Taxable income is $42,140, and every dollar of it is qualified dividends.
Qualified dividends are taxed at 0% until taxable income passes $98,900 for a couple. Theirs is $42,140. The federal income tax bill is $0.
You can run the same check on your own numbers: as long as your ordinary income (pensions, interest, IRA withdrawals, the taxable part of Social Security) fits inside your deductions, qualified dividends up to $98,900 are tax-free. The line is easy to cross. A $5,000 IRA withdrawal would cost this couple $899, because it also pulls more of their Social Security into the taxable column. A $10,000 withdrawal would cost $1,530.
What selling a quarter would cost
Say they sell 5,000 shares at the record, $496,250. The basis on those shares is $29.125 each, $145,625, so the long-term gain is $350,625.
That gain lands on top of everything else. Adjusted gross income jumps to $445,825. The senior deduction is gone, because it phases out above $150,000. The first $81,600 of dividends and gains still sits in the 0% band, and the remaining $311,425 is taxed at 15%, $46,714. The 3.8% net investment income tax applies to income above $250,000, another $7,441. Ordinary tax on the interest and the now fully taxable Social Security adds $1,730. The federal bill goes from $0 to $55,885.
Medicare sends a second bill two years later. A joint income of $445,825 is above the $410,000 line, so each spouse pays a Part B surcharge of $446.30 a month at 2026 rates, $10,711 for the year between them, plus a smaller Part D surcharge. The cost of selling a quarter of the position at the top is about $67,000, 13% of the proceeds.
The $429,654 they keep would earn $21,912 a year in a 10-year Treasury at 5.1%, against the $10,600 of dividends the 5,000 shares were paying, so the sale buys about $11,000 a year of extra income. The interest is ordinary income, so part of it is taxed. At that rate the $67,000 takes about six years to earn back. Selling everything would cost about $296,000 in federal tax alone.
When selling anyway makes sense
Two things can make the tax worth paying. The first is concentration: 87% of this couple’s money is in one stock, and a dividend cut, which the beverage maker has not made in 64 years, would take $42,400 a year with it. If you cannot sleep with that, sell in stages, keeping each year’s gain inside the 15% band, which runs to $613,700 of taxable income, and your income under the Medicare lines when you can.
The second is the opposite choice. If the plan is to leave the shares to the children, the gain of $1,402,500 disappears at death. Heirs take the shares at their market value on that day and owe nothing on the 27 years of appreciation. For a couple who can live on the checks, that is the strongest argument of all for leaving the lot alone, and it is why the tax rules, more than the stock price, should settle the question.
The bottom line
The beverage maker closed at a record $99.25. The couple’s 20,000 shares pay $42,400 a year, their income is about $100,000, and their federal income tax bill is $0. Selling a quarter of the shares at the top costs about $67,000 in tax and Medicare surcharges for about $11,000 a year of extra income. The record high is a reason to check the plan. For this couple, the numbers say keep collecting the checks.
Contact [email protected] for any questions or corrections.
I've spent more than 15 years inside enterprise software, working alongside the finance, sales operations, and HR leaders who run the revenue engines at some of the largest tech companies in the country.
My day job is helping enterprise executives make smarter decisions about retention, compensation, and growth. These are the same operational levers that show up in every earnings report investors actually read. That perspective shapes my writing for 24/7 Wall St.
The headline numbers are easy. The interesting stuff is underneath: how companies make money, what executives are worried about, and what any of it means for the person checking their 401(k) on a Sunday afternoon. I write about personal finance and business as someone who has spent her career inside the rooms where these decisions get made.