The Federal Reserve’s April Inflation Forecast Was Bad News for Stock Market Bulls, and Things Have Only Gotten Worse
The stock market staged a sharp recovery in April 2026, but the Federal Reserve's inflation outlook threatened to cut it short. Since then, Jerome Powell has been replaced by Kevin Warsh as Fed chair, core PCE has risen to 3.3%,…

The stock market staged a sharp recovery in mid-April 2026, but the Federal Reserve’s inflation outlook at the time threatened to cut it short before bulls could fully celebrate. Since then, conditions have deteriorated further: the Fed has raised rates, a new chair is in place, and the 10-year Treasury yield has climbed toward levels not seen since 2007.
The Rally Was Real. So Was the Inflation Risk.
SPDR S&P 500 ETF Trust (NYSEARCA:SPY) gained 3.53% over the week ending April 16, 2026, with the S&P 500 recovering all losses from the U.S.-Iran conflict that began in late February. Invesco QQQ Trust Series 1 (NASDAQ:QQQ) added 5.17% in the same week, sitting on its longest winning streak since 2021. SPDR Dow Jones Industrial Average ETF Trust (NYSEARCA:DIA) tacked on 1.16% over the same period.
Inflation refused to cooperate with that recovery narrative. Core PCE held at 2.97% year-over-year in February 2026, and the Cleveland Fed’s Nowcasting tool showed April projections moving higher through early April. The Strait of Hormuz closure disrupted roughly 20% of global daily oil supply, and WTI crude was sitting at $100.72 per barrel after spiking to $114.58 on April 7. Diesel peaked at $5.67 per gallon. Guggenheim Partners warned that sustained oil near $100 per barrel could trigger a 10% equity selloff.
What Investors Were Watching in April
At the time, the Fed held rates at 3.75% and Powell flagged a near-term inflation spike from energy prices. With the market entering 2026 at a forward P/E around 22x, any signal that the rate-cut timeline would be pushed back threatened to compress valuations with little cushion. The 10-year Treasury yield at 4.26% was already a headwind for growth stocks. The rally looked real, but the inflation trajectory left bulls with almost no margin for error.
How the Picture Has Shifted Since April
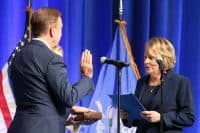
The months since that April assessment have validated the concern, and then some. Jerome Powell’s tenure as Fed chair ended in May 2026, when Kevin Warsh was sworn in on May 22 as the 17th chair of the Federal Reserve, following a 54-45 Senate confirmation. Warsh, who previously served as a Fed governor during the 2008 financial crisis, has made inflation discipline a central theme of his tenure.
By the time of the April 28-29 FOMC meeting, the Fed’s own staff review confirmed that core PCE inflation had moved to 3.0% and that prices were being pushed higher by a sharp increase in energy costs. April’s actual core PCE reading then came in at 3.3% year-over-year, with headline PCE at 3.8%, as the Iran conflict and tariff pressures continued to feed through the supply chain. Rather than cutting rates as markets had hoped entering 2026, the Fed reversed course entirely. In September 2026, the FOMC voted unanimously to raise the federal funds rate by 25 basis points, bringing the target range to 3.75% to 4%, the central bank’s first rate increase since 2023. Futures markets quickly priced in at least one additional hike before year-end.
The bond market has delivered an equally stark message. The 10-year Treasury yield, which stood at 4.26% when this article first ran, climbed to around 5% by mid-September 2026, touching 19-year highs ahead of the FOMC decision. At that level, the valuation cushion for growth stocks is considerably thinner than bulls had hoped when the spring rally was underway.
Oil prices have remained a central pressure point. WTI crude was trading near $97 to $102 per barrel in mid-to-late September, with a 52-week range spanning from roughly $55 to nearly $118. The September Fed rate hike, combined with Warsh’s pointed comments on inflation, rattled equity markets, with the Dow dropping sharply on the day of his remarks. The Fed’s own updated projections have since raised the 2026 core PCE forecast to 3.4%, up from the 3.3% projected in June, a signal that policymakers see little near-term relief.
The April warning that inflation would leave bulls with no margin for error has, in the months since, proven accurate.
Editor’s note: This article has been updated to reflect that Jerome Powell was succeeded by Kevin Warsh as Federal Reserve chair in May 2026, that core PCE inflation rose to 3.3% in April and the Fed’s full-year 2026 core PCE projection was subsequently raised to 3.4%, that the Fed raised the federal funds rate by 25 basis points to a target range of 3.75% to 4% in September 2026 (its first hike since 2023), and that the 10-year Treasury yield climbed to approximately 5% ahead of that decision.
Contact [email protected] for any questions or corrections.