They Sold the Family Home for a $700,000 Gain. The IRS Only Ever Saw $200,000 of It
The IRS built a massive tax shelter directly into the home sale rules, and most homeowners walk past it without a second glance. Knowing exactly how it works, and where it breaks down, can mean the difference between a five-figure…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
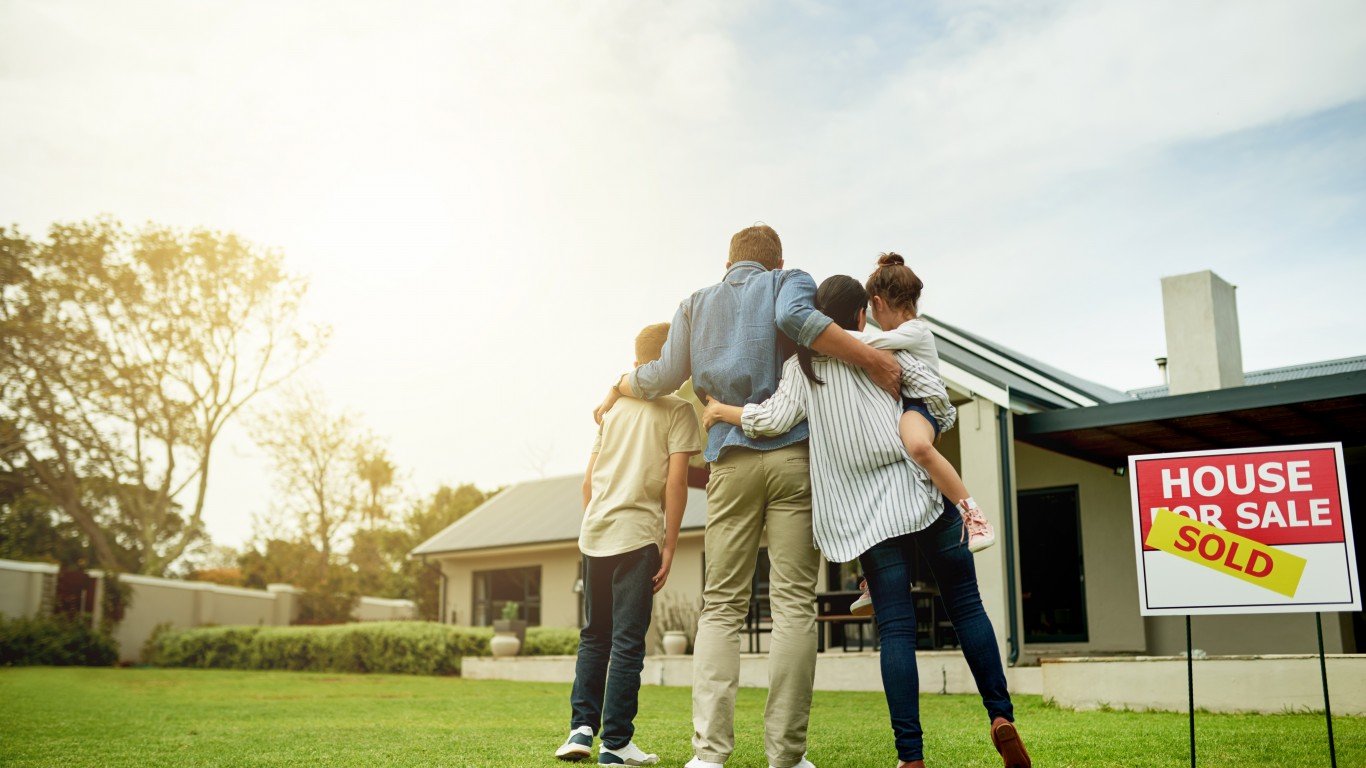
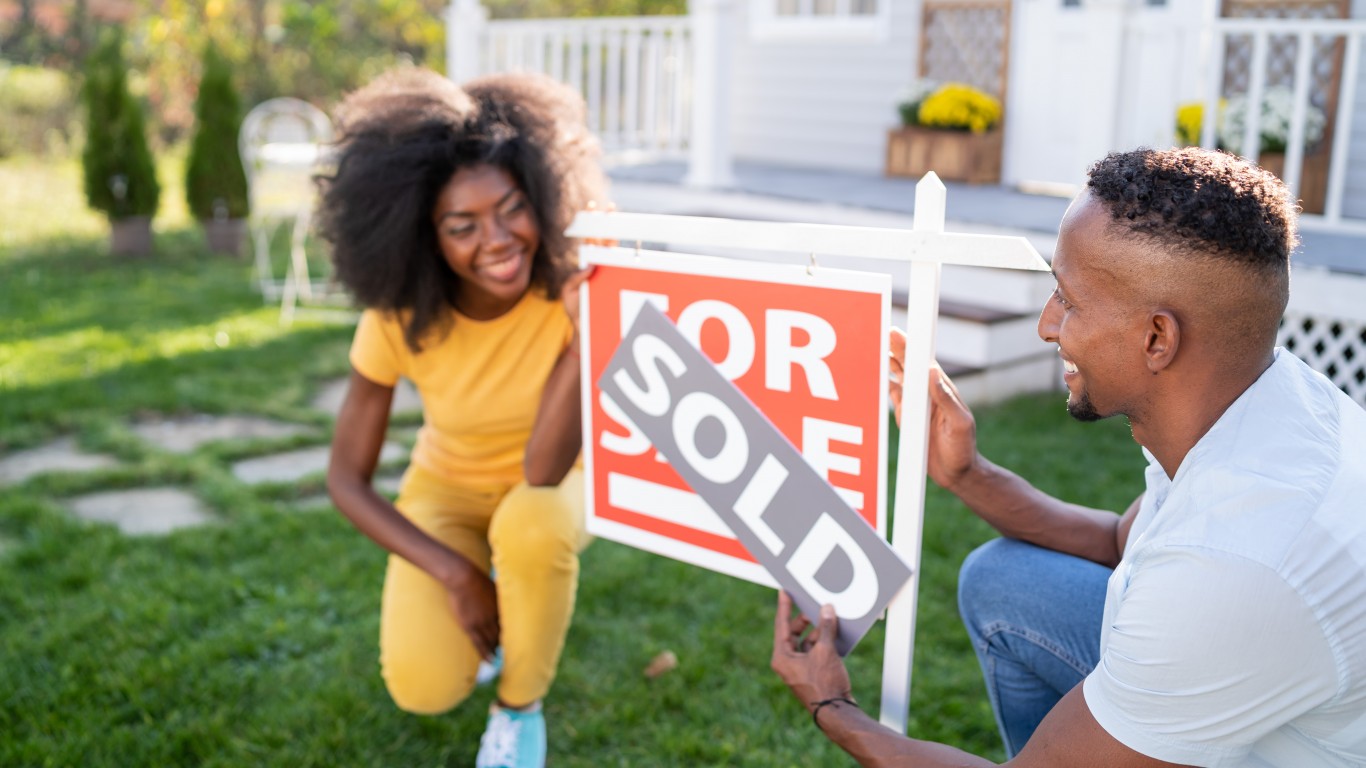
If you own a home you’ve lived in for a few years, the IRS is quietly offering you one of the biggest tax-free windfalls in the entire tax code. When a married couple sells the family house for a $700,000 gain, they can legally erase $500,000 of it before the IRS ever sees a dollar. Only $200,000 shows up as taxable income. This is the Section 121 home sale exclusion, and it applies to your primary residence. Not a rental, not a flip.
Gains this size are no longer a coastal fantasy. According to the National Association of Realtors, the median existing-home price reached $434,100 in July 2026, up 2.0% year-over-year and marking the 37th consecutive month of price increases. Sales ran at a seasonally adjusted annual pace of 4.06 million units, and prices in the Northeast topped $563,800. For long-term owners in appreciating markets, six-figure gains have become routine.
The Buried Rule in Plain English
When you sell your primary residence, Section 121 lets you exclude up to $250,000 of capital gain if you’re single, and up to $500,000 if you’re married filing jointly. The gain is your sale price minus your cost basis (what you paid, plus qualifying improvements, minus selling costs). Everything under the cap is invisible to the IRS. Everything above it gets taxed at long-term capital gains rates, typically 0%, 15%, or 20% depending on your income.
So a married couple with a $700,000 gain reports the sale, subtracts the $500,000 exclusion, and arrives at $200,000 of taxable long-term gain. That is the whole trick.
The Statute That Makes It Real
The authority is 26 U.S. Code §121, enacted by the Taxpayer Relief Act of 1997. IRS Publication 523 (Selling Your Home) walks through the mechanics. Congress set the $250,000 and $500,000 thresholds in 1997 and has never indexed them for inflation. The Consumer Price Index rose 3.5% year-over-year through June 2026, according to the Bureau of Labor Statistics, and the real purchasing power of those caps has eroded sharply since the rule first took effect. The result: more sellers hit the ceiling every year.
The scale of the problem has grown considerably. NAR research finds that nearly 29 million homeowners, roughly 34% of all current owners, already face potential capital gains taxes if they sell. That figure is projected to climb toward 56% by 2030 and approach 70% by 2035.
Those numbers have drawn attention on Capitol Hill. The More Homes on the Market Act (H.R. 1340), introduced by Rep. Jimmy Panetta (D-CA) and Rep. Mike Kelly (R-PA) in February 2025, is a bipartisan bill that would double the exclusion limits to $500,000 for single filers and $1 million for married couples, then index both figures to inflation going forward. A separate measure, the No Tax on Home Sales Act (H.R. 4327), introduced by Rep. Marjorie Taylor Greene (R-GA) in July 2025, would eliminate the dollar caps entirely for qualifying homeowners. Neither bill has been enacted as of this writing, so the 1997 limits remain in force.
Who Qualifies, and Who Doesn’t
To claim the full exclusion, you must pass two tests during the five-year period ending on the sale date:
- Ownership test: You owned the home for at least 24 months.
- Use test: You lived in it as your main home for at least 24 months (the months don’t have to be consecutive).
For the $500,000 married cap, either spouse can satisfy the ownership test, but both must meet the use test, and neither can have claimed the exclusion on another sale in the prior two years. Vacation homes, pure investment properties, and houses you’ve owned less than two years generally don’t qualify. Time a property spent as a rental after 2008 can also reduce the exclusion under the “non-qualified use” rules.
How to Actually Use It
- Rebuild your basis. Start with your purchase price. Add closing costs you paid, plus every capital improvement: new roof, kitchen remodel, addition, HVAC replacement. Routine repairs don’t count. A higher basis means a smaller taxable gain.
- Confirm the 2-of-5 clock. Pull your prior tax returns and utility records if needed. The months you lived in the home as your main residence are what matter, and they don’t have to be consecutive.
- Run the math before you list. If your projected gain is $520,000 and you’re married, waiting a few months to cross the 24-month use test can save five figures in tax. The arithmetic is worth doing early.
- Report it on Form 8949 and Schedule D only if the gain exceeds the exclusion or you received a Form 1099-S. If neither applies, you generally don’t have to report the sale at all.
- Apply the exclusion, then tax the rest at long-term capital gains rates (0%, 15%, or 20%), plus the 3.8% Net Investment Income Tax if your modified AGI crosses the relevant threshold.
The Catch Most Sellers Miss
You can only claim the full Section 121 exclusion once every two years. Sell two homes inside a 24-month window and the second sale gets no exclusion, unless the move was forced by a job change of at least 50 miles, a health reason, or an unforeseen circumstance defined in the regulations. In those cases, a prorated exclusion may apply.
The other trap is the frozen cap. The $250,000 and $500,000 limits haven’t moved a dollar since 1997, and the math is becoming harder to ignore. With the median existing-home price at $434,100 and prices across the country up for 37 straight months, more sellers are clearing the exclusion ceiling every quarter. If your projected gain is anywhere near the cap, document every improvement you made to the property. Each qualifying dollar added to your basis is a dollar the IRS never touches.
Editor’s note: This update refreshes the housing market data to the July 2026 NAR report (median price $434,100, 37th consecutive month of year-over-year gains, 4.06 million annualized sales pace) and adds NAR research showing that nearly 29 million homeowners, about 34% of all current owners, already face potential capital gains taxes if they sell. It also notes the bipartisan sponsorship of H.R. 1340 by Reps. Panetta and Kelly.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.