Medicare Pays for Home Care Only When It’s Intermittent. That Meant a Nurse Twice a Week, Not the $6,700 a Month of Help Mom Actually Needed
Medicare approved a nurse twice a week after Mom came home from the hospital, and the family exhaled with relief. Then the first month's caregiving bill arrived.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
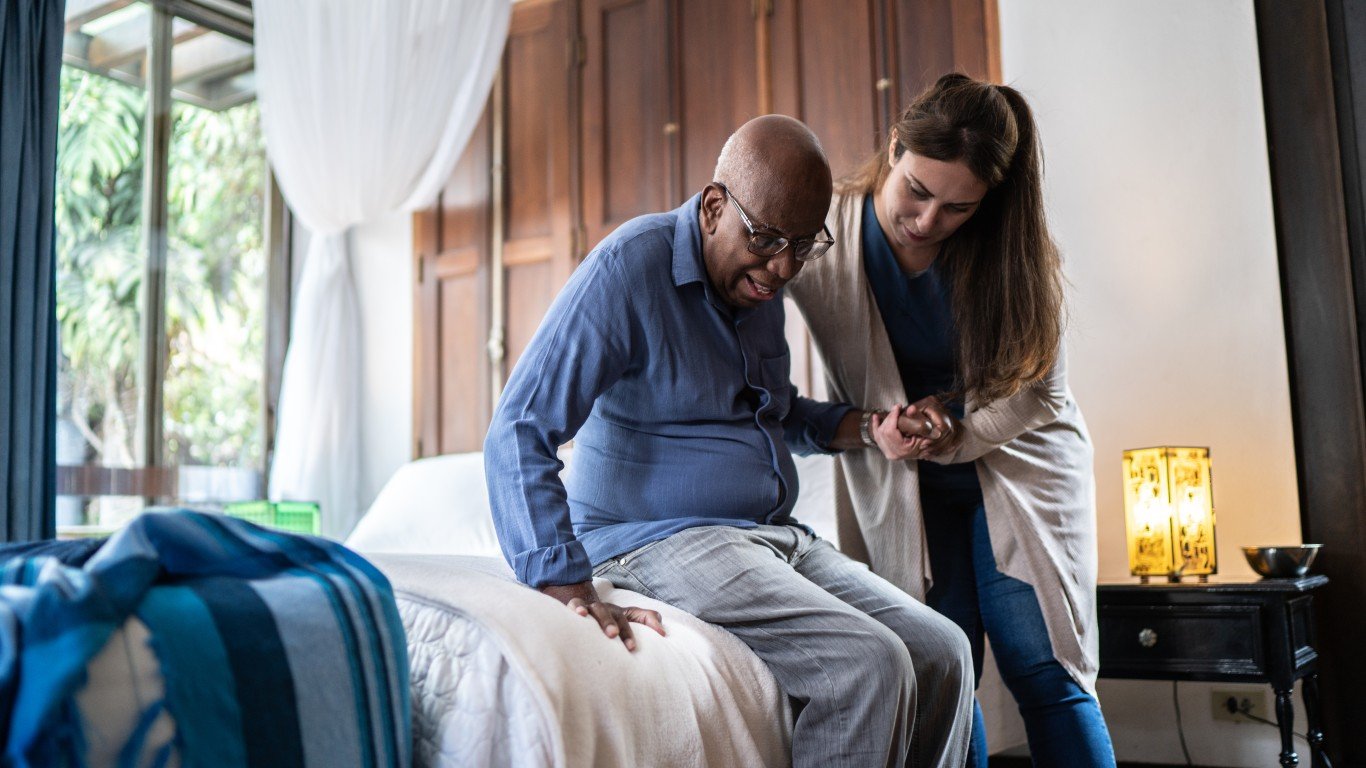
Picture an 82-year-old widow discharged home after a hospital stay, with a surgical wound that needs monitoring. Medicare approves a home health nurse twice a week and a physical therapist for a few visits. The family assumes home health also means someone providing those services for roughly 44 hours every week. It does not. Medicare may cover limited aide visits while the skilled-care lasts, but it does not pay the ongoing standalone help that costs a national median of $6,673 a month.
The term doing the damage on the coverage letter is intermittent. Medicare home health covers part-time or intermittent skilled care for homebound patients, defined as generally no more than eight combined hours a day and 28 hours a week, with a provider able to authorize up to 35 hours in limited circumstances. Those are ceilings. A plan calling for two nurse visits a week allows just that.
What Medicare Actually Sends Through the Door
To qualify for the Medicare home health benefit, the patient generally must be homebound, need a qualifying skilled service (nursing or therapy), have care ordered by a provider, and use a Medicare-certified agency. Covered services carry no beneficiary cost under Original Medicare. The complaint centers on scope: most of the hours Mom needs fall outside the benefit entirely.
Two categories of help get bundled in everyday conversation and split apart in the rulebook:
- Skilled care: wound treatment, injections, monitoring an unstable condition, and physical, occupational or speech therapy.
- Custodial care: bathing, dressing, toileting, meal preparation, housekeeping and supervision.
Medicare can add limited home health aide hours, but only while the patient is also receiving qualifying skilled services. Once the nurse or therapist closes the case, the aide piece generally goes with them, even if Mom still can’t safely step into a shower. Medicare doesn’t cover round-the-clock care, and it doesn’t cover custodial help as a standalone service.
Medicare, the federal health program tied to age 65 or disability, differs from Medicaid, the joint federal-state program that becomes the payer of last resort for long-term custodial care, with rules that vary by state.
Where the $6,700 Number Comes From
CareScout’s 2025 Cost of Care Survey, released in March 2026, puts the median non-medical caregiver rate at $35 an hour. At 44 hours a week, that works out to $80,080 a year or $6,673 a month. CareScout now folds the old homemaker and home health aide categories into a single “non-medical caregiver” line.
That figure covers roughly six hours a day, enough to get someone up, fed, cleaned, and settled, with nights and long midday stretches still uncovered. Round-the-clock care can run three to four times higher.
Household budgets generally don’t stretch that way. The BEA reports a personal savings rate of 2.8% as of Q2 2026, and the 2027 Social Security cost-of-living adjustment is currently tracking toward the mid-3% range. But a COLA bump of a few dollars a month doesn’t move the meter on a $6,673 bill.
Filling the Gap Without Going Broke
A handful of levers exist, and none of them work in isolation:
- Medicaid home and community-based services (HCBS) waivers can cover personal assistance for financially and functionally eligible applicants. Availability, income and asset rules, and waiting lists vary sharply by state. Some states move applicants through quickly. Others keep HCBS waiver lists years long.
- Long-term care insurance may pay for home care once the policy’s benefit trigger (typically two activities of daily living or cognitive impairment) is met.
- VA benefits, including Aid and Attendance, may help certain wartime veterans and surviving spouses.
- Medicare Advantage plans sometimes offer limited in-home support as a supplemental benefit. A handful of meals or aide visits per year falls well short of long-term care coverage.
Before the first home health visit, families can ask the agency for the written plan of care and pin down four things: which services Medicare has approved, how many visits or hours the agency will actually provide, how long the skilled need is expected to last, and which bathing, meal and supervision needs remain uncovered. If the agency plans to deliver something Medicare won’t pay for, it must issue an Advance Beneficiary Notice first.
Medicare walked the nurse through the front door twice a week. It never promised to stay for the other six hours Mom needed help. Now the family must fill in those gaps, but knowing what they can expect helps to build the care around the clock.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.