Dolly Parton’s Former Cottage Fetches Nearly $2 Million. Retirees Selling Their Own Property Can Face Higher Medicare Premiums Long After Moving Out
Selling a home you owned for decades can feel like cashing out a second retirement account, but Medicare has its own opinion about that windfall and will send the bill to your future self at exactly the wrong moment.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
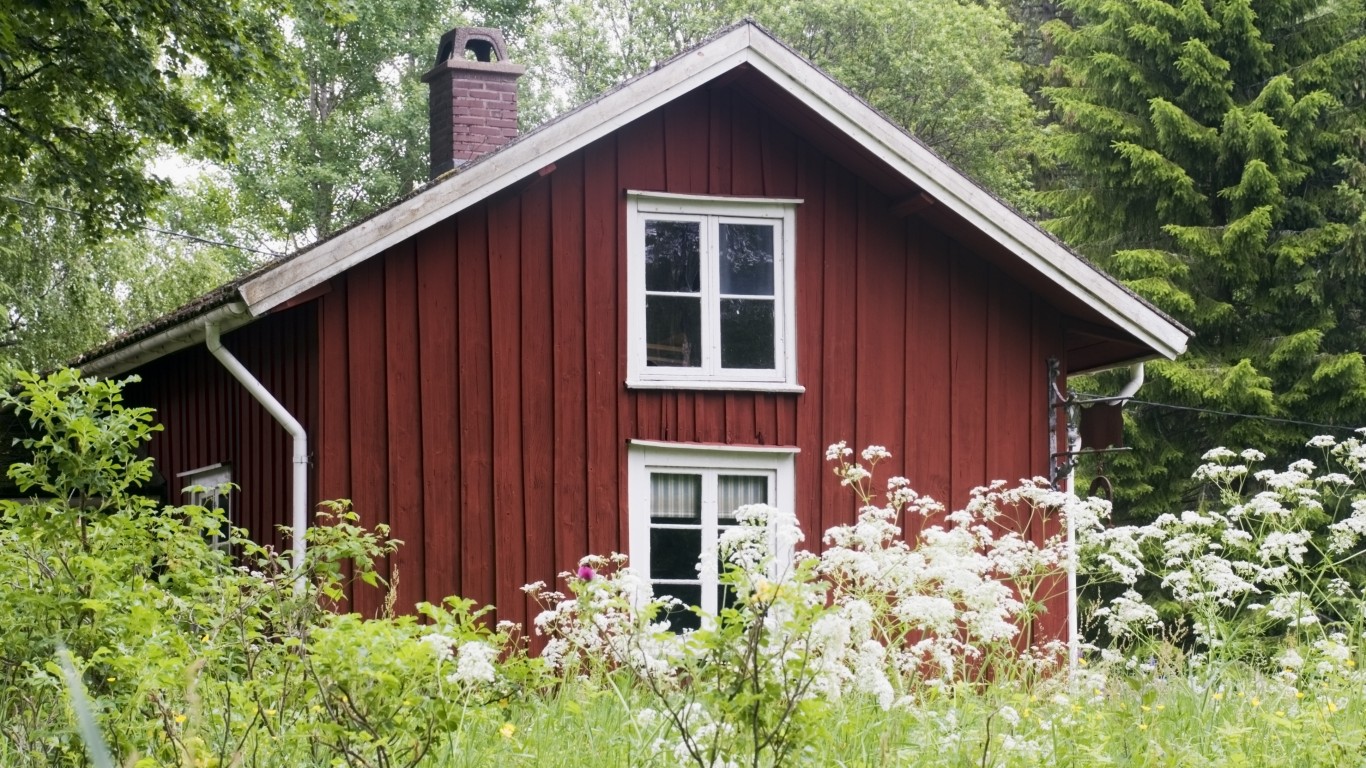
Dolly Parton’s former cottage in Solvang, California, has been sold for $1,945,150. The country music icon owned the whimsical property for years before selling it, and its latest owners brought it back to market with a $1.995 million asking price.
Buyers noticed. The cottage drew five offers and interest from 10 serious buyers before the sale closed, according to Homes.com.
A sale like that makes a house owned for decades look like a retirement account with a front porch. Imagine a 70-year-old single woman who has owned her home for decades. She downsizes, deposits the money and assumes Medicare has nothing to do with the sale. Two years after she moves in, her Part B and Part D premiums can rise because of a house she no longer owns.
Medicare looks only at whether the sale leaves taxable capital gain on her federal return. Only about 8% of Part B enrollees pay the income surcharge at all. Home sellers who end up paying it usually have a large gain on top of steady pension or IRA income.
Taxable Gain Drives Your Medicare Bill
Gain starts with the selling price, minus selling expenses, minus adjusted basis, which usually starts with what she paid and goes up with capital improvements. The IRS gives examples such as putting an addition on your home, replacing an entire roof, paving your driveway, installing central air conditioning and rewiring. Every documented improvement eats into the gain. Medicare sees only what lands in adjusted gross income, so a big sale price coupled with a high basis can leave very little behind.
Home-Sale Exclusion Can Erase Most of the Gain
An eligible homeowner can exclude up to $250,000 of gain on the sale of a main home, or $500,000 on a joint return in most cases. She generally must have owned and lived in the home for two of the five years before the sale.
Our seller paid $300,000 decades ago. Improvements raised her adjusted basis to $450,000, and she clears $800,000 after selling expenses. Her gain is $350,000. As a qualifying single filer, she excludes the first $250,000, leaving $100,000 taxable. That $100,000 is the only part of the $800,000 proceeds that enters her income for the Medicare calculation.
Widows face a sharper version of this. A surviving spouse who has not remarried can still qualify for the joint-size exclusion if the sale happens within two years of the spouse’s death. Other conditions must also be met. Waiting past that window drops the exclusion to the single-filer limit.
Medicare Bill Arrives Two Years After the Moving Truck
Social Security sets the income surcharge, called IRMAA, using modified adjusted gross income (MAGI). MAGI is adjusted gross income with tax-exempt interest added in, so municipal bond income counts. Social Security generally looks at income from two years earlier: 2026 premiums use tax year 2024. That means a 2026 sale generally affects 2028 premiums.
The 2028 thresholds and premiums have not been set, so the 2026 figures from CMS and Social Security serve as a yardstick. This year, individual filers with MAGI at or below $109,000 pay no surcharge, and neither do joint filers at or below $218,000. The standard Part B premium is $202.90 a month. Even the lowest surcharge tier adds $81.20 to Part B, bringing it to $284.10, plus $14.50 a month on Part D. IRMAA is one of several Medicare costs that surprise retired people, which is why we mapped out the surcharges and coverage gaps in a free guide here.
Her usual $80,000 of MAGI plus the $100,000 taxable gain puts her sale-year MAGI at $180,000. Under today’s schedule, that is well past the single-filer line and into surcharge territory. The surcharge generally lasts one premium year, because the next year’s premium looks back to a tax return without the sale on it.
Selling the House Is No Form SSA-44 Escape Hatch
Social Security can make a new decision after certain life-changing events that decrease income. These include marriage, divorce or a spouse’s death, stopping or reducing work, losing income-producing property because of a disaster or another event beyond the person’s control, and certain employer pension changes. A voluntary home sale fits none of them. She cannot ask Social Security to leave out one unusually good year.
She still has options if something else changes. If she separately stops working or loses pension income, Form SSA-44 lets her ask for a new decision based on her lower income.
Find the Forgotten Receipts Before Listing
Gather records for every qualifying improvement: roof, addition, kitchen remodel, HVAC, fencing, driveway. Routine repairs such as repainting, fixing gutters or floors, fixing leaks and replacing broken window panes generally do not add to basis.
Get a tax estimate before picking a closing date. A December closing and a January closing fall in different tax years, which means they affect different premium years. If she also plans a Roth conversion, a large IRA withdrawal or a major stock sale, putting them in the same year as the home sale piles all that taxable income onto one return. Spreading them across separate years keeps each year’s MAGI lower.
A nearly $2 million sale makes a great deal. The number that determines Medicare exposure is the taxable gain left after basis, selling costs and the exclusion, and she could be settled in her new place for two years before Medicare bills her for the old one. Before she signs a sale contract, she should know how much of the gain the IRS will count as income. She should know which year’s premiums it will hit.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.