She’ll Stay in Her Paid-Off Denver Home as Prices Rise. Once Her Equity Tops $1.13 Million, Medicaid Could Block Nursing-Home Coverage Without a Sale
A Denver widow who never sold, never refinanced, and never moved still finds Colorado's Medicaid rules closing in around her, driven entirely by a market she never participated in.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Freddie Mac’s average 30-year fixed rate rose for seven straight weeks, from 6.65% on August 20 to 7.4% on October 8. It held there the following week and has since eased to 7.24%. Existing-home sales ran at a 3.99 million annual pace in September, one of the slowest months of the year.
For a Denver homeowner who paid off her house years ago, staying put doesn’t stop her equity from rising. Colorado applies a $1,130,000 home-equity limit in 2026 to many people seeking long-term-care Medicaid. If no exception applies and she owes nothing on the house, her equity equals its market value whether or not she plans to sell.
How Colorado’s $1,130,000 Home Equity Limit Works
A primary home can usually be excluded from Medicaid’s ordinary asset test, but long-term-care coverage has a separate home-equity limit. Equity is the property’s market value minus debt secured by it, so with no mortgage or home-equity loan, equity equals value.
For 2026, the federal range runs from $752,000 to $1,130,000. Colorado uses the higher figure, as do states including New York, Massachusetts and Washington. California currently has no home-equity limit. Most states use the lower figure, so an identical house can receive very different treatment across state lines.
For someone seeking long-term-care Medicaid, home equity is part of the financial eligibility test. A house that otherwise receives favorable treatment can still create a problem when the owner’s equity rises above the state’s limit.
There are important exceptions. The limit does not apply when a spouse, a child under 21 or a blind or disabled child lives in the home. Federal rules also allow a hardship waiver in qualifying cases.
How a $230,000 House Crosses $1.13 Million Without a Sale
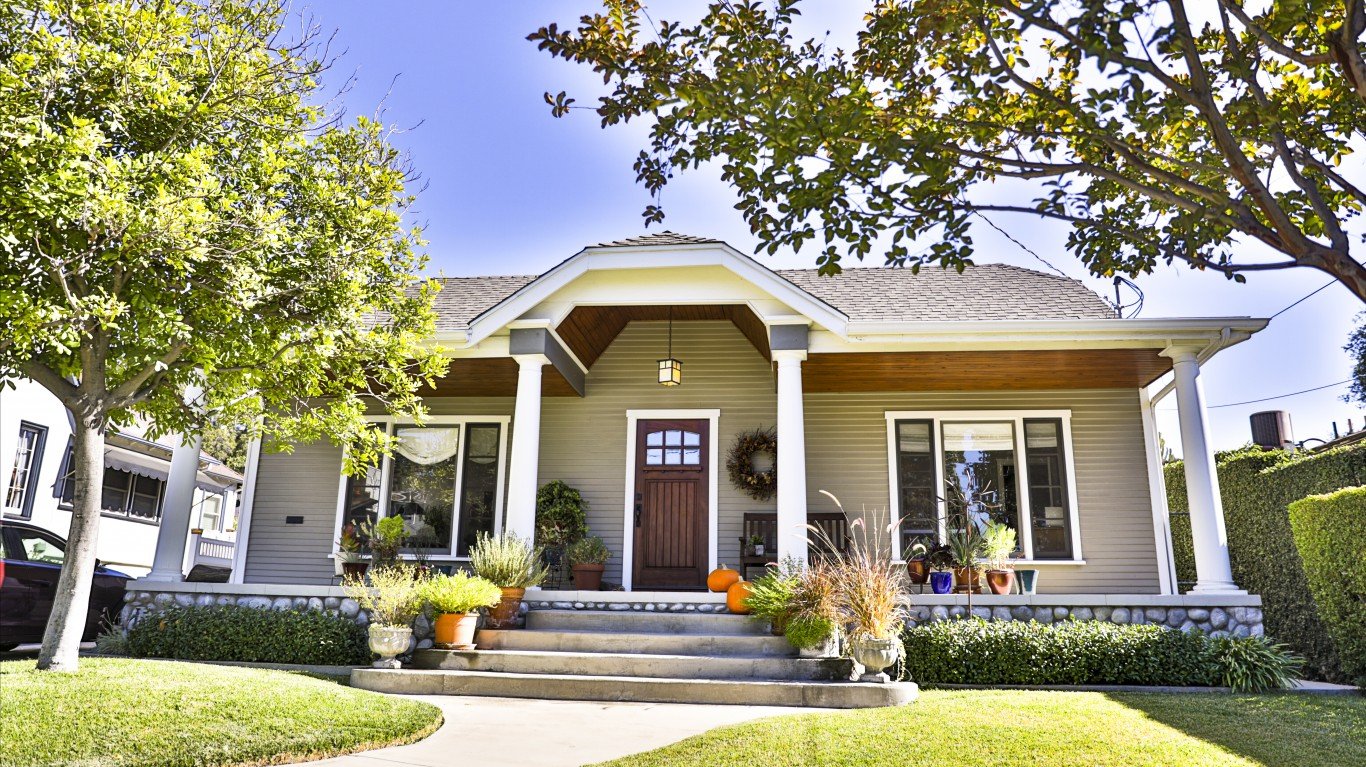
Consider a widow who bought a Denver bungalow in early 1995 for $230,000. She paid off the mortgage, never refinanced and never sold. The Denver metro’s FHFA house price index rose from 100 in early 1995 to 492.5 in the second quarter of 2026. If her house merely kept pace with the metro index, its estimated value would be about $1,132,750, just $2,750 over Colorado’s cap.
Back at the end of 2020, the same house would have been worth about $845,503, well under the limit. She did nothing different. The market did the work.
Lately, Denver prices have barely moved. The index fell 0.46% over the past year and sits just below its recent peak of 496.35. It’s still up 21.44% over five years. Low sales volume shows how few homes are changing hands, and it tells a caseworker nothing about whether her particular house has lost value.
A tighter ceiling is coming. Starting in January 2028, federal law caps the maximum home-equity limit for non-agricultural homes at $1 million, so Colorado will no longer be able to use a higher figure. Homes on land zoned for agricultural use follow different rules. At a $1 million ceiling, the widow’s estimated equity would already be $132,750 over the line.
Why an Appraisal Matters Near the Equity Limit
A $2,750 gap is small enough that solid evidence could close it. A metro index tracks averages. Her house has its own history. It may have a 30-year-old roof, the original kitchen, a cracked foundation or a busy main street out front.
When families think the state’s number runs high, they build a file. It usually holds a licensed appraisal. It also includes recent sales of comparable homes nearby, and inspection reports or contractor bids that put a price on the defects. An appraiser who walks through the house and photographs the water stains will usually beat a computer estimate that never left the curb.
Timing matters. A family that checks equity and orders an appraisal before a long-term-care application has more time to document the home’s actual condition and value. Starting during a hospital discharge leaves far less room to resolve a valuation dispute while nursing-home bills keep arriving. For a widow near Colorado’s line, a current appraisal and solid comparable sales can make the difference between an estimate and evidence.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.