Warrior Met Coal Closes in on IPO
It is surprising to see a coal company come forward and file to be publicly traded, considering the industry’s recent history.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
[cnxvideo id=”655354″ placement=”ros”]We’ve noted in the past that the coal industry has been absolutely beat down in recent memory, with more companies consolidating or getting out of the business than entering. So it is surprising to see a coal company come forward and file to be publicly traded, considering the industry’s history.
Warrior Met Coal has filed an amended S-1 form with the U.S. Securities and Exchange Commission (SEC) regarding its initial public offering (IPO). The company expects to price its 16.67 million shares in the range of $17 to $19, with an overallotment option for an additional 2.5 million shares. At the maximum price the entire offering is valued up to $364.17 million. The company intends to list its shares on the New York Stock Exchange under the symbol HCC. Keep in mind that this company was formerly known as Walter Energy.
The underwriters for the offering are Credit Suisse, Citigroup, Morgan Stanley, BMO Capital Markets, RBC Capital Markets, Apollo Global Securities, Clarksons Platou Securities and KKR.
[nativounit]
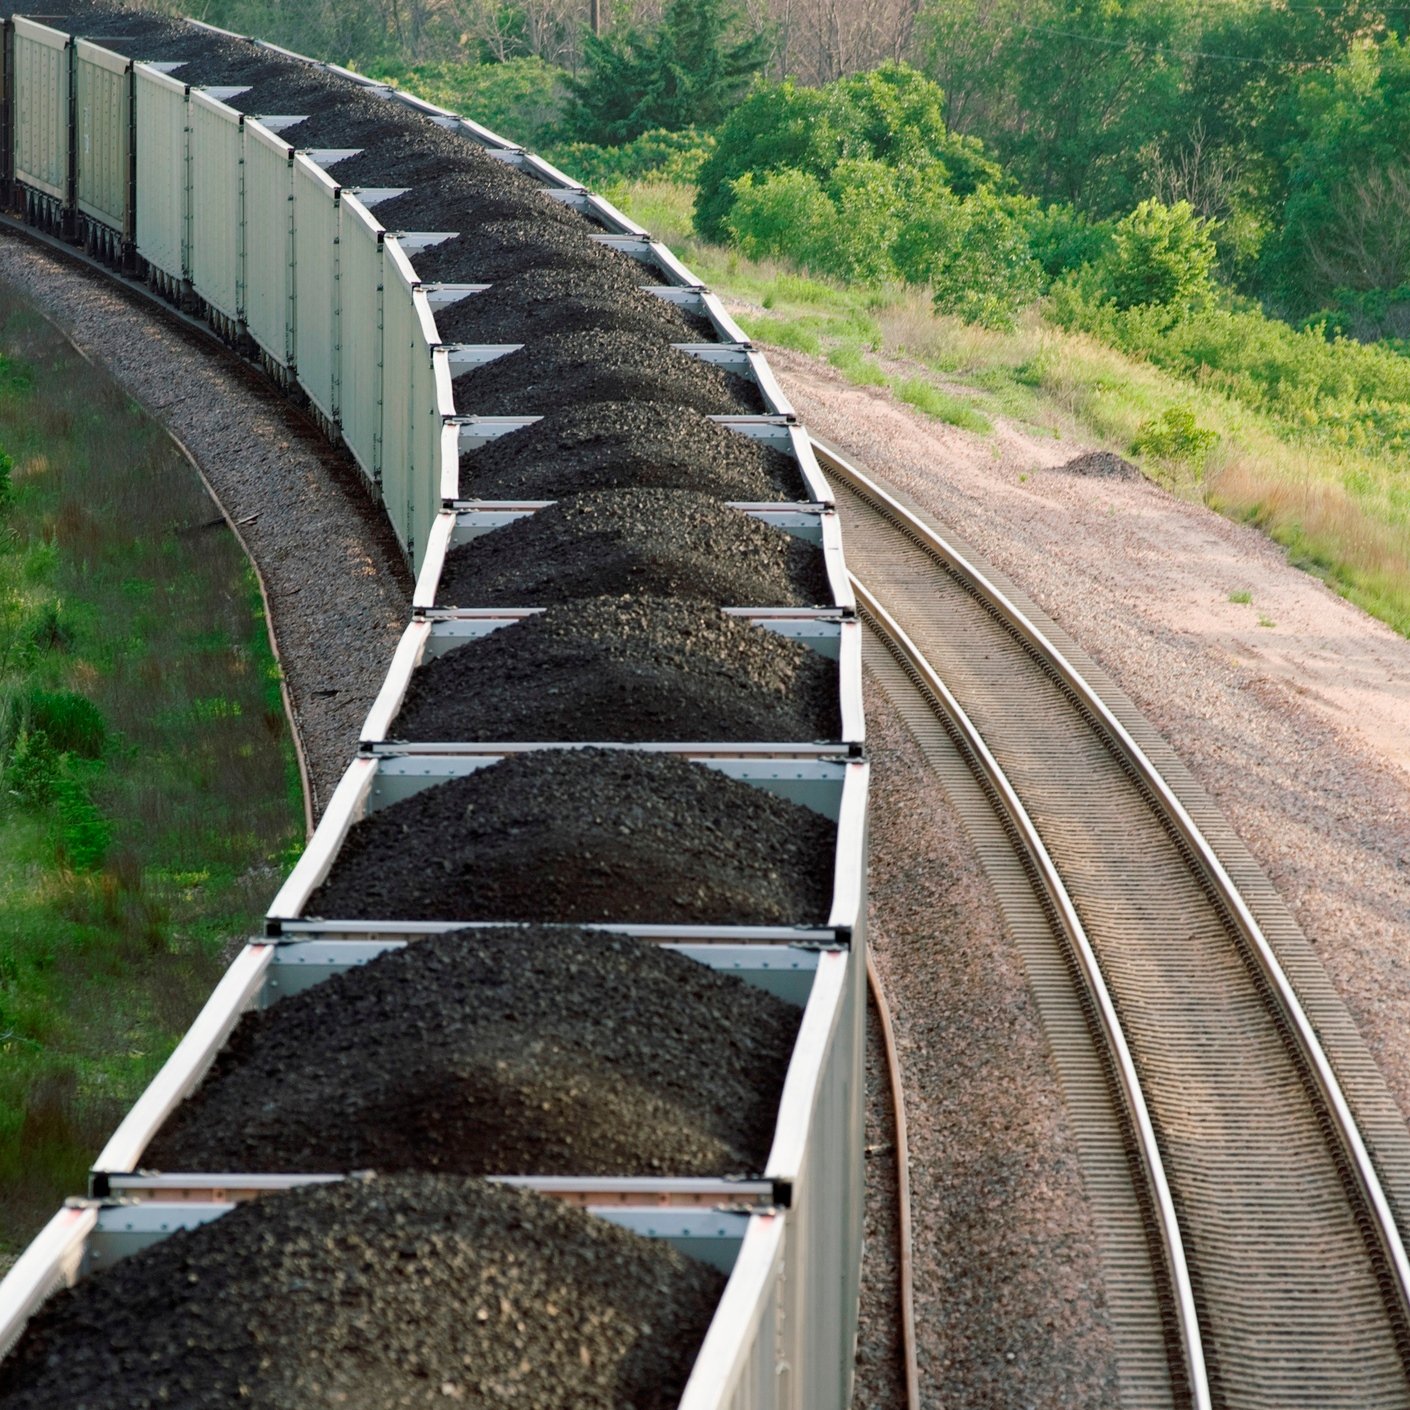
This is a large-scale, low-cost U.S.-based producer and exporter of premium metallurgical coal, operating two highly productive underground mines in Alabama, Mine No. 4 and Mine No. 7, that have an estimated annual production capacity of 7.3 million metric tons of coal.
According to Wood Mackenzie, in 2017, Warrior is expected to be the largest seaborne met coal supplier in the Atlantic Basin, and a top 10 supplier to the global seaborne met coal market. At the end of December 2016, based on a reserve report prepared by Marshall Miller, its two operating mines had approximately 107.8 million metric tons of recoverable reserves and, based on a reserve report prepared by Norwest, its undeveloped Blue Creek Energy Mine contained 103.0 million metric tons of recoverable reserves. The premium hard coking coal it produces at Mine No. 4 and Mine No. 7 is of a similar quality to coal referred to as the “benchmark HCC” produced in Australia, which is used to set quarterly pricing for the met coal industry.
For the year ended 2015, the company generated sales of $514.3 million, but incurred costs of sales of $601.5 million.
The company will not receive any proceeds from the sale of the common stock in this offering. Instead, all the net proceeds will be received by the selling stockholders.
For some background on the company: Warrior Met Coal was formed on September 3, 2015, by certain lenders under Walter Energy’s 2011 Credit Agreement, dated as of April 1, 2011, and the noteholders under Walter Energy’s 9.50% senior secured notes due 2019 in connection with the acquisition by the company of certain core assets of Walter Energy and certain of its wholly owned subsidiaries related to its Alabama mining operations.
[wallst_email_signup]
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.