Stock Price Prediction: Arm Holdings Has Limited Upside Despite 177% Rally
I’ll cut to the chase. Arm Holdings (NASDAQ:ARM | ARM Price Prediction) has more than doubled year-to-date, and our proprietary model now sees only a sliver of upside left in the near term. Our 24/7 Wall St. price target for…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
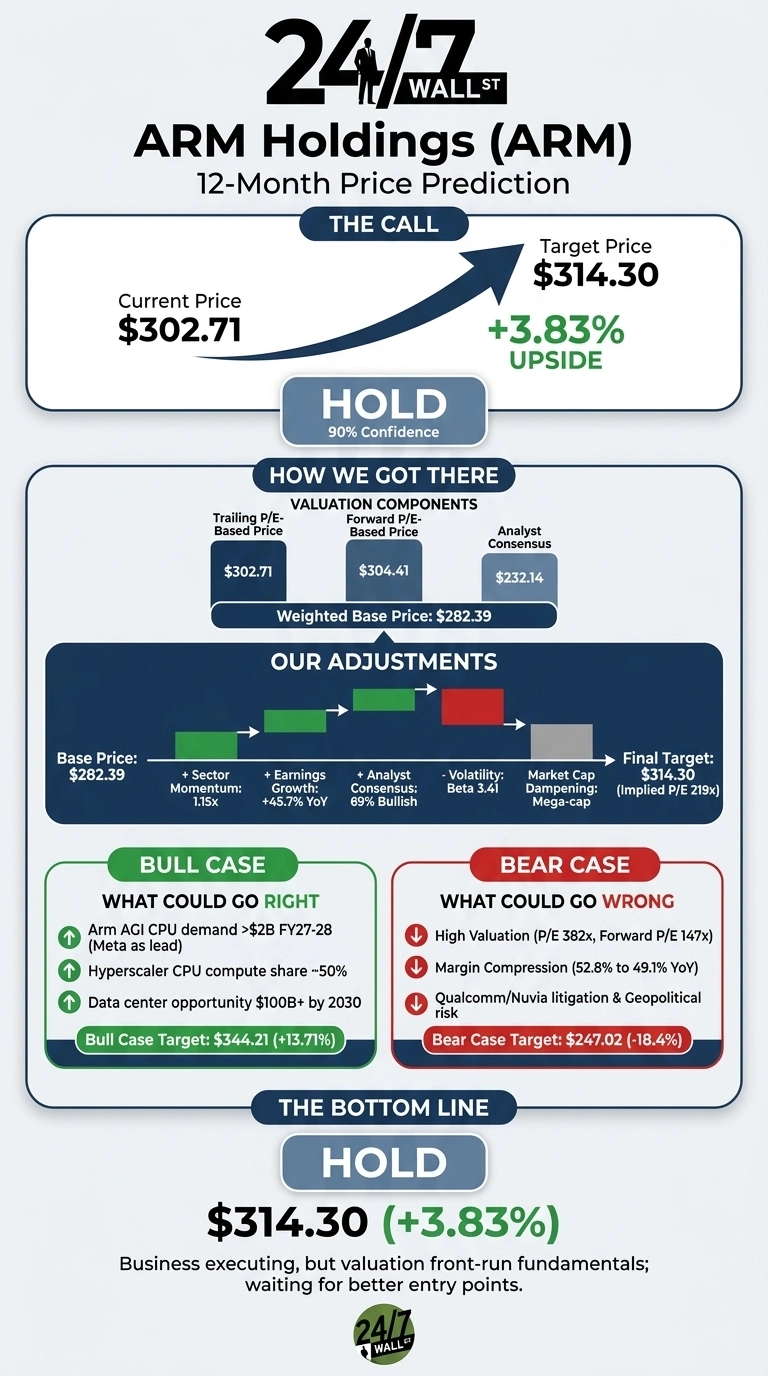
I’ll cut to the chase. Arm Holdings (NASDAQ:ARM | ARM Price Prediction) has more than doubled year-to-date, and our proprietary model now sees only a sliver of upside left in the near term. Our 24/7 Wall St. price target for Arm is $314.30 over the next 12 months, implying roughly 3.83% upside from the recent close of $302.71. The recommendation is hold, with a high confidence reading of 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $302.71 |
| 24/7 Wall St. Price Target | $314.30 |
| Upside | 3.83% |
| Recommendation | HOLD |
| Confidence Level | 90% |
An AI Compute Story That Has Already Repriced
Arm has been one of the cleanest AI infrastructure trades of 2026. Shares are up 176.93% year to date, 40.22% in the past month, and 17.91% in the past week alone, even after a 5.76% pullback on May 27. The stock sits 29% below a 52-week high of $325 and well above the $100.02 52-week low.
The fundamentals justify the move. Q4 FY2026 revenue hit $1.49 billion, growing 20.1% YoY and beating consensus, while non-GAAP EPS of $0.60 beat the $0.57 estimate. Data center royalty revenue more than doubled YoY. CEO Rene Haas framed the year as a turning point, citing “a third consecutive year of more than 20% revenue growth” and noting Arm AGI CPU demand “has exceeded expectations.”

The Case for $344 and Higher
Bulls have a clean narrative. Arm AGI CPU, the company’s first data center chip, already has more than $2 billion in committed customer demand across FY2027 and FY2028, with Meta as lead partner.
Arm holds roughly 50% CPU compute share among top hyperscalers, with NVIDIA Vera, Google Axion, and Microsoft Cobalt all built on Arm. Management is targeting a $100 billion data center CPU opportunity by 2030. ACV grew 22% YoY to $1.66 billion, and full-year FCF jumped 395.51%. Our bull case scenario lands at $344.21, or 13.71% upside.

What Could Go Wrong
The bear case starts with valuation. Arm trades at a trailing P/E of 382 and a forward P/E of 147, leaving little margin for error. The consensus analyst target of $232.14 sits well below the current quote. Non-GAAP operating margin compressed from 52.8% to 49.1%, RPO fell 7% YoY, and Q4 FCF declined 17.39%.

Bulls would counter that the margin pressure reflects a 43% ramp in R&D to $1.911 billion, funding the AGI CPU roadmap. Add the Qualcomm/Nuvia trial expected in Q4 2026, US export controls, a 25% tariff on semi imports, and SoftBank’s controlling stake, and the downside scenario lands at $247.02, or -18.4%.
Arm Price Prediction 2026-2030
My 24/7 Wall St. price target for Arm is $314.30 with hold at 90% confidence. The business is executing, but the stock has front-run the fundamentals after a 177% YTD rally. A pullback toward the $250 to $270 zone would mark a more attractive entry, where royalty growth and AGI CPU bookings would carry the valuation.
Caution is warranted if Arm trades through $325 without a fresh customer announcement or if the Qualcomm trial in Q4 introduces overhang. For now, holders should keep an eye on the stock and let the bookings do the work.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $314.30 |
| 2030 | $376.50 |
These projections assume Arm continues converting AGI CPU demand into royalty revenue and hyperscaler share holds near 50%. Material upside or downside could come from the Qualcomm verdict, China export policy, or a step-change in agentic AI capex.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.