Price Prediction: Up 144% YTD, Where Will AMD Be In 2027?
AMD has nearly tripled in a year on the back of exploding Data Center revenue and Lisa Su's boldest guidance yet, but the stock sits 12% off its highs with analyst targets still lagging the price. Whether $800 is a…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
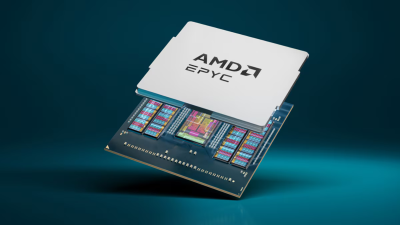
AMD has become the AI trade of 2026. Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) is up 155.29% year to date as Data Center revenue explodes and Lisa Su locks in multi-gigawatt deals with OpenAI and Meta.
Q1 Data Center revenue hit $5.775 billion, up 57% year over year, and management now sees a server CPU TAM of over $120 billion by 2030. Can AMD hit $800 by the end of 2027?

Why AMD Shares Have Paused Near the Highs
Even after a monster run, momentum has cooled. Shares are up 5.58% in the past week and 14.98% over the past month, but sit roughly 12% below the 52-week high of $584.73. Part of that is digestion. Part of it is beta of 2.469, which means AMD trades like an amplified NASDAQ.
The trailing P/E of 206 gives fundamental buyers pause, even though forward earnings power looks very different. Add ongoing U.S. export restrictions on MI308 shipments to China, and growth investors are asking whether the easy money has already been made.
Wall Street Is Bullish, But Consensus Lags the Stock
The average analyst target sits at $512.27, below the current price. Coverage skews positive with 5 Strong Buy, 37 Buy, 9 Hold and zero Sell ratings, or 82% bullish, but price targets have not caught up to the June rally.
Our base case model lands at $581.08 for July 2027 with 90% confidence, and the bull case rises to $632.24. Both feel too conservative given quarterly earnings growth of 91.2% year over year. Analysts are anchoring to old estimates, setting up targets to march higher through the year. Stifel analyst Ruben Roy raised the firm’s price target on AMD to $635 from $450 and keeps a Buy rating on the shares.

The Path to $800 Per Share
Reaching $800 from today’s price of $546.72 would require a gain of 46.3%. With forward EPS of $6.87, a price of $800 implies a forward P/E of 116x. Our base case of $581.08 already implies 119x means the $800 target requires no additional multiple expansion. It is a pure EPS growth story.
Lisa Su told investors AMD sees a “clear path to exceed our long-term financial targets, including delivering more than $20 in EPS over the strategic time frame”.
Catalysts in the pipeline include Meta’s 6 gigawatt Instinct deployment, the Helios rack ramp in Q3 and Q4 2026, and Su’s guidance that AMD will deliver “tens of billions of dollars in annual Data Center AI revenue in 2027”. The single biggest risk is an expansion of China export controls that clips MI-series unit volumes.
Where AMD Trades Today Vs Its Earnings Power
At $546.72, AMD trades at roughly 80x forward EPS of $6.87. That is rich, but the growth backdrop is unusual. Shares sit within striking distance of the 52-week high of $584.73 and nearly 4x off the 52-week low of $141.60.
Zooming out further, AMD is up 10,812.57% over the past ten years. If the AI capex cycle plays out as Su described, today’s multiple compresses fast as EPS scales into the double digits.
Is $800 Realistic?
Getting to $800 by the end of 2027 requires a 46.3% gain from here. It is a stretch, but a defensible one.
Three things need to go right. MI450 and Helios have to ramp on schedule through late 2026. Server CPU share needs to keep marching toward the 50%+ market share target. Gross margin has to hold at the 55% to 58% range Lisa Su outlined.
What derails it is a broader tightening of U.S. chip export rules that cuts off AI accelerator demand. We’ve outlined the blueprint for how Advanced Micro Devices could reach $800 in 2027.

Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.