One Reason to Be Bullish on SanDisk Stock
SanDisk has already delivered one of the most explosive stock runs in recent memory, yet a single structural shift in how it sells storage could mean the rally is nowhere near finished.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Our SanDisk (NASDAQ:SNDK | SNDK Price Prediction) price prediction has one message: the AI storage story that turned this stock into a 3,120% one-year gainer still has room to run.
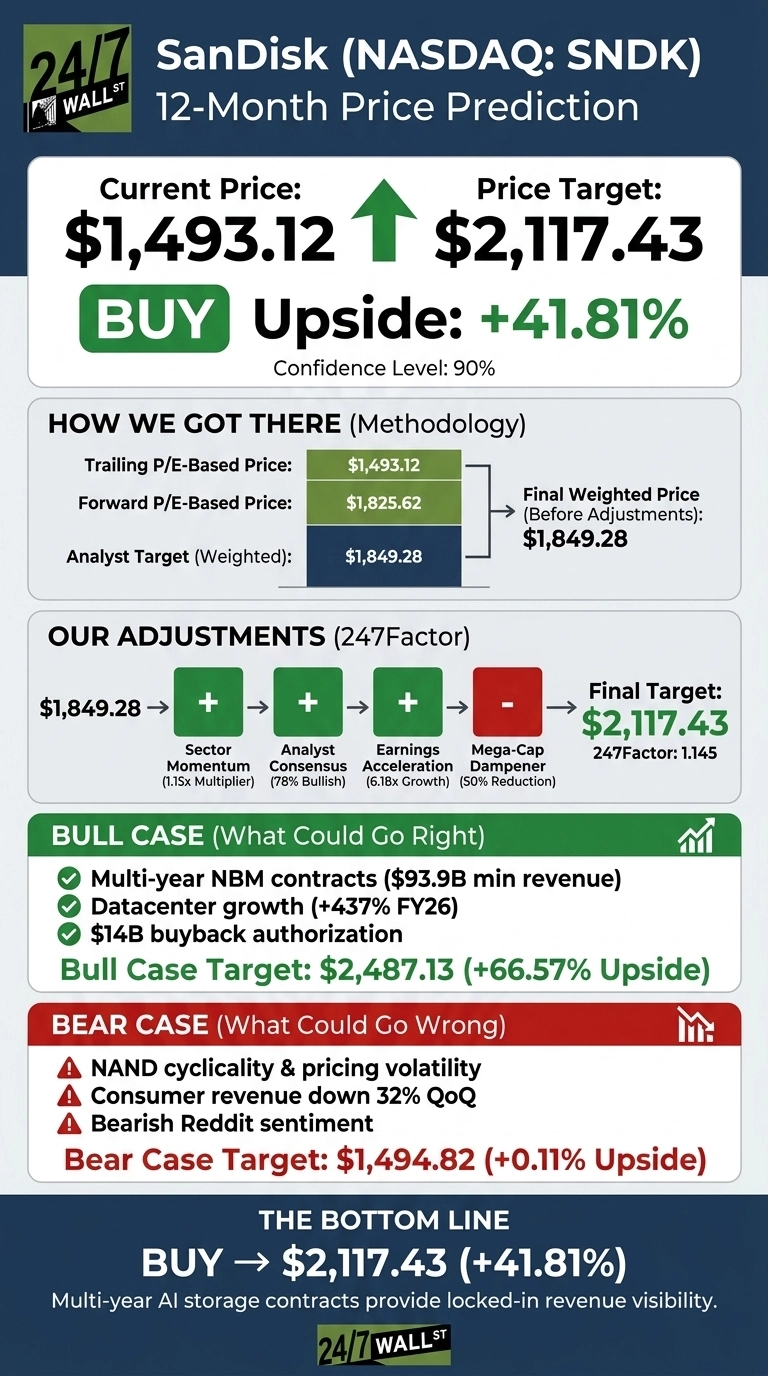
The 24/7 Wall St. price target is $2,117.43 over the next 12 months, implying 41.81% upside from $1,493.12. Our recommendation is buy with 90% confidence. The reason to be bullish: multi-year contracts have turned a cyclical NAND supplier into a company with locked-in revenue visibility.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $1,493.12 |
| 24/7 Wall St. Price Target | $2,117.43 |
| Upside | 41.81% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Post-Earnings Reset With the Growth Story Intact
SanDisk gave back 16.44% over the past week and 6.45% on the most recent trading day, cooling from a Reddit post flagging “rapidly increasing volatility among memory stocks” as a possible bubble signal. Year to date, shares are up 529%.
Fiscal Q4 2026, reported August 5, delivered non-GAAP EPS of $39.25 against $33.28 consensus (the fifth straight beat) on revenue of $8.96 billion (up 371.59% year over year). GAAP gross margin hit 84.6%. Q1 FY2027 guidance calls for revenue of $10.30 billion to $10.80 billion and non-GAAP EPS of $44 to $46.
Why Bulls See a Breakout to $2,487
The bull case rests on signed contracts. Management said New Business Model deals now cover eight datacenter and edge customers with a weighted-average duration of over four years and minimum expected revenue of $93.9 billion. NBMs will cover more than 50% of FY2027 bits and roughly two-thirds of FY2028 bits. Datacenter revenue grew 437% in FY2026.
Management projects the NAND market approaches $500 billion in calendar 2027. Analysts have chased shares to a $2,126.17 consensus target, and our bull-case scenario points to $2,487.13, roughly 66.57% above current levels. The $14 billion additional buyback authorization adds fuel.

What Could Go Wrong
NAND remains cyclical. The non-NBM portion floats with market pricing, and Q4 revenue growth was two-thirds pricing driven, meaning spot NAND softening compresses margins fast. Consumer revenue fell to $556 million, down 32% quarter over quarter, and Reddit sentiment turned bearish at a weekly score of 23.5. Kioxia dependency and customer concentration also matter.
Bulls counter that lower sequential margins reflect deliberate product mix and prudent guidance while fundamentals remain intact, and NBMs smooth exactly this volatility. Our bear-case scenario lands at $1,494.82, essentially flat.

How SanDisk Compares to Micron and Western Digital
Micron (NASDAQ:MU) is the direct memory competitor. Its fiscal Q3 2026 revenue was $41.46 billion at 84.6% GAAP gross margin, matching SanDisk’s profile but on far larger scale ($1.03 trillion market cap). Micron’s Strategic Customer Agreements validate the multi-year-contract playbook, making our SanDisk target well-grounded.
Western Digital (NASDAQ:WDC) is SanDisk’s former parent and the HDD counterpart to the same AI storage buildout. WDC posted Q4 FY26 revenue of $3.75 billion (up 43.84%) at 54.4% non-GAAP gross margin. SanDisk’s 84.6% gross margin and 371.59% revenue growth exceed WDC, justifying our target premium.
What Tips the Scale for Bulls
The 24/7 Wall St. price target of $2,117.43 is a buy at 90% confidence. The $93.9 billion NBM revenue floor tips the scale.
Investors will want to watch whether the next earnings report shows NBM bit coverage crossing 50% as guided, and whether spot NAND pricing holds before FY2027 contracts fully ramp.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $2,117 |
| 2027 | $2,653 |
| 2028 | $3,225 |
| 2029 | $3,568 |
| 2030 | $3,945 |
These projections assume SanDisk executes on its NBM strategy and BiCS8/BiCS10 roadmap. A cyclical NAND correction or Kioxia disruption could push results toward our bear path near $1,708 by 2031.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.