SanDisk Could Have a Much Bigger Opportunity Than Investors Expect
SanDisk has already surged hundreds of percent this year on record earnings and massive long-term contracts, yet one critical risk lurking inside its revenue breakdown raises questions about whether the rally can survive what comes next in the NAND cycle.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
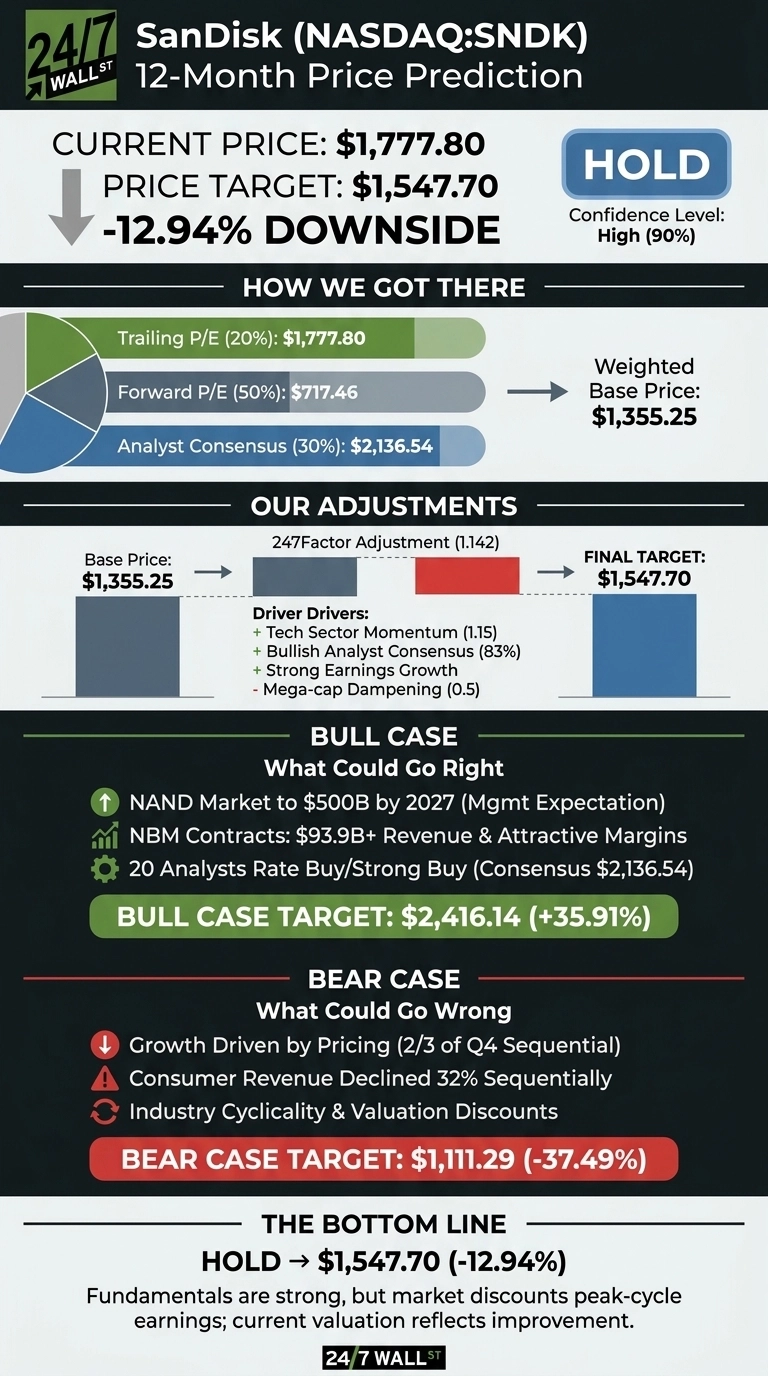
Our 24/7 Wall St. Price Target for SanDisk (NASDAQ:SNDK | SNDK Price Prediction) is $1,547.70. The stock currently trades at $1,777.80, so the target means -12.94% downside. Our model rates the shares a hold, and its confidence in that call is high.
| Metric | Value |
|---|---|
| Current Price | $1,777.80 |
| Price Target from 24/7 Wall St. | $1,547.70 |
| Upside/Downside | -12.94% |
| Recommendation | HOLD |
| Confidence Level | 90% |

SanDisk now makes like a premium semiconductor business. After a 1,785.46% gain over the past year, though, the share price already reflects much of that improvement.
Why Our Model Could Be Too Cautious
Our target is below today’s price. SanDisk’s New Business Model (NBM) contracts carry at least $93.9 billion in expected revenue even at floor pricing.
Management expects the NAND market to “approach $500 billion in revenue in calendar year 2027”. The full bull case follows below.
A 648% Year-to-Date Surge Backed by Record Earnings
The shares slipped 0.78% over the past week, up 18.57% over the past month and 648.93% year to date. The stock trades 24.49% below its 52-week high of $2,354.39 and about 17x its 52-week low of $103.35.
In the fiscal Q4 earnings report on August 5, revenue rose 371.6% to $8.965 billion. Non-GAAP EPS came in at $39.25, beating the $33.28 consensus. That was the company’s fifth consecutive beat. For fiscal Q1, management guided to revenue of $10.30 billion to $10.80 billion and EPS of $44 to $46. The board also added a $14 billion buyback.
Why Bulls See $2,416 Within Reach
Management says “demand from our customers is growing faster than our supply,” and expects bits to stay on allocation beyond 2027. Remaining performance obligations would reach $91.1 billion including two post-quarter NBMs, backed by $16.5 billion in financial guarantees.
Of analysts covering the stock, 20 rate it Buy or Strong Buy, with a consensus target of $2,136.54. Bull-case upside reaches $2,416.14.


What Could Drag SanDisk Toward $1,111
About two thirds of fiscal Q4’s sequential growth came from higher prices. Gross margin was at 84.6%, up from 26.4% a year earlier. Consumer revenue fell 32% from the prior quarter. The bear case is $1,111.29. Management targets NBM margins around 80% and expects “attractive margins even at floor pricing.”
SanDisk Versus Micron, Western Digital and Seagate
| Company | Latest Quarter Revenue Growth | Latest EPS Beat |
|---|---|---|
| SanDisk | 371.6% | 17.94% |
| Micron | 345.72% | 23.79% |
| Western Digital | 43.84% | 8.11% |
| Seagate | 48.49% | 12.11% |
Micron (NASDAQ:MU) is the closest NAND and DRAM comparable. Its 84.6% GAAP gross margin matches SanDisk’s, supporting memory pricing is raising the sector.
Western Digital (NASDAQ:WDC) sells only hard disk drives with 54.4% non-GAAP gross margin, showing how far below flash storage traditional storage runs.
Seagate (NASDAQ:STX) increased fiscal 2026 revenue 34.06%. Against this group, the target looks reasonable. SanDisk’s growth matches Micron’s but rests on NAND pricing, which moves in cycles.
SanDisk Price Prediction 2026-2030
The 24/7 Wall St. price target is $1,547.70 with a hold rating and 90% confidence. The market discounts peak-cycle earnings heavily. A more positive view would require NBM floors to hold through calendar 2027 and edge demand to return to growth.
Caution remains warranted if price increases stall before new contracts take a larger share of bits. The fundamentals look excellent, and valuation already reflects them fully.
Base-case figures here extend our model forward and assume current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $1,547.70 |
| 2027 | $1,554.30 |
| 2028 | $1,463.05 |
| 2029 | $1,437.01 |
| 2030 | $1,492.21 |
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.