Dave & Buster’s Retreats 12% on Sales Miss; Six Flags Slips 2%, Lucky Strike Entertainment Falls 1%
Dave and Buster's shares cratered after a rough quarter, but management is pointing to a trend that could change the story entirely for patient investors watching the entertainment sector stumble.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
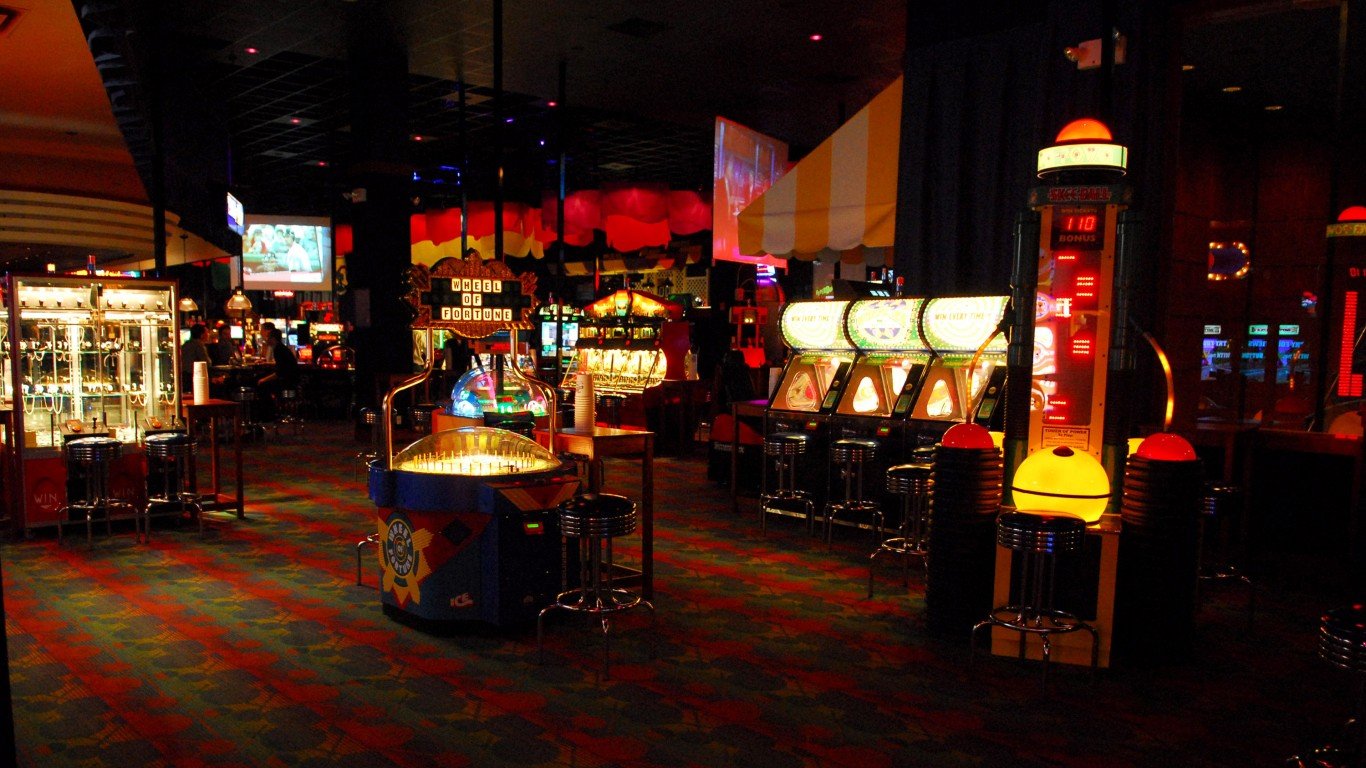
Dave & Buster’s Entertainment (NASDAQ:PLAY) stock is falling 12% to $7.41 in Tuesday morning trading after the entertainment and dining operator reported weaker-than-expected second-quarter results. Dave & Buster’s generated $544.1 million of revenue, down 2.4% from a year earlier and below the roughly $556.8 million analysts had expected, while the company posted an adjusted loss of $0.27 per share.
The weakness isn’t isolated to Dave & Buster’s stock, although the decline is more pronounced than in some peers. Six Flags Entertainment (NYSE:FUN) stock is down 2% to $12.92, Lucky Strike Entertainment (NYSE:LUCK) stock is falling 1% to $5.56, the Invesco Leisure and Entertainment ETF (NYSE ARCA:PEJ) is down 1% to $62.95, and the SPDR S&P 500 ETF Trust (NYSE ARCA:SPY) stock is down 0.2% to $759.36.
Dave & Buster’s Sales Miss Raises Concerns
Dave & Buster’s second-quarter same-store sales fell 2.9%, while entertainment-related sales declined 9% and food and beverage revenue provided an offsetting benefit. Dave & Buster’s also swung to a $12.5 million net loss from net income of $11.4 million in the year-earlier quarter, adding to the pressure on PLAY stock.
Dave & Buster’s does have a potential recovery argument, however, because management indicated that sales trends improved as the quarter progressed. Same-store sales declined 5% in June and 1.6% in July, while management reported additional improvement during the first five weeks of the third quarter.
A Turnaround Could Still Take Time
Dave & Buster’s has acknowledged the need to improve its entertainment offerings and reconnect with customers, with the company emphasizing new products, stronger marketing and better value. Dave & Buster’s remodeled locations have also performed better than the systemwide average, which could provide a useful blueprint if those improvements can be replicated more broadly.
Yet, Dave & Buster’s stock faces a tougher case while revenue remains below the prior year’s level and profitability has deteriorated. Investors may want to watch for whether the sequential improvement continues and whether the company’s efforts to refresh its entertainment business can translate into sustained comparable-sales growth.
Peers Also Face A Challenging Backdrop
Six Flags stock is falling 2% to $12.92, suggesting that pressure on discretionary entertainment businesses extends beyond Dave & Buster’s. Six Flags has faced its own operational and financial challenges following the 2024 combination of Cedar Fair and Six Flags, including weak attendance and significant debt.
Lucky Strike stock is slipping 1% to $5.56, while the Invesco Leisure and Entertainment ETF is down 1%. The relatively modest declines in Lucky Strike stock and the ETF compared with Dave & Buster’s stock could suggest that investors are distinguishing between broader leisure-sector pressure and Dave & Buster’s specific earnings problems.
Investors May Want To Stay Selective
The bullish case for Dave & Buster’s rests on the possibility that recent investments in entertainment, marketing and remodeled locations can restore traffic and improve sales trends. Dave & Buster’s could also benefit if consumer spending on experiences remains resilient, giving the company room to rebuild profitability from a depressed base.
However, the latest results show that the turnaround still carries meaningful execution risk, particularly after the revenue miss and adjusted loss. Investors who choose to own Dave & Buster’s stock should consider keeping their share-position sizes moderate, while investors on the sidelines may want to watch for clearer evidence of sustained sales improvement before taking on additional exposure.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk.His work has appeared in The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, TalkMarkets, Finmasters, 24/7 Wall St., and others.With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.