Prediction: Meta Stock Will Trade at $800 on This Date
Meta's ad engine is firing on all cylinders and analysts are almost unanimously bullish, yet one earnings gate stands between today's price and a specific target date that changes everything for long-term investors.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
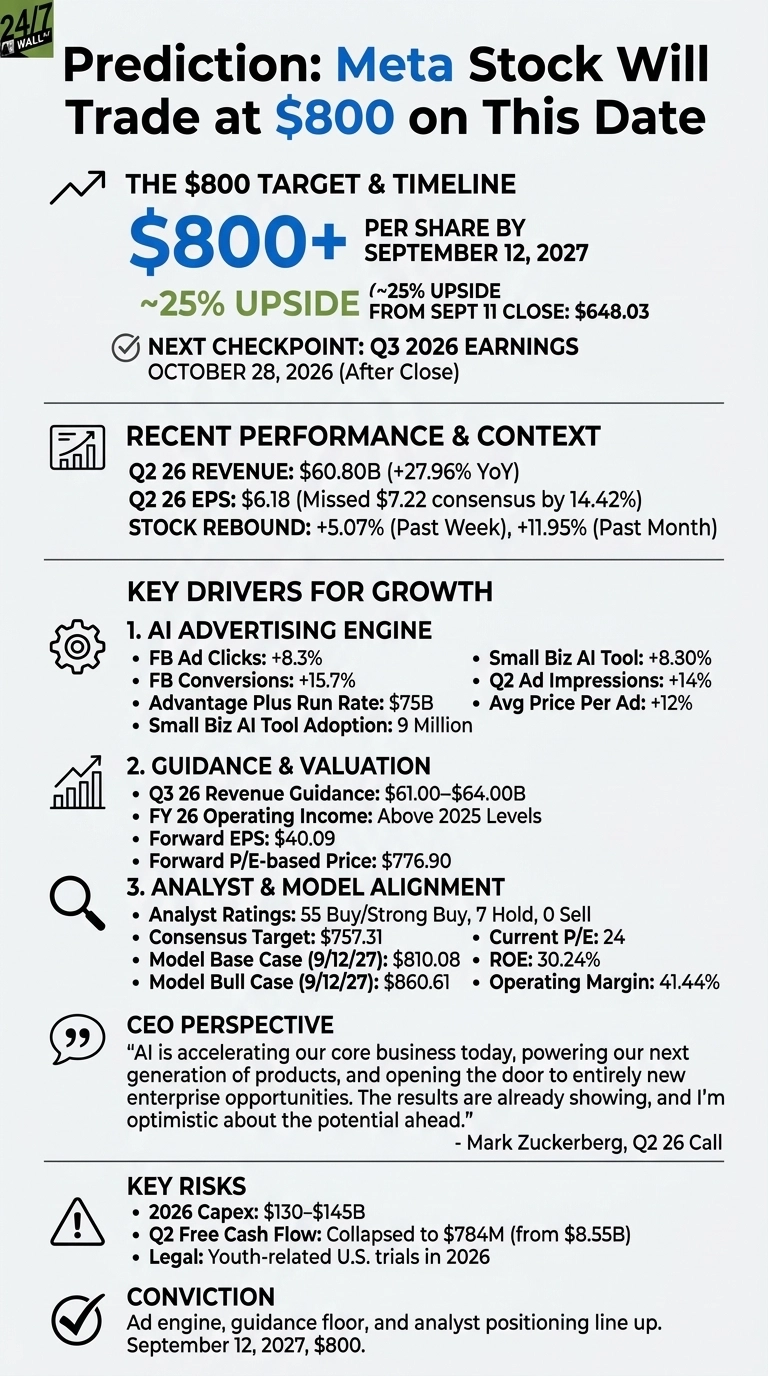
Meta Platforms (NASDAQ:META | META Price Prediction) will trade at or above $800 per share by September 12, 2027, a roughly 25% move from the September 11 close of $648.03. The first checkpoint arrives sooner: the October 28, 2026 Q3 earnings report, released after the close. That earnings report is the gate. Clear it, and the runway to $800 opens.
Meta Platforms enters the fall setup off a bruising July: Q2 2026 revenue landed at $60.80 billion, up 27.96% year over year, but diluted EPS of $6.18 missed the $7.22 consensus by 14.42%, snapping a six-quarter beat streak.

The stock has since rebuilt: up 5.07% in the past week and 11.95% over the past month. Three reasons the $800 target resolves in favor.
AI Advertising Is Already Paying
The Q2 call quantified the flywheel. Ranking and sequence-learning upgrades drove an 8.3% increase in ad clicks on Facebook and a 15.7% uplift in conversions.
Advantage Plus end-to-end tools reached a $75 billion annual revenue run rate, and nine million small businesses are now using at least one Meta AI ad creative tool. Q2 ad impressions rose 14% while average price per ad rose 12%. Both curves accelerating simultaneously is the setup shorts do not want to see heading into Q3.

Guidance Frames a Beatable Bar
Management guided Q3 revenue to $61 to $64 billion and reiterated full-year 2026 operating income above 2025 levels. The Q2 expense shock was concentrated: $2.40 billion in legal charges and $1.18 billion in severance from the May headcount cut.
Strip those out and operating income rose 9% year over year. The Q3 comparison normalizes that base. With forward EPS of $40.09 feeding the model, the forward P/E-based price is $776.90, before any multiple expansion on cleaner comps.
Analyst and Model Alignment
The sell side is stacked to one side: 55 buy or strong buy ratings versus 7 holds and zero sells, with a consensus target of $757.31. The base-case one-year projection lands at $810.08 on September 12, 2027, with the bull case at $860.61.
At a current P/E of 24, ROE of 30.24%, and operating margin of 41.44%, Meta is priced well below a company poised to re-rate. That is the opportunity.

What Zuckerberg Said
On the Q2 call, CEO Mark Zuckerberg framed the thesis directly: “AI is accelerating our core business today, powering our next generation of products, and opening the door to entirely new enterprise opportunities.
The results are already showing, and I’m optimistic about the potential ahead.” Meta Connect on September 23, 2026 and the Q3 report on October 28 are the near-term proof points.

What Kills the Call
The risk is real: 2026 capex of $130 to $145 billion, Q2 free cash flow collapsing to $784 million from $8.55 billion, and youth-related U.S. trials in 2026.
That capex flows straight to the power, cooling, and networking suppliers behind the data-center buildout, seven of which we profiled in a free report: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers).
Another EPS miss with no offsetting revenue upside pushes $800 into 2028. Conviction stands: the ad engine, the guidance floor, and analyst positioning line up. September 12, 2027, $800.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.