Coinbase Has a Bitcoin Problem, and a Potentially Bigger Opportunity
Coinbase just delivered one of its ugliest quarterly reports in years, yet a quiet transformation happening beneath the surface could make the spot trading slump largely irrelevant to its future.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Coinbase (NASDAQ:COIN | COIN Price Prediction) has become a stock of two stories. One is the near-term problem: spot crypto volumes have cratered, Bitcoin (CRYPTO:BTC) sits well below its cycle peak, and the Q2 2026 earnings report was ugly.
The other is the bigger opportunity: stablecoins, derivatives, prediction markets, and Base are building a business that no longer needs Bitcoin to work. Our 24/7 Wall St. price target reflects both.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $172.11 |
| 24/7 Wall St. Price Target | $212.94 |
| Upside | 23.73% |
| Recommendation | BUY |
| Confidence Level | 50% |
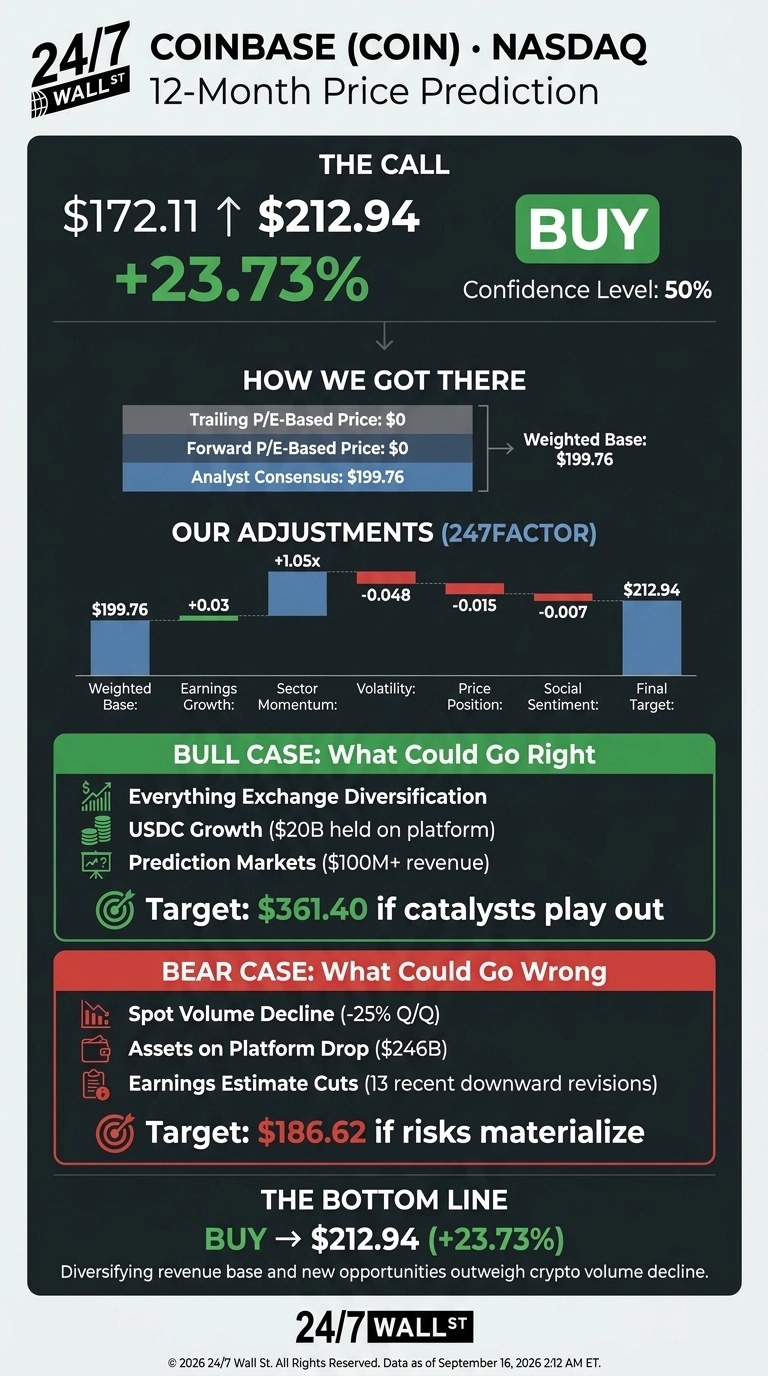
Our 24/7 Wall St. price target for Coinbase is $212.94 over the next 12 months, with a moderate confidence level. The rating is a buy, driven by a diversifying revenue base that our model believes the market is underpricing after a brutal de-rating.
A Bitcoin Hangover Meets a Base Rally
Coinbase has been through the wringer. Shares are down 47.37% over the past year and 23.89% year to date, though the last month brought a 15.92% bounce. The 52-week range runs from $139.11 to $402.16.
Q2 2026 revenue of $1.22 billion fell 18.5% year over year and missed consensus by 5.36%, with GAAP EPS of -$1.36. The driver was blunt: total crypto spot trading volume fell 25% quarter over quarter as volatility hit multi-year lows. Morningstar recently raised its fair value estimate on higher crypto prices, while a stalled Senate crypto bill dented sentiment this week.

Why Bulls See $360-Plus
The bull case rests on the “Everything Exchange.” On the Q2 call, CEO Brian Armstrong said, “We’re diversifying revenue both on the trading fee side and on subscription and services with non-trading fees.”
Prediction markets already exceed $100 million in annualized revenue, average USDC held on platform hit an all-time high of $20 billion, and Base has processed roughly $32 trillion in trailing 12-month stablecoin transfer volume.
Management pegs the stablecoin market at $300 billion today, headed toward $3 trillion by 2030. Our bull scenario points to $361.40, a 110% return if Bitcoin re-accelerates and Deribit derivatives compound.

Risks Worth Watching
The bear case is straightforward. Consumer transaction revenue fell 20% YoY in Q2 and institutional dropped 26%. Assets on Platform dropped to $246 billion from $294 billion. The FY2026 EPS estimate has collapsed from $0.8953 ninety days ago to -$1.9697 today, with 13 downward revisions in the past 30 days.
Counterpoint: Q2 adjusted EBITDA was still positive at $207.8 million (14 consecutive quarters), and management is taking $600 million of costs out versus the 2025 exit run rate. Our bear scenario lands at $186.62, still above today’s price.

How Coinbase Compares to Robinhood and CME
Robinhood (NASDAQ:HOOD) is the sharpest comp on retail crypto and prediction markets. Q2 2026 revenue climbed 32% YoY to $1.31 billion, with event contracts revenue up more than tenfold to $156 million.
HOOD’s $87 billion market cap exceeds Coinbase’s $38 billion, despite smaller crypto exposure. That gap says the market is paying up for diversified retail flow, which is exactly where Coinbase is heading.
CME Group (NASDAQ:CME) is the regulated-derivatives yardstick. Q2 2026 revenue was $1.71 billion with adjusted EPS of $2.99, and CME is rolling out 24/7 crypto trading and prediction markets.
At a $99 billion market cap, CME trades at a premium multiple reflecting stable fee economics. That contrast makes our $212.94 target look reasonable.
Diversification Is the Real Story
The 24/7 Wall St. price target of $212.94 implies a 23.73% one-year return, a buy at 50% confidence.
The tipping factor is subscription and services, which reached 48% of net revenue in Q2. The bull thesis strengthens if USDC balances and prediction-market revenue continue doubling. The setup weakens if Bitcoin breaks below $70,000 and drags spot volumes lower.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $181 |
| 2027 | $211 |
| 2028 | $240 |
| 2029 | $263 |
| 2030 | $288 |
These projections assume Coinbase continues executing the Everything Exchange strategy. Meaningful upside or downside could come from a regulated stablecoin boom, agentic-finance adoption on Base, or a prolonged spot-trading winter.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.