AMD Is About to Become a Trillion-Dollar Stock as It Hikes Chip Prices 10%
AMD is knocking on a door only 14 other companies have ever opened, and a bold 10% price hike on its hottest chips is what just pushed it to the threshold.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Anchor Number: $992.4 Billion
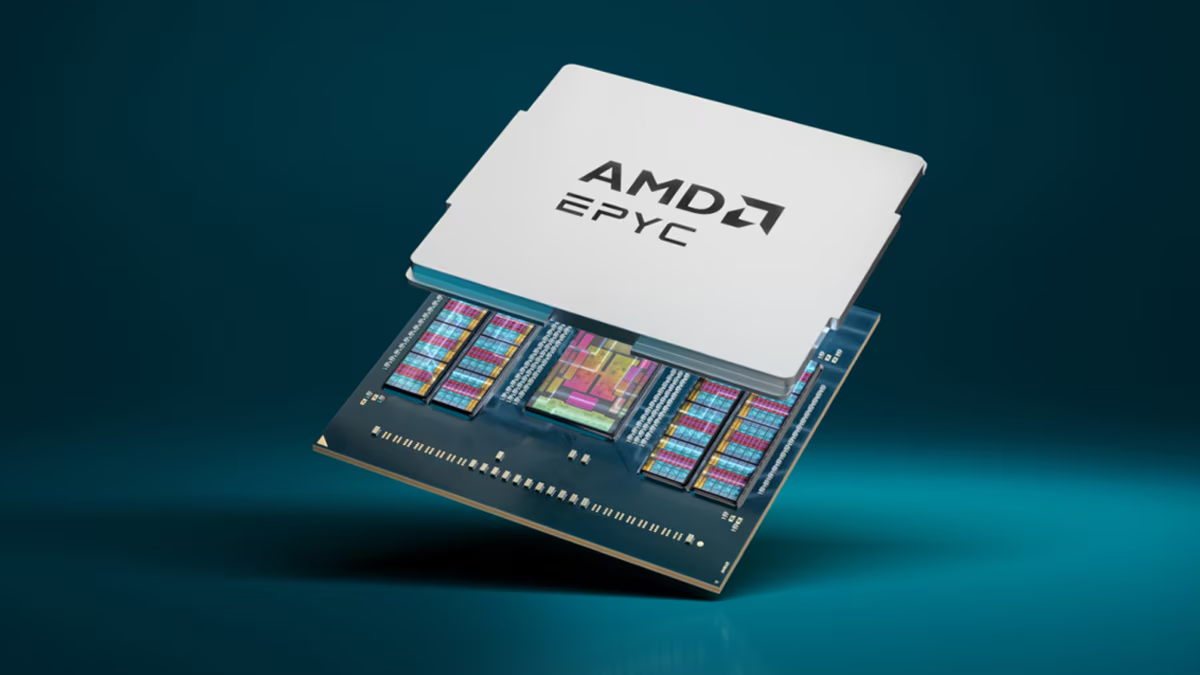
Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) carries a market capitalization of roughly $992.4 billion in afternoon trading today, putting the chipmaker within a rounding error of the trillion-dollar threshold. That places AMD at the doorstep of a club only 14 other companies currently occupy. The catalyst pushing it there: management is raising prices by 10% on AI accelerators, consumer GPUs, and chipsets, a move investors are reading as proof that demand is outrunning supply.

What a Trillion-Dollar Valuation Signals
The valuation is arriving on a financial trajectory that has bent sharply upward. AMD reported Q2 FY2026 revenue of $11.54 billion, up 50.1% year over year, and non-GAAP diluted EPS of $1.66 against a $1.61 consensus. Data Center, now the engine, hit $6.718 billion, up 107% year over year, or 58% of total revenue, with segment operating income of $2.10 billion versus a $155 million loss a year earlier.

Pricing power is the fuel behind the 10% hike. CFO Jean Hu told analysts on the Q2 call that in cloud and enterprise server, AMD delivered “double-digit growth in both units and ASPs” and that going forward investors should “expect both unit and ASP growth”. Non-GAAP gross margin expanded to 56%, up over 200 basis points year over year. When a chipmaker can raise prices into accelerating volume, the market usually rewards it, and it is doing so now.
Market Reaction
AMD shares are up 8.67% in Monday’s regular session, moving from $559.82 to $607.97, clearing the $600 line for the first time. The one-week gain sits at 17.55%, one-month at 30.08%, and year-to-date at 183.3%. The one-year return runs to 284.19%. Following the August earnings report, shares had already risen roughly 5%, and today’s move extends that momentum into trillion-dollar territory.
Bull Case
The bull case rests on three pillars visible in AMD’s own filings. First, the AI ramp spans multiple hyperscale customers. Strategic commitments now include Anthropic for up to 2 gigawatts of MI450 Series GPUs in Helios racks, OpenAI as a core preferred partner deploying 6 gigawatts of AMD GPUs, Meta for up to 6 gigawatts of AMD Instinct GPUs, and expanded Microsoft Azure collaboration on Helios. CEO Lisa Su put the per-gigawatt revenue opportunity at “double digit billions”.
Second, guidance is stepping up rather than tapering. Management guided Q3 2026 revenue to approximately $13 billion, plus or minus $300 million, implying roughly 41% year-over-year growth at the midpoint and about 13% sequentially, with non-GAAP gross margin near 56%. Su also flagged that AMD “now expect data center segment revenue to more than double year-over-year in 2027” and that the company expects to “significantly exceed our $20 annual EPS target”.
Third, the balance sheet supports the ramp. Debt-to-equity sits at 0.071, cash and short-term investments at $13.1 billion, and AMD repurchased $1.316 billion in stock during FY2025. Sell-side coverage skews positive at 4 Strong Buy and 39 Buy ratings against 11 Hold and zero Sell, with an analyst target of $616.51.

Bottom Line for Long-Term Holders
Retirement-focused investors should read the $991.7 billion market cap as a valuation now priced for execution. The trailing P/E of 211 is stiff, and Su herself flagged risks including U.S. export controls, a Gaming segment down 31% year over year, and a tight server CPU supply chain through the second half. But the pricing action, the guidance step-up, and the multi-gigawatt customer roster all point one way (we reverse-engineered what the biggest chip winners looked like early in a free playbook you can grab here). The next hard test is the Q3 report against the $13 billion revenue guide. Clear it, and AMD walks through the trillion-dollar door on its own numbers.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.