Fed Rate Hike Fails to Lift Bank Stocks as Market Reprices the Rally
The Fed raised rates for the first time in three years, and bank stocks promptly sold off. What looks like a contradiction might be a warning about where the trade goes from here.

The Federal Reserve lifted its target range to 4% on September 17, 2026, the first hike in three years.
Textbook finance calls this a gift to banks: loans reprice faster than deposits, net interest margins widen, profits follow. Instead, JPMorgan Chase (NYSE:JPM | JPM Price Prediction) fell 1%, Wells Fargo (NYSE:WFC) dropped 3%, and Goldman Sachs (NYSE:GS) gave back 4%. Prime rates rose the next day, but the stocks did not follow.
Positioning Ate the Catalyst
The move was the most telegraphed hike of the year, and the sector had already priced it in. The SPDR S&P Regional Banking ETF is up 12.6% over the past year and 13.55% year to date.
JPMorgan itself sits on a 13.75% one-year gain and a 151.42% five-year run. When everyone has already bought, the news arrives without a marginal buyer.
The curve is not helping either. The 10-year minus 2-year spread closed at 0.25% on September 18, down from 0.74% in February. A flatter curve compresses the very spread the hike was supposed to widen.
JPMorgan’s Mixed Signal
Q2 2026 looked pristine on the surface: adjusted EPS of $6.14, ROTCE of 23%, and net interest income up 10%. Management guided full-year NII to about $105.5 billion and raised the quarterly dividend to $1.65 per share.

CFO Jeremy Barnum, however, warned that deposit costs eventually catch up:
“At some point that kicks in.”
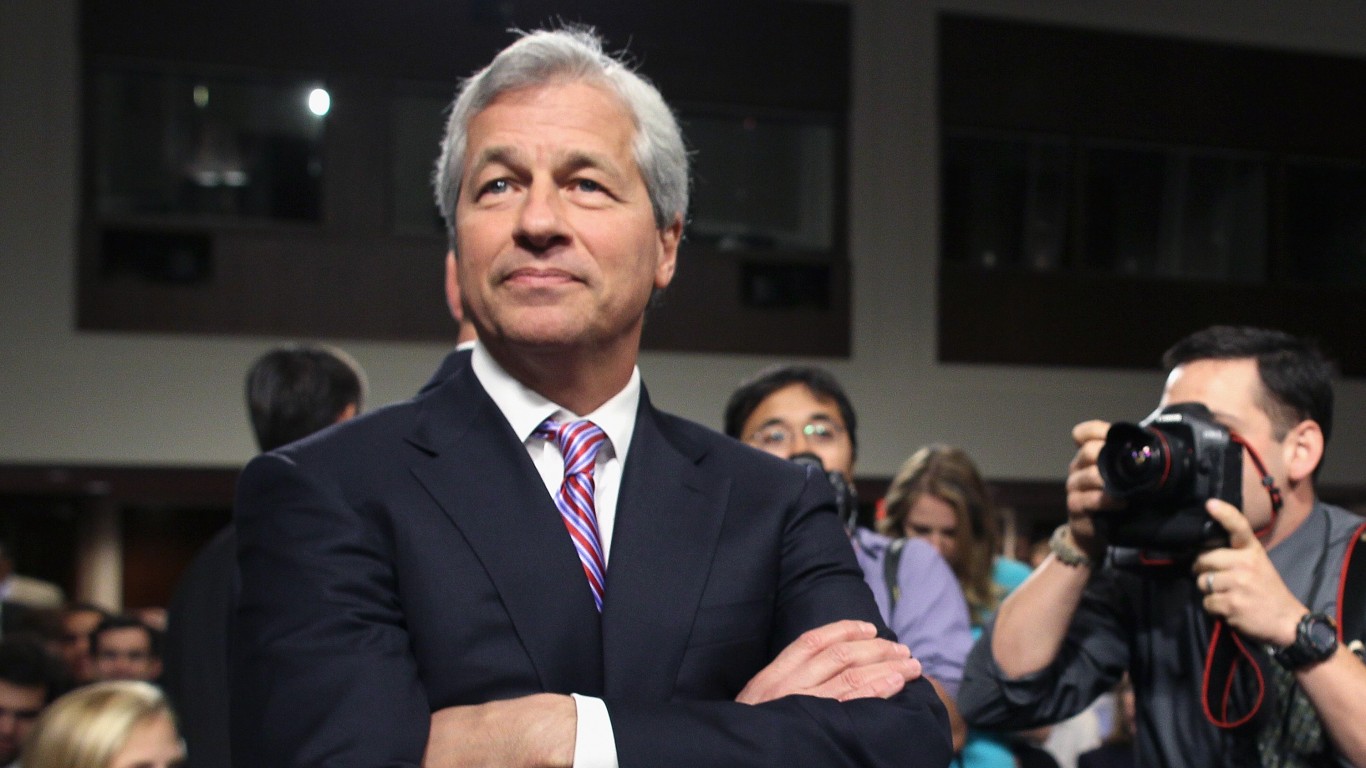
Jamie Dimon was blunter about the setup:
“It’s getting close to as good as it gets. We just don’t know how long it’s going to last.”
Credit Is the Real Question
Every extra hike squeezes borrowers. JPMorgan’s card net charge-off rate already sits at 3.33%, and its allowance for credit losses climbed 12% to $31.4 billion.
Wells Fargo carries a heavier consumer and commercial real estate book, so the same hike lands harder. Goldman earns most of its money from trading and advisory, so its 4% drop looked more like a crowded-long unwind than a credit signal.
Barnum has already flagged the swing variable:
“When it comes to consumer credit performance, it’s just about the labor market.”
Bull and Bear Case for JPM Stock

The bull case rests on scale and capital return. JPMorgan authorized a $50 billion buyback in July, delivered $21.16 billion of Q2 net income, and Dimon said the firm targets a 17% return on deployed capital.
The bear case is that the easy money in this trade is already priced in. The stock trades near $349.47, well above the $308.21 average Q2 buyback price, and further hikes tighten borrower cash flow before they widen bank spreads.
The deciding variable is Q3. If net interest margin expands and card losses stabilize, the September dip was noise. If deposit repricing accelerates while charge-offs drift higher, the market was front-running an earnings problem the NII bulls have been ignoring.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.