‘It’s Time for the Fed to Raise Interest Rates’: Ex-Fed President Defies Trump’s Ultimatum

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

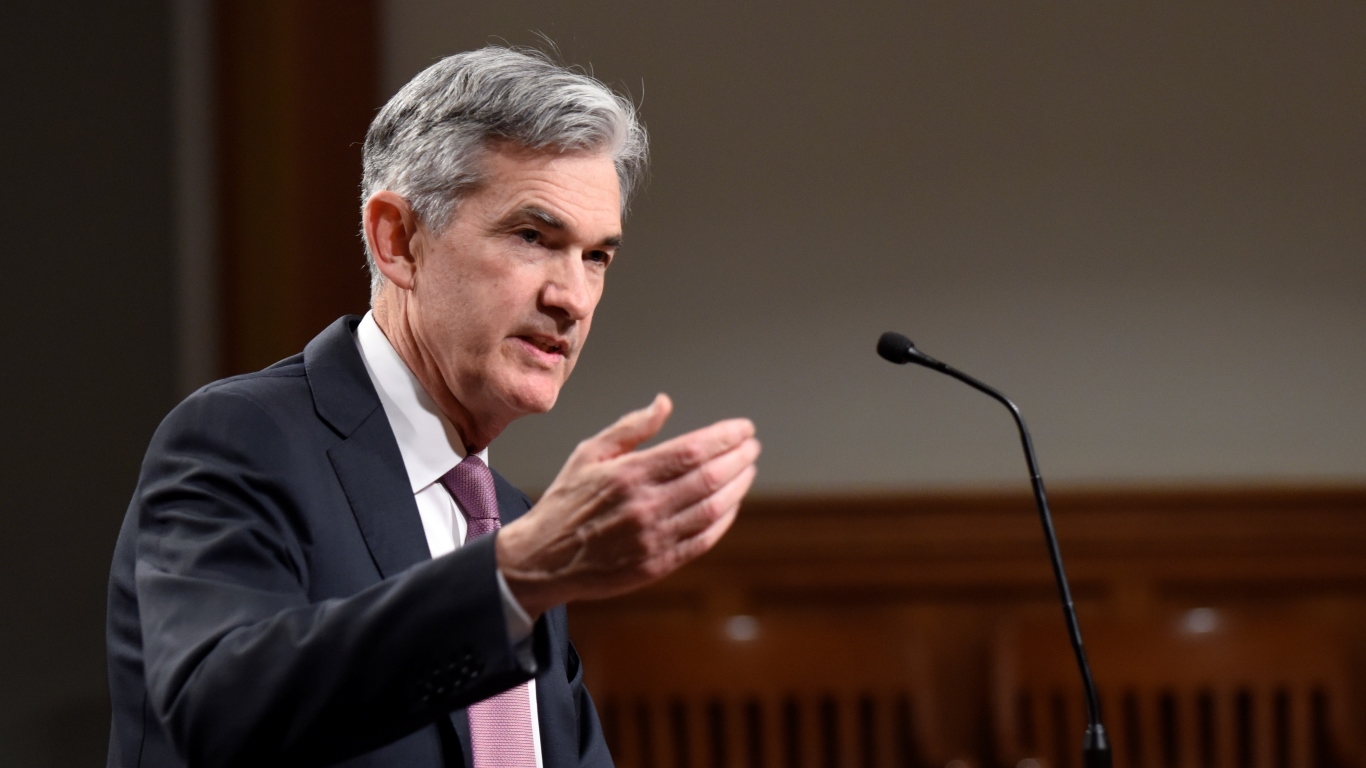
Within a few hours on the morning of September 8, the American interest-rate debate fractured in three directions at once. Former Cleveland Fed President Loretta Mester said it is time for the Federal Reserve to raise rates. Bond firm Payden & Rygel chief economist Jeffrey Cleveland warned that tariffs are acting as a tax dragging on growth while adding inflationary pressure, and said “this is reason, I think, for the central bank to hike interest rates this fall.” Economist Mohamed El-Erian said he would vote against a hike, arguing that today’s inflation drivers are largely insensitive to the price of money.
President Trump wanted the Fed moving the other way entirely. On September 4, he doubled down on a threat to halt trade with major surplus partners unless the Fed cuts, renewing the demand hours after an August payrolls report that bond traders read as a green light for a hike. The Fed had not moved since December 11, 2025, when it took the upper bound of its target range down to 3.75%. It held there through an unemployment rate sitting at 4.1% in both July and August.
Why the hawks got loud
The case rested on the Fed’s own preferred gauge. Core Personal Consumption Expenditures climbed to 130.66 in July, running 3.3% above the year-ago level. That was well above the Fed’s 2% target, and it came alongside a headline PCE reading of 3.7% year-over-year. Headline CPI has been choppier, which is part of why this was a debate rather than a consensus.
Canada’s retaliatory tariffs took effect September 8, ranging from 15% to 50% on roughly $20 billion of American exports, matching Washington dollar for dollar. El-Erian’s counter-argument was that a Fed hike cannot repeal a tariff, cannot pump more crude out of the ground, and cannot force chipmakers to build capacity faster. Raising rates into a supply shock would slow the parts of the economy that are working while doing little to the parts that are not.
That argument lost inside the building. Fed Chairman Kevin Warsh had said in late August that the Fed may have “work to do” on inflation, a line markets read as endorsing a September move. The White House spent the days that followed publicly pressuring him not to make it. The yield curve reflected the shift: the 10-year Treasury sat 0.41 percentage points above the 2-year on September 8, still a normal-shaped curve but flatter than the 0.74 spread it carried in February.
On September 16, the FOMC voted 12-0 to raise the federal funds rate by 25 basis points, lifting the target range to 3.75%–4.0%. It was the first rate increase since July 2023. Warsh emphasized at his press conference that inflation remains too high and that the Fed is serious about delivering price stability. The September dot plot placed the median year-end rate projection at 4.1%, leaving the door open to at least one more hike in 2026.
What the hike means at the kitchen table
Borrowers feel rate moves in two separate places, and the difference matters. Anyone shopping for a home is dealing with the bond market rather than the Fed directly, since a 30-year fixed mortgage prices off long yields. Households carrying revolving debt are the ones exposed to the Fed directly. An increase in the target range pulls the prime rate up with it and reprices variable-rate balances within a billing cycle. The average credit card APR for new offers has already climbed to above 22% as of October 2026, up from the roughly 21% level that prevailed before the September hike.
Savers get the mirror image, and it remains a thin one. The FDIC national average yield on a 12-month certificate of deposit reached 1.76% in October, up from 1.71% in August but still a rounding error against a 3.7% inflation rate. The signal to watch now is whether the Fed follows through with another hike before year-end. Mester and Cleveland called the September move correctly. Whether the dot plot delivers a second hike, or the tariff drag finally cools the economy enough to pause, is the question that will shape borrowing costs through early 2027.
Editor’s note: This article has been updated to reflect the September 16, 2026 FOMC decision, in which the Fed raised the federal funds rate by 25 basis points to a target range of 3.75%–4.0% in a unanimous 12-0 vote, and to incorporate the September dot plot median year-end projection of 4.1%, the updated FDIC 12-month CD national average of 1.76%, and the post-hike rise in average credit card APRs to above 22%.
Contact [email protected] for any questions or corrections.
Gerelyn Terzo is the author of dividend investing handbook "Dividend Investing Strategies: How to Have Your Cake & Eat It Too." A veteran financial journalist, she covers agri-finance for outlets like Global AgInvesting and the broader stock market and personal finance for 24/7 Wall Street. She began at CNBC and later helped launch Fox Business in New York. Gerelyn currently resides in Woodland Park, Colorado and dabbles in nature photography as a hobby.