Tech Exec Says China Is About to Burst the Memory Chip Pricing Bubble
Acer's chairman just accused the world's biggest memory chip suppliers of using public shortage forecasts as a covert pricing signal, and he named a specific date when the whole story falls apart.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Jason Chen, the chairman of Taiwanese PC maker Acer, walked into a room of reporters this month and said out loud what almost nobody on the supply side of the memory chip business will admit: the shortage story is a story. “How could it stay short forever? Chinese capacity keeps coming onto the market. The supply shortage problem has already completely disappeared,” he told the press. His timing was pointed. Two days earlier, on September 20, China’s CXMT confirmed that a new memory chip platform had entered mass production, and Barron’s had already flagged the buildout as a bigger problem for SK Hynix than for Micron. Chen thinks the bubble in dynamic random access memory (DRAM) and NAND flash pricing is about to leak.
Why a PC Executive Is Calling Out the Cartel Signal
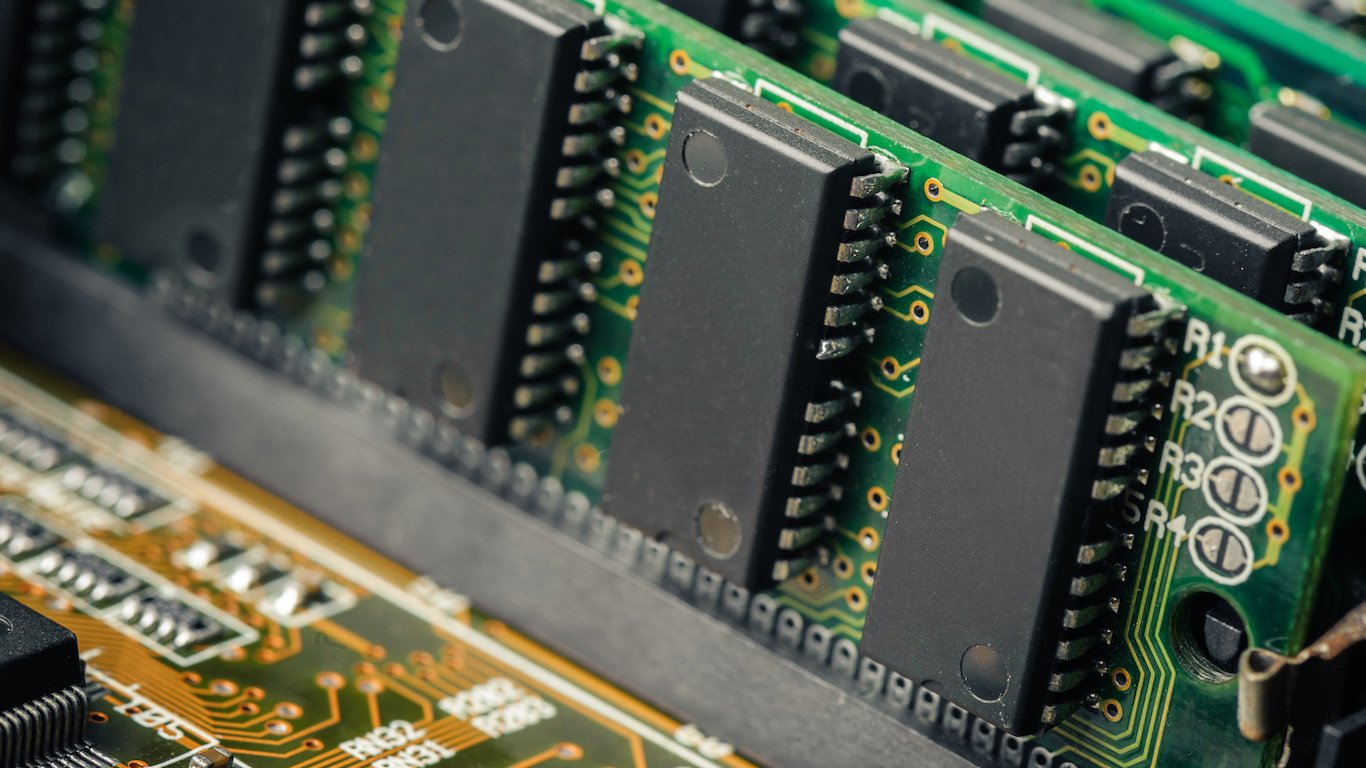
The memory chip market has three dominant suppliers: Samsung, SK hynix, and Micron (NASDAQ:MU | MU Price Prediction). Chen argues that when SK hynix or Adata publicly forecasts a shortage extending to 2030, they are signaling coordination rather than making a prediction. Antitrust rules prevent them from coordinating prices directly, so they use public statements to send a kind of “signal” to one another. The stakes are enormous for anyone who touches a laptop or a server. PC prices are expected to rise 5% to 20% toward the end of 2026, plateau in the first half of 2027, and start declining after that, with component costs peaking around mid-2027 as fresh capacity runs at scale.
Chinese Fabs Are Already Inside Your Next Laptop
The evidence for Chen’s thesis is concrete. CXMT and YMTC parts are already being designed into products by Acer, HP (NYSE:HPQ), Asus, and Lenovo. That is a structural break from the last cycle, when Chinese memory was treated as second-tier and confined to domestic buyers. Once the top four PC brands qualify a supplier, the pricing power of the incumbents erodes fast, because buyers can play vendors off each other on every purchase order.
The macro backdrop strengthens the accusation. The Federal Reserve nudged the funds rate upper bound to 4.00% from 3.75% on September 17, and the core Personal Consumption Expenditures index hit 130.66 in July, its highest reading on record. Chen argues that hardware price hikes in memory, solid-state drives, printed circuit boards, and fiberglass cloth feed directly into inflation, forcing the Fed to keep money expensive. He called the chain “not a normal phenomenon.”
What Breaks the Story by Mid-2027
Chen conceded the near term is ugly. He expects further price increases in the first quarter of 2027, though smaller in magnitude, before the reversal. The signal to watch is narrow and specific: the gross margins reported by SK hynix and Micron on their next two DRAM earnings updates, and the bit-shipment share disclosed by CXMT in Chinese trade filings. If Chinese output keeps climbing while incumbent margins stay near cycle highs, Chen’s cartel-signal theory looks right, and Washington will notice. If margins compress first, the market did the antitrust work on its own. Either way, the 2030 shortage narrative does not survive a mid-2027 capacity wave. Acer is betting its 2027 procurement book on that call.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.