Broadcom Has More Than One Way to Win. Here’s Where I See the Stock Going
Broadcom just posted its strongest quarter in company history and the stock barely moved. Understanding why the chart looks broken is the first step toward seeing where it actually goes from here.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

I am bullish on Broadcom (NASDAQ:AVGO | AVGO Price Prediction) heading into the back half of fiscal 2026. AVGO trades at $349.65, well off its 52-week high of $493.28, despite posting its most explosive AI quarter yet.
Our 24/7 Wall St. price target for Broadcom is $427.46, implying roughly 20.4% upside over the next 12 months, with a buy rating and 90% confidence.
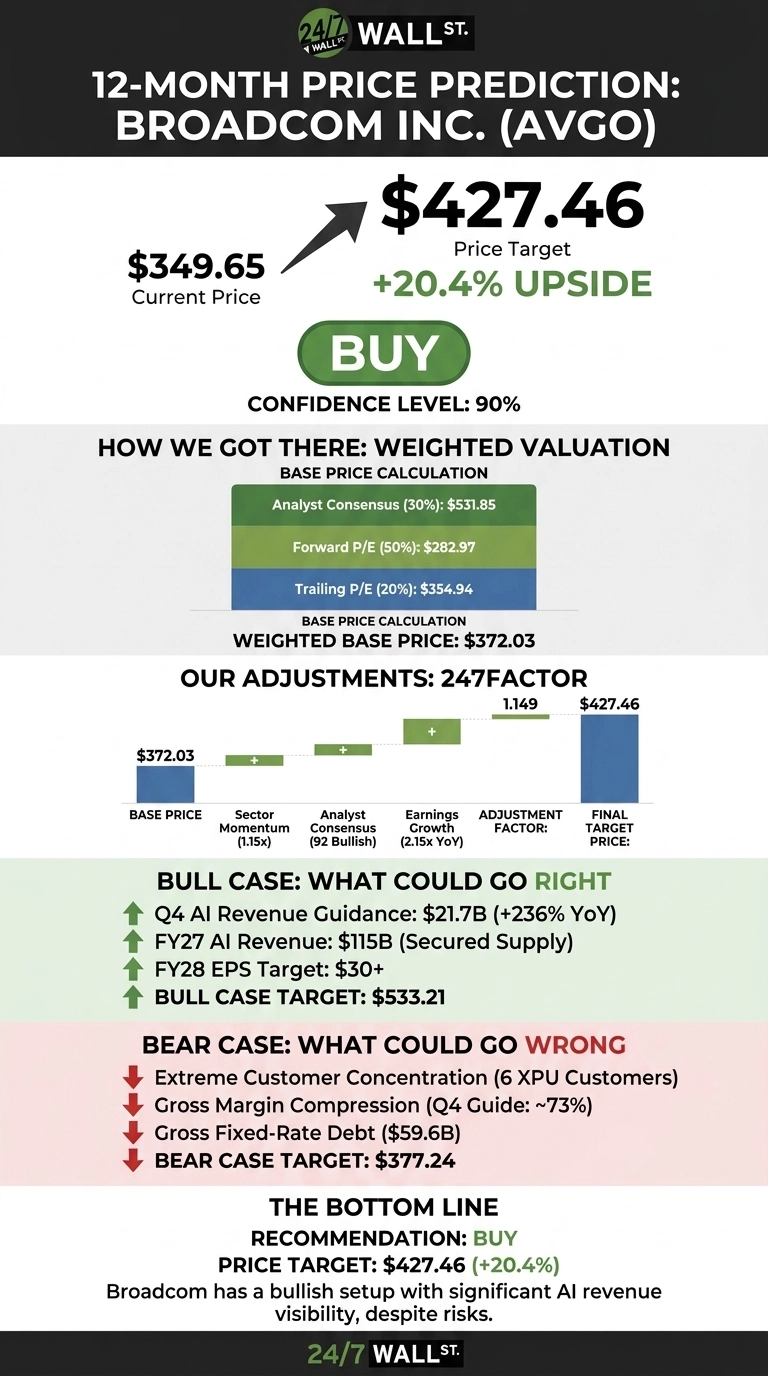
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $349.65 |
| 24/7 Wall St. Price Target | $427.46 |
| Upside | 20.43% |
| Recommendation | BUY |
| Confidence Level | 90% |

Why a Blowout Quarter Hasn’t Fixed the Chart
Broadcom is up just 1.58% year-to-date and down 2.36% over the past month, despite Q3 FY2026 results that were arguably the strongest in company history.
Revenue hit $29.59 billion, up 85.5% year over year, with non-GAAP EPS of $3.32 beating consensus for the ninth straight quarter. AI semiconductor revenue alone was $16.70 billion, up 221% YoY. A Financial Times report that China is reviewing its dependence on Broadcom data-center switches likely explains the recent pullback.

Why Bulls See a Path to $530 and Beyond
The bull case is quantifiable. CEO Hock Tan guided Q4 AI semiconductor revenue to $21.7 billion, up 236% year-on-year, with fiscal 2026 AI revenue outlook of $58 billion.
Management disclosed secured supply for approximately $115 billion in fiscal 2027 AI revenue and a path to $230 billion in fiscal 2028, with Tan stating Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”
Customer commitments include Google TPU volume, 5 gigawatts of TPU v8i for Anthropic in 2027, and OpenAI’s Jalapeno accelerator. Consensus analyst target is $531.85, and Morningstar values the stock at $650. Our bull scenario one-year target is $533.21.

What Could Go Wrong
Risks are substantial. Customer concentration is extreme, with AI revenue tied to just six XPU customers. Gross margin is compressing as XPU mix rises, with Q4 consolidated gross margin guided to approximately 73%, compared with 78% a year ago.
Operating margin holds at roughly 66% because revenue outpaces opex growth. Add $59.6 billion in gross fixed-rate debt, potential residual-value guarantees on the Apollo/Blackstone AI XPV platform, and the China switch review. Our bear-case one-year price is $377.24.

How Broadcom Compares to NVIDIA and AMD
NVIDIA (NASDAQ:NVDA) trades at a forward P/E of 25 with a profit margin of 63.7%. Broadcom’s forward multiple of 19 looks cheap by comparison, explaining why the 24/7 Wall St. price target has room to expand toward analyst consensus.
Advanced Micro Devices (NASDAQ:AMD) trades at a forward P/E of 40 with a profit margin of just 15.6%. Paying double Broadcom’s forward multiple for a fraction of the margin profile makes AVGO the more disciplined way to own AI infrastructure.
| Company | Forward P/E | Profit Margin |
|---|---|---|
| Broadcom | 19 | 42.9% |
| NVIDIA | 25 | 63.7% |
| AMD | 40 | 15.6% |
Broadcom Price Prediction 2026-2030
The 24/7 Wall St. price target of $427.46 with a buy rating and 90% confidence reflects real conviction. The visibility of $115 billion in fiscal 2027 AI revenue against a forward multiple well below NVIDIA and AMD supports this call.
The setup looks compelling for investors who can stomach headline risk from China and hyperscaler capex debates. Investors who require a name without customer concentration or debt-service exposure may prefer alternatives.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $369.70 |
| 2027 | $427.13 |
| 2028 | $479 |
| 2029 | $531.60 |
| 2030 | $578 |
These projections assume Broadcom executes on its custom AI accelerator roadmap and VMware software transition. Significant upside or downside could result from hyperscaler capex swings or China trade policy shifts.
Broadcom’s XPU story rides on the same data-center buildout powering everything from switches to cooling, and we profiled seven of the non-chipmaker suppliers behind that buildout in a free AI infrastructure report.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.