Prediction: Broadcom Could Be the AI Winner After Nvidia
Nvidia dominates AI compute, but hyperscalers are quietly shifting billions toward a rival chip architecture that costs less than half as much per workload. One semiconductor giant is positioned to capture that spending, and its valuation still hasn't caught up…


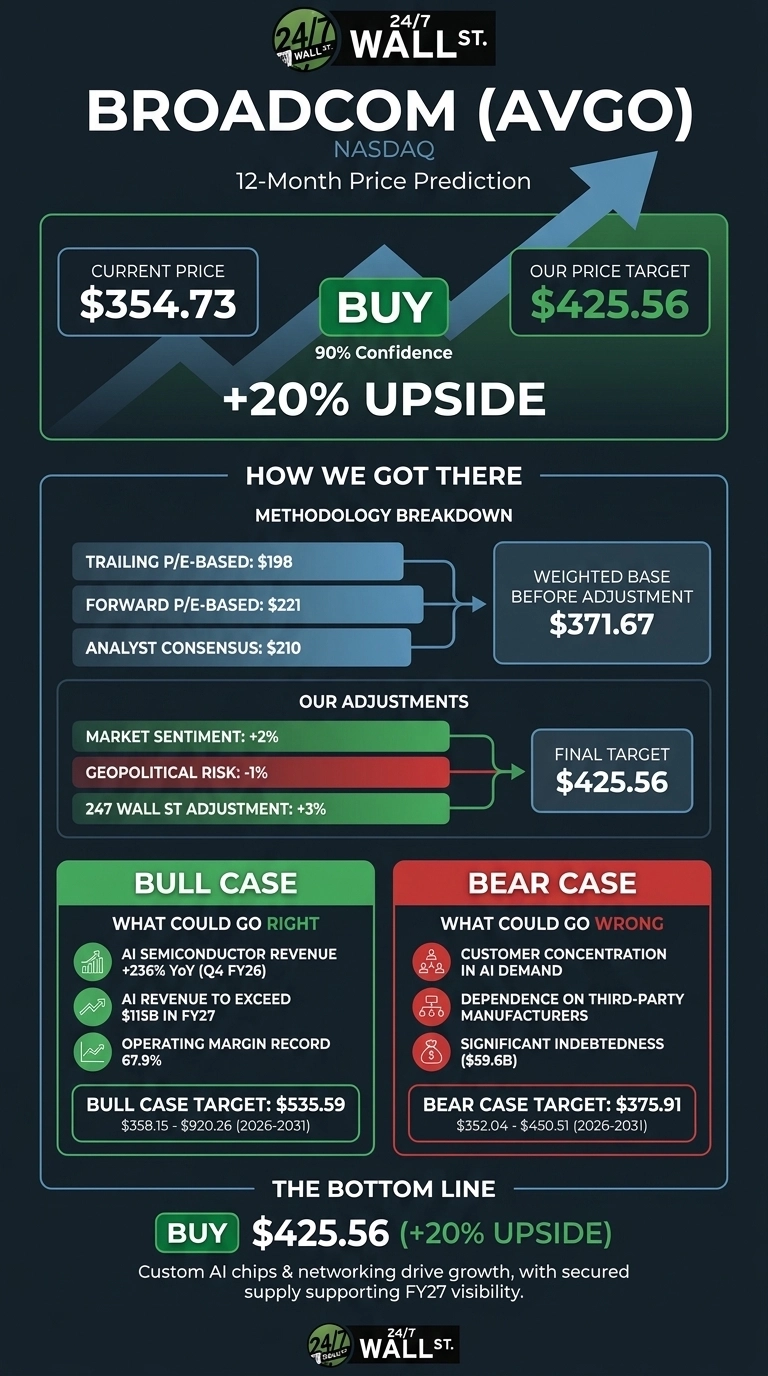
Broadcom (NASDAQ:AVGO | AVGO Price Prediction) is turning custom AI chips into the fastest-growing revenue stream in large-cap semiconductors. Based on our proprietary model, the 24/7 Wall St. price target for Broadcom is $425.56 over the next 12 months. That means 19.97% upside from the current $354.73.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $354.73 |
| 24/7 Wall St. Price Target | $425.56 |
| Upside/Downside | 19.97% |
| Recommendation | BUY |
| Confidence Level | 90% |
Broadcom has delivered a 9th consecutive EPS beat, guided AI semiconductor revenue to $21.70B next quarter, and trades at a forward multiple below what its growth rate suggests.
NVIDIA (NASDAQ:NVDA) still owns general-purpose AI compute. Broadcom is building the custom-silicon and Ethernet layer that hyperscalers and AI labs are using to lower their cost per workload, and that is where I see the next leg of AI value creation.

Broadcom Shares Stall While AI Revenue Triples
The stock has fallen 2.07% over the past week and 1.76% over the past month, and it is up just 3.13% year to date. It sits between a 52-week low of $288.95 and a high of $493.28. This week chip stocks slid after a “casino” comment by Broadcom’s chief executive, which added to sector volatility.
Fiscal Q3 revenue of $29.59B beat the $29.44B estimate and rose 85.5% YoY. Non-GAAP EPS of $3.32 exceeded the $3.24 estimate. AI semiconductor revenue reached $16.70B, up 221% YoY.

Why Bulls See $535 and Beyond
The bull case reaches $535.59, which is close to the consensus target. Of the analysts covering Broadcom, 7 rate it Strong Buy, 40 Buy and 3 Hold, with zero Sells.

Management expects fiscal 2027 AI revenue of approximately $115 billion and has line of sight to $230 billion in fiscal 2028. Hock Tan said Broadcom is “very much on target to exceed $30 in earnings per share in fiscal 2028.”
Anthropic is expected to become Broadcom’s largest XPU customer in 2027. Google (NASDAQ:GOOGL), OpenAI and Meta (NASDAQ:META) are scaling custom accelerators that management says cost “less than half the cost” of a GPU.
Risks That Could Cap Broadcom Near $376
The bear case sits at $375.91. Broadcom has only six XPU customers, and deployments depend on customers securing land, power and data center shells. Gross margin fell 210 basis points sequentially to 75%.
That drop reflects the higher memory content in XPUs, and operating margin still hit a record 67.9%. Debt totals $59.6 billion, though Broadcom paid down $5.6 billion last quarter. Residual value guarantees linked to AI lab financing are a potential risk worth tracking.
How Broadcom Compares to NVIDIA and AMD
NVIDIA is the benchmark Broadcom’s XPUs aim to undercut, and it competes directly in AI networking. Its Data Center Networking revenue reached $40.31 billion, up 138%, and the stock trades near 46 times trailing earnings.
AMD (NASDAQ:AMD) competes for the same hyperscaler AI budgets. Its Data Center revenue grew 107%, but it trades at about 224 times trailing earnings.
| Company | P/E | Latest Quarter Revenue Growth |
|---|---|---|
| Broadcom | 19x (forward) | 85.5% |
| NVIDIA | 46x (trailing) | 105.85% |
| AMD | 224x (trailing) | 50.11% |
Broadcom grows faster than AMD and trades at a far lower multiple than either peer. Against this group, our 24/7 Wall St. price target looks conservative.
Broadcom Earns a Buy Rating at $355
I rate Broadcom a buy with a 24/7 Wall St. price target of $425.56 and 90% confidence. What tips the scale is the visibility on fiscal 2027 AI revenue, which management says is supported by secured supply.
The bull case strengthens if Broadcom delivers its Q4 AI guide. It weakens if data center power delays push customer deployments into 2028. (The features that showed up in the last generation of monster chip winners are the same ones we cataloged in a free playbook here: The Next Nvidia Playbook.)
Broadcom Price Prediction 2026-2030
Our model projects where Broadcom could trade if current growth trends hold.
| Year | 24/7 Wall St. Price Target (Base) | Bull Case |
|---|---|---|
| 2026 | $355.25 | $358.15 |
| 2027 | $427.82 | $509.87 |
| 2028 | $491.28 | $617.36 |
| 2029 | $528.88 | $735.75 |
| 2030 | $584.38 | $861.88 |
These estimates rely on Broadcom keeping execution on its XPU roadmap on track. The biggest swing factors are faster gigawatt deployments at Anthropic and OpenAI on the upside and customer concentration on the downside.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.