Flex’s AI Data Center Spin-Off Just Got a $37.5 Billion Price Tag
General Catalyst just put a stunning price tag on a business most Flex investors barely noticed, and the stock's muted reaction suggests Wall Street has not yet figured out what that number actually means for shareholders.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
A business most investors know only as a line item inside a contract manufacturer now has an outside price. On October 5, 2026, Flex (NASDAQ:FLEX | FLEX Price Prediction) said investors led by General Catalyst, with Koch Equity Development, will put $2.0 billion of convertible preferred stock into Axiom, its planned data center spin-off.
Axiom’s enterprise value is $37.5 billion, according to Flex. It was negotiated privately for a minority stake, the first outside mark on a business embedded inside a low-multiple manufacturer.
Flex’s market capitalization was $43,131,494,280 on October 6, 2026.
Flex rose 0.13% on October 5 to $116.76, up 108.02% over the past year. The question is whether that run already priced Axiom in.
Power and Cooling Now Limit AI Buildouts
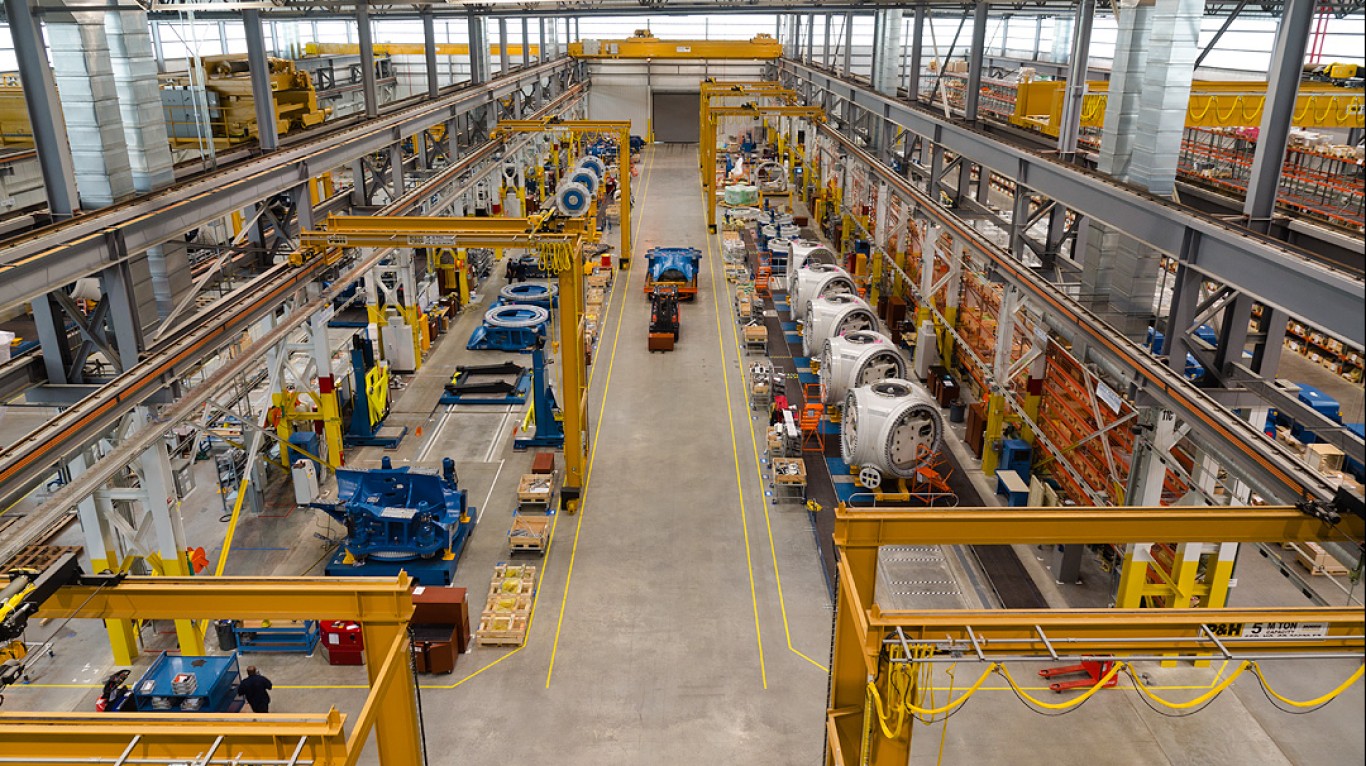
Axiom makes the power systems, liquid cooling and integrated computing hardware that AI data centers physically need. Chief executive Revathi Advaithi described the problem on the July 29, 2026 earnings call: “As AI scales, the constraint is no longer just the chip. It’s everything around the chip.”
Flex said the segment generated $6.6 billion in revenue for the fiscal year ended in March and $2.2 billion last quarter, up 35%. It forecasts 65% to 75% growth for the current fiscal year, the kind of pull-through that is lifting a whole roster of suppliers behind the AI expansion (we covered seven of them, from power to cooling, in a free report you can grab here).
How the Axiom Deal Is Structured
General Catalyst leads the round, with Koch Equity Development as a strategic co-investor. Flex expects to complete the tax-free separation in the first quarter of 2027.
Tax-free means Flex holders receive Axiom shares without paying tax, with cost basis split between the two holdings. Flex’s filings warn the spin-off “may not be completed on anticipated timeline or at all.”
Preferred Investors Get Paid Before You
Flex said the proceeds help fund Axiom’s $4.4 billion acquisition of EPC Power. Preferred stock is a class of shares that pays a set dividend and ranks ahead of common stock. Seniority means its holders collect before common shareholders do.
Flex said the preferred pays a 10% dividend before the separation and then converts into Axiom shares. Existing holders bear that cost in exchange for a reliable outside valuation and a deal that Revathi Advaithi said “will allow Axiom to have a strong balance sheet.”
General Catalyst’s Hemant Taneja said “Axiom sits at the center of the power and infrastructure buildout that AI demands,” but his firm benefits from a high valuation. Growth depends on a few hyperscalers whose capital spending can shift in a single quarter.
The remaining business makes lower margins. Last quarter, Flex’s other segments posted adjusted operating margins of 5.2% and 6.6%, versus 9.7% for the cloud and power unit.
What the Axiom Mark Means for FLEX Stock
Outside investors valued one piece of Flex near the company’s full market value, yet shares trade at 24x forward earnings and sit below the 52-week high of $166.86. The flat reaction to a fresh outside mark suggests the market has yet to fully price the separation.
The stock is up 93.25% year to date. Flex holders gain exposure to Axiom through the spin, and the cost is dilution from the preferred.

The test comes at the November 10, 2026 Investor Day. If Axiom’s standalone margin targets show no path toward peer levels, or the stock closes below its 200-day moving average of $99.61, this call is wrong.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.