Prediction: This Company Could Be One of AI’s Biggest Winners by 2028
Broadcom's AI revenue is exploding at triple-digit growth rates, yet the stock has barely moved in 2025. Something has to give, and figuring out which way it breaks could make or break your 2028 portfolio.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Broadcom (NASDAQ:AVGO | AVGO Price Prediction | AVGO Price Prediction) just reported a standout quarter. Fiscal Q3 revenue reached $29.59 billion, up 85.5% YoY. AI semiconductor revenue hit $16.7 billion, up 221%.
CEO Hock Tan said, “Demand for our custom AI accelerators and networking continues to be very strong.” Even so, the stock is up only 0.72% this year.
I see that gap as the central question for investors. This article asks one question: can Broadcom hit $550 per share in 2028?

What’s Holding Broadcom Back Right Now
The stock traded at $371.27 on Sept. 2 and has fallen since, down 6.22% over the past month.
Three issues weigh on it: management guided consolidated gross margin down to about 74% due to product mix; the company relies on a small number of large AI customers; and with a beta of 1.46, Broadcom moves more sharply than the market when AI enthusiasm cools off. The stock needs new evidence to move higher.
Wall Street Sees 51.4% Upside. Our Model Says 20.7%
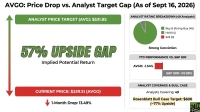
The consensus price target sits at $531.85, suggesting 51.4% upside. Analyst ratings stand at 8 Strong Buy, 37 Buy, 4 Hold and 0 Sell. Our model is more conservative.
Its one-year base case lands at $423.79, or 20.67% upside, within a range of $374.67 (bear case) to $532.91 (bull case). The model’s confidence score of 0.9 means it has high conviction in that range.
On this one, I side with the Street. 92% of analysts are bullish, and earnings growth adds 0.03 to the model, which labels it “strong earnings acceleration.” Management also says its visibility now runs “all the way to 2028.”

Here’s What It Takes for Broadcom to Reach $550
Reaching $550 from $351.19 means a rise of 56.6%. At forward EPS of $18.3613, a $550 share price implies a forward P/E of 30x, about 6x below the model’s implied 36x. The rerating needed is a move from today’s multiple to 30x.
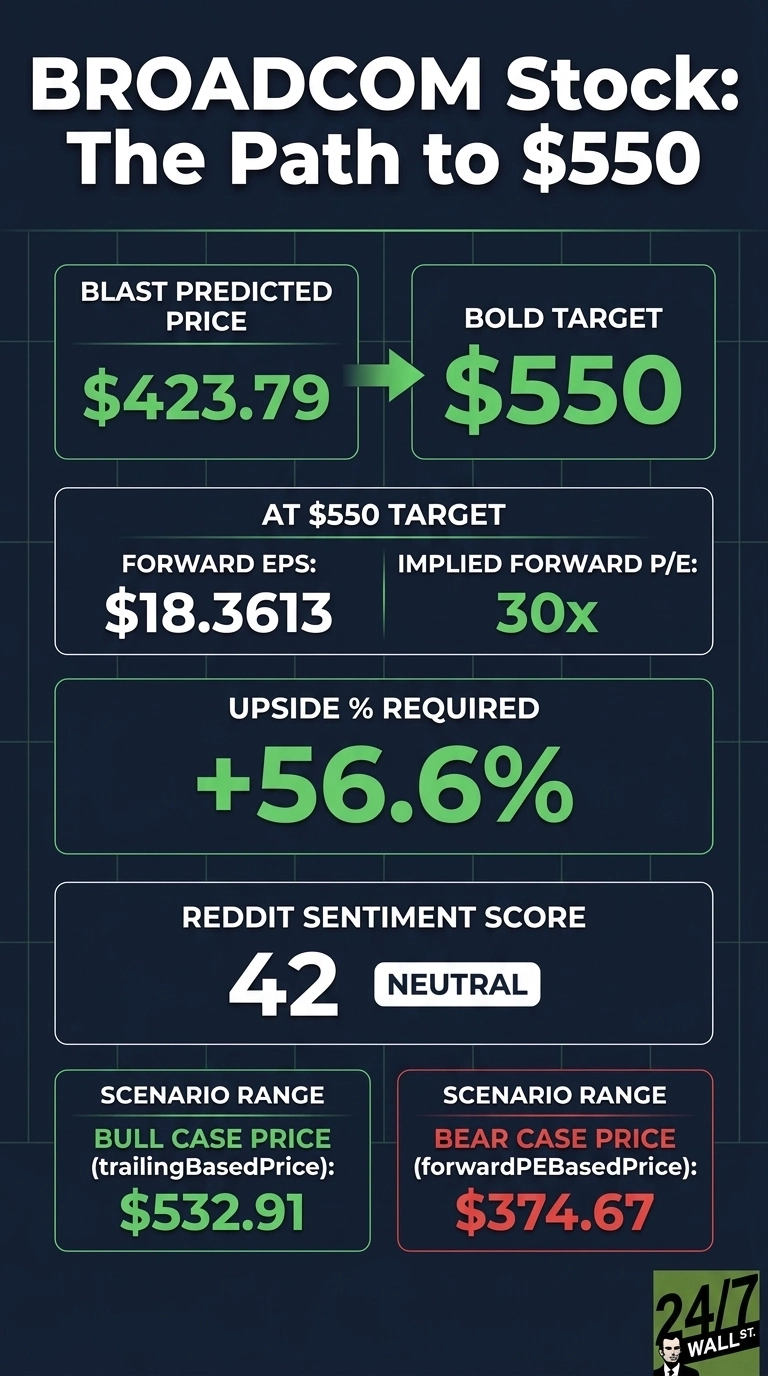
The model’s adjustment factor of 1.146 comes from a 1.15 sector momentum multiplier and strong analyst consensus, partly offset by a 50% mega-cap penalty. Earnings growth is contracting the multiple: trailing P/E is 46x, forward P/E is 19x.
Q4 guidance calls for AI revenue of $21.7 billion, up 236%. Management expects fiscal 2027 AI revenue “in excess of $100 billion.” Barron’s reported Anthropic and Broadcom are becoming more intertwined.
CEO Tan: “Demand for XPUs and networking is simply insatiable.” The main risk: Alphabet (NASDAQ:GOOGL) unit Google plans some diversity of sources for chips, potentially limiting the multiple.

Where Broadcom Trades Today vs Its Earnings Power
Broadcom trades at 19x forward earnings, a low multiple for a company growing revenue at 85.5%. The stock sits between its 52-week low of $288.95 and high of $493.28.
Over 10 years, it has returned 2,482.49%. At today’s multiple, the market prices in little of the 2027 AI ramp, the core of the optimistic thesis.
Can Broadcom Really Hit $550? My Verdict
Hitting $550 requires a 56.6% gain. I consider it reachable. Our 2028 bull case reaches $624.06 by October 2028. Three things must go right:
- AI revenue passes $100 billion in fiscal 2027.
- Gross margin stabilizes.
- OpenAI and Meta Platforms (NASDAQ:META) deployments ship on schedule.
A spending pullback by a major hyperscaler could disrupt the target. Such gains are rare in any single year, and we’ve outlined the path for how Broadcom could reach $550 in 2028. The signs that showed up in past AI-chip winners before their monster runs are the ones we cataloged in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.