3 Hydrogen Stocks Worth Watching This October
Hydrogen stocks remain speculative. The three companies below lose money and carry higher risk than established industrial companies. Measurable milestones will move these stocks. Each company below gets one verifiable number it must hit. How We Ranked These Three Hydrogen…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Hydrogen stocks remain speculative. The three companies below lose money and carry higher risk than established industrial companies. Measurable milestones will move these stocks. Each company below gets one verifiable number it must hit.
How We Ranked These Three Hydrogen Names
We ranked the stocks on three factors:
- Liquidity runway: how much cash each company holds against its burn rate and market value.
- Margin trend: whether gross margin is getting better quarter over quarter.
- Milestone proximity: how soon the company’s own stated target can be confirmed or ruled out.
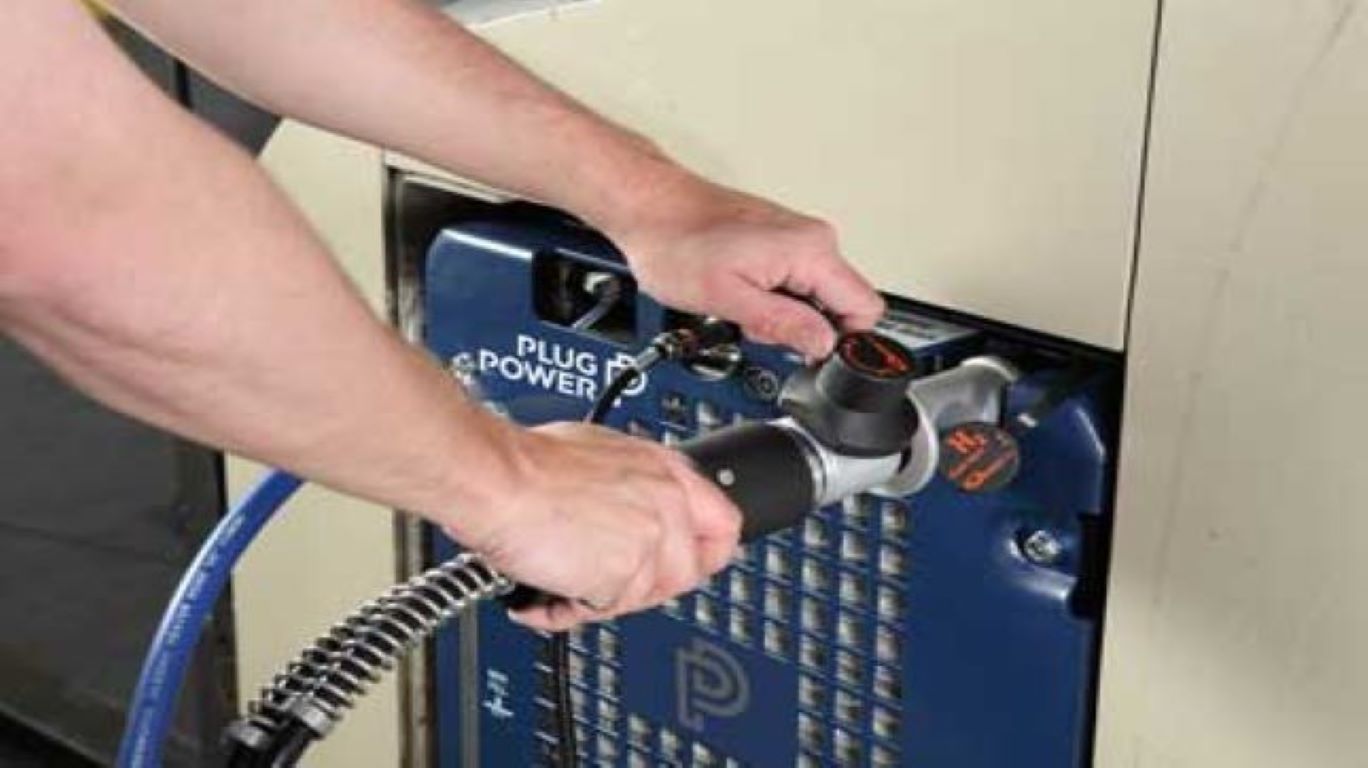
#3 Plug Power: Positive EBITDAS in Q4 2026
Plug Power (NASDAQ:PLUG) sells GenDrive fuel cells for warehouse forklifts and also supplies hydrogen fuel and electrolyzers. That puts it in production, distribution and equipment at once. Its Q2 report beat on both lines: adjusted EPS came in at -$0.07 versus a -$0.08 estimate, and revenue reached $178.3M versus $169.1M expected. Gross loss narrowed to -$1.68M from -$53.47M a year earlier. GenDrive installations rose to 1,666 units.
Liquidity is weak. Unrestricted cash stood at $161.9 million, while net cash usage ran about $61 million for the quarter. Operating expenses benefited from $39.7 million of recoveries of previously impaired assets. Plug has collected roughly $52M of its $275M asset monetization target. The stock trades at $1.90, down 32.86% over the past year.
The number: positive EBITDAS in Q4 2026. If Plug misses, it falls back on further asset sales or equity, and dilution risk rises.
#2 Ballard Power Systems: Positive Operating Cash Flow by End of 2027
Ballard Power Systems (NASDAQ:BLDP) makes fuel cell engines for buses, rail and stationary power. It closed its GeoPura acquisition on August 28, 2026, which adds hydrogen power units and fuel supply to the business. Ballard’s Q2 missed on both lines. EPS came in at -$0.07 versus -$0.045 expected and revenue at $20.6M versus $25.6M. Gross margin still turned positive at 20%, and operating expenses fell 34%.
Before the deal, cash of $502.1M covered nearly 70% of the $719.7M market cap. GeoPura’s initial consideration of 275 million pounds will reduce that buffer. The next milestones are 2026 operating expenses within $65M to $75M and progress toward $25 million in run-rate EBITDA savings by 2028.
The number: positive operating cash flow by end of 2027. If Ballard misses, the energy-as-a-service pivot starts to look like expensive diversification paid for out of a shrinking cash pile.
#1 FuelCell Energy: 100 MW Annualized Production This Month
FuelCell Energy (NASDAQ:FCEL) builds stationary carbonate fuel cell power plants, and data centers are increasingly its target customers as AI electricity demand strains the grid (we rounded up seven non-chipmaker ways to play that expansion in a free report here). Its fiscal Q3 was rough. GAAP EPS came in at -$0.64 versus -$0.39 expected, and revenue reached $33.0M versus $38.8M. Gross loss was -$24.5M, driven by $17M in Phase 0 charges.
FuelCell has the strongest balance sheet: $658.1M in unrestricted cash and no corporate convertible debt. The share count rose from 46M to 80M since Oct 2025. Backlog reached $3.6B, but the CFO warned that awarded backlog “is not contracted firm order backlog or a guarantee of future revenue.” FuelCell’s commitments fall into three levels:
- Fit Energy: a signed agreement for up to 380 MW. Only the 30 megawatt Phase 0 is committed, and later phases are at Fit Energy’s option.
- Texas data center: a 75 MW capacity reservation that has not yet become a definitive agreement.
- Siemens: a memorandum of understanding, not a contract.
The number: a 100 MW annualized production rate by October 2026, up from roughly 37 megawatts last quarter. If FuelCell misses, Phase 0 losses continue and its positive adjusted EBITDA target for Q4 fiscal 2027 is at risk.
Three Numbers That Decide Hydrogen’s Next Chapter
FuelCell tops the ranking because its test arrives this month and it has the most cash to absorb a stumble. Ballard has strong margin momentum but must make a large acquisition pay off. Plug has the best operating momentum and weakest liquidity. Track 100 MW in October, positive EBITDAS in Q4, and operating cash flow by 2027. Each figure will show whether that company’s story remains credible.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.