“Unprecedented Test Of Investor Gullibility”: Analyst Says Anthropic Could Be Overvalued By As Much As 93% At A $2 Trillion IPO Valuation
One analyst is calling Anthropic's upcoming IPO the most ridiculous deal of 2026, and his reverse-engineered math suggests the company may need to pull off a near-impossible growth trajectory to justify what investors are being asked to pay.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
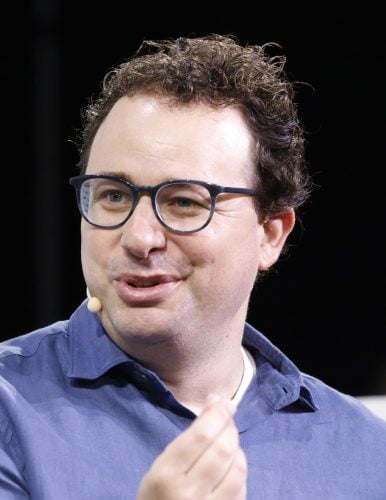
New Constructs senior investment analyst Kyle Guske II calls Anthropic’s planned offering an “unprecedented test” of investor gullibility. His note, released Tuesday, titled the deal the most ridiculous IPO of 2026, according to CNBC. CNBC reported on October 7 that Anthropic will be the “most ridiculous IPO” of the year.
He is measuring against a listing valuation of around $2 trillion, according to Moomoo. The firm’s low scenario implies Anthropic would be overvalued by 93%. New Constructs says it receives no compensation for writing about specific companies.
Three Scenarios Behind a $2 Trillion Question, according to Moomoo
The firm built a reverse discounted cash flow model, which starts from a price and works backward to the business performance that price would require. All three cases use 100% revenue growth in 2027, differing only in what happens after.
| Scenario (firm’s assumptions) | Operating Margin | Revenue CAGR, 2028 to 2035 | Implied Equity Value |
|---|---|---|---|
| Justifies listing valuation | 10% | 56% | $2 trillion |
| Growth slows | 20% | 36% | $1.1T |
| Mature social media profile | 20% | 20% | $144B |
The model applies a 9.33% discount rate based on seven mega-cap technology peers. It deducts $518 billion in liabilities for planned cloud and data center spending. The authors note their assumptions may be too optimistic, as Anthropic could need more cash and computing spending than projected.
A Label New Constructs Has Used Before
According to CNBC, New Constructs called WeWork the most ridiculous IPO of 2019; WeWork later went bankrupt.
Why the Firm Sees Exit Liquidity
New Constructs argues the offering mainly provides exit liquidity for private investors and insiders. It points to large spending commitments and customer concentration: according to the leaked draft reported by Fortune, two customers supply about a quarter of revenue.
The leaked draft shows 2025 revenue of $4.6 billion and operating expenses of $13 billion, producing an operating loss of $8 billion-plus and a net loss of $42 billion. A non-cash charge from revaluing convertible instruments accounted for $34 billion of that net loss. Anthropic had $20.28 billion in cash at year end.
Recent Quarters Point the Other Way
Recent results contradict the model’s assumption of a sharp growth slowdown. Revenue was $4.73 billion in Q1 2026 and $11.5 billion in Q2, with operating profit for the second quarter in a row. Its Series H round in May 2026 raised $65 billion at a valuation of $965 billion, well above the firm’s low case.
The bearish case projects results years from now; current numbers show the opposite trend. The two views cover different time frames. The real question is how long growth holds up.
What Is Confirmed and What Is Still Missing
The prospectus figures come from a draft that leaked to Reuters, as reported by Fortune. We have not located a public registration statement on the SEC’s EDGAR system. Reports say the offering could raise $100 billion, but that figure is unconfirmed. Moomoo reported the valuation target as $2 trillion, according to Digital Today. We found no response from Anthropic to the research note or the leak.
What Would Settle the Debate
Three things would move this forward: a public filing, a price range, and a response from the company. For now, this is one firm’s model set against a leaked document. Investors following the deal can compare the firm’s growth assumptions with the audited numbers once a registration statement is public.
Contact [email protected] for any questions or corrections.
AJ spent 10 years writing about financial markets at The Motley Fool. His coverage centers on technology stocks and the broader macroeconomic trends, from interest rates to geopolitics, that shape where markets are headed next. AJ is drawn to the stories where big-picture economics and individual companies collide.