Warren Buffett’s Berkshire Now Owns 12% of This Homebuilder — Just as America’s Housing Market Deteriorates
Berkshire Hathaway just spent nearly $200 million buying into a homebuilder whose CEO admits conditions have deteriorated, margins are shrinking, and almost half of visitors can't qualify for a mortgage. What does Warren Buffett's successor see that the market clearly…

On Oct. 1 and 2, as mortgage rates rose toward a three-year high, Berkshire Hathaway (NYSE:BRK-A | BRK-A Price Prediction)(NYSE:BRK-B) bought roughly 2.42 million more shares of Lennar (NYSE:LEN) for about $193 million, according to a Form 4 filed with the Securities and Exchange Commission. Berkshire now holds about 29 million Class A and Class B shares, a stake of roughly 12% worth about $2.2 billion.
Days later, Freddie Mac put the average 30-year fixed mortgage rate at 7.40%, its highest since November 2023 and the seventh straight weekly increase. Lennar closed Friday at $76.68, down 33.23% over the past year, after Barron’s flagged its worst drop since 2024. Short-seller Hunterbrook has also published a critical report on Lennar’s transactions with Millrose Properties (NYSE:MRP).
Berkshire hasn’t explained the purchase. My read: it is buying a homebuilder engineered to survive a long slump, at a price that already assumes one (we sorted Berkshire’s holdings by valuation and pulled the cheapest dividend payers into a free report).

America’s Biggest Builder Is Bleeding Margin
Lennar’s third quarter was rough. Revenue fell 8.5% to $8.05 billion, and adjusted EPS of $1.23 missed the $1.30 consensus. Net income dropped 51.96%. Gross margin on home sales slipped to 15.8% from 17.5% a year earlier, even with incentives near 12% of price. Management cut full-year deliveries to 80,000 to 81,000 homes.

Stuart Miller, Lennar’s chief executive, said conditions had “deteriorated since our last earnings call.” The buyer’s math explains why. The 10-year Treasury yield hit 5.22% this week, and consumer sentiment came in at 51.7. In many Lennar markets, “almost 50% of our visitors cannot immediately qualify.”
Why Lennar Owns Almost None of Its Land
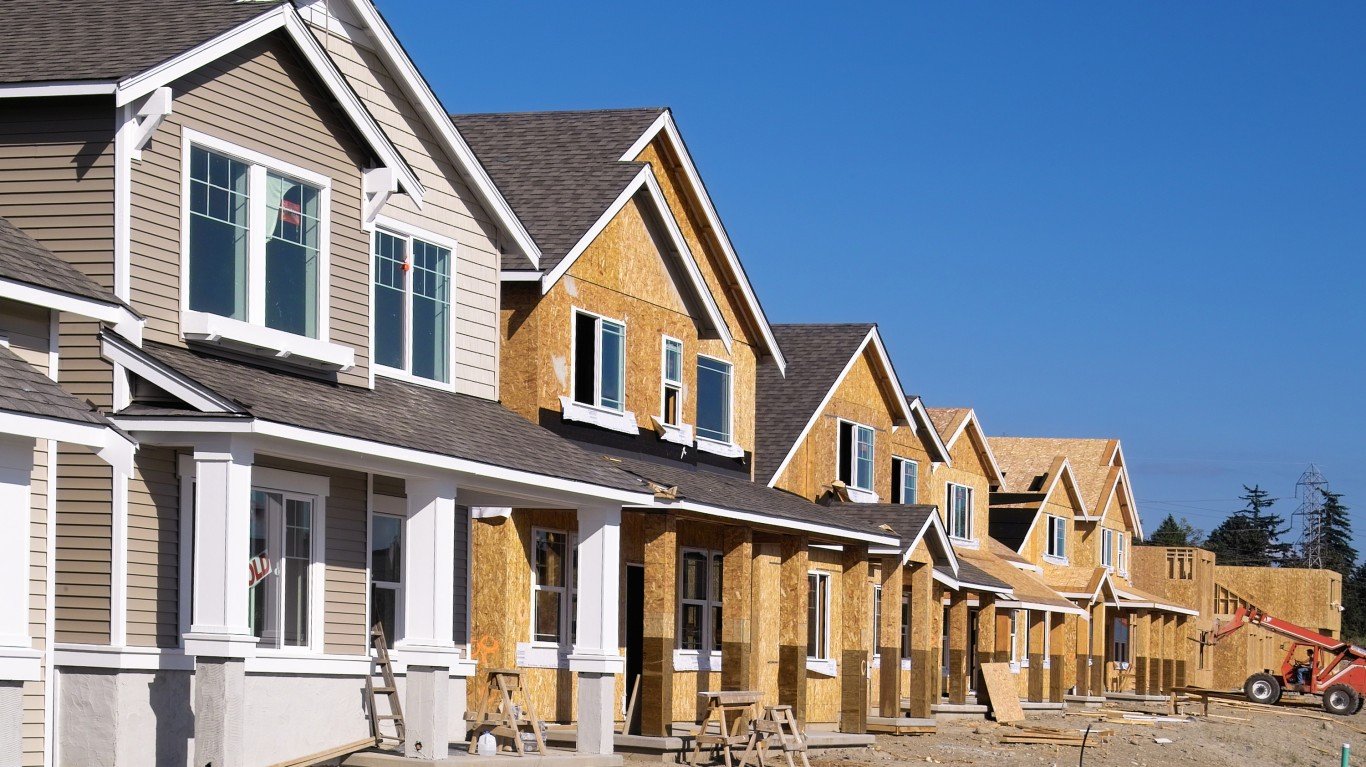
Land is what bankrupted builders in 2008. They bought lots at peak prices, then wrote them down when demand collapsed. Lennar owns roughly 2% of its homesites and controls about 476,000 through third parties, mainly land bankers such as Millrose. Homebuilding debt is just 16.6% of total capital.
That turns Lennar into something closer to a manufacturer. Build time fell to a record 116 days, and construction costs are down 14% since late 2023. Miller says the entire margin gap comes from land contracted under older, costlier assumptions. Accepting thin margins, he argued, “we are buying volume” and “buying time,” working through a land challenge that is “finite” and “visible.”
The weak spot is the same structure. Land-light still costs money: option fees are rising as land-bank holding periods stretch, and deposits and pre-acquisition costs have reached $7.3 billion. That is exactly where Hunterbrook aimed its criticism.
Signals That Will Test Berkshire’s Conviction
Lennar guided fourth-quarter gross margin to 15.5% to 16.0%, with 19,500 to 20,500 new orders. That outlook assumed mortgage rates near 6.8%. Rates are now well above that.
Keep an eye on three numbers in the next earnings report. If orders land inside guidance with rates above 7%, the volume machine is doing its job. If margin slips below 15.5%, it means rates are hitting faster than Lennar can work off old land. And if deposits keep rising while land-bank purchases are paused, the off-balance-sheet risk is getting bigger instead of contracting.

Berkshire’s money tells you a patient investor likes the design. It does not tell you the housing market has hit bottom. For the families who can’t qualify today, the trigger is the same one Lennar needs: lower rates.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.