AMD’s Recent Plus $600 Prices Look Like a Stepping Stone, Not a Barrier
AMD has surged 184% this year and now trades above $600, but the real question is whether its Helios chip ramp can grow into that valuation before the market loses patience with a 155x trailing multiple.

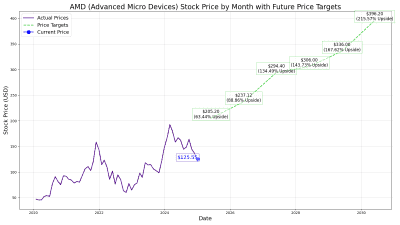
AMD (NASDAQ:AMD | AMD Price Prediction) trades at $608.10 after pushing past $600. The price is a waypoint for AMD, and investors should not read it as a ceiling, since the stock is up 183.95% year to date and earnings estimates keep rising behind it.
AMD designs CPUs, GPUs and AI accelerators. It competes with NVIDIA (NASDAQ:NVDA) in AI chips. Data Center revenue reached $6.72 billion last quarter, up 107% year over year and now 58% of total sales. The stock traded at $222.50 when AMD reported Q4 FY2025 and at $494.60 when it reported Q2 FY2026.
Gigawatt Deals Lock In a Multi-Year AI Runway
AMD guided Q3 revenue to about $13B +/- $300M, which works out to around 41% growth. Behind that guide sit multi-gigawatt customer commitments: OpenAI at 6 gigawatts, Meta Platforms (NASDAQ:META) at up to 6 GW and Anthropic at up to 2 GW. Management expects Data Center revenue to “more than double year-over-year in 2027”.
Analysts have raised their numbers to match. The 2027 EPS consensus is now $15.7219, up from $13.1993 90 days ago. That puts the stock near 39x 2027 earnings, with a PEG ratio of 0.626.
A 155x Trailing Multiple Punishes Any Stumble
On trailing numbers, AMD’s earnings multiple stands at 155 and its free cash flow multiple is 148. Free cash flow fell 9.89% in Q2 as capex rose 186.52%. Gaming revenue dropped 31%, and management expects PC demand to soften as memory costs rise.
Export controls already cost AMD an $800M MI308 inventory charge. NVIDIA still dominates AI accelerators, and the gigawatt deals are future installations that have not yet become booked revenue. With a beta of 2.454, the stock fell 4.07% last week while the S&P 500 rose 1.16%.
Helios Yields Will Set the Next Leg
Management called Helios “highly complex” and expects yields to improve over the first few quarters of the ramp. AI GPUs also carry gross margins “slightly below corporate average,” which puts the 56% margin guide at risk. Forecasts for 2027 revenue run from about $61 billion to $118 billion, and Q3 and Q4 results should help narrow that range.
Stock Outruns Wall Street and the S&P 500
The consensus target of $636.21 points to a 4.6% gain from $608.10. Targets have fell behind this rally. Among 55 analysts:
- Strong Buy: 5
- Buy: 39
- Hold: 11
- Sell: 0
AMD is up 183.95% year to date, against 14.17% for the S&P 500. Over one year it gained 161.11%, versus a 16% rise for the index. Shares sit 7.7% below the $658.52 high and well above the 50-day average of $528.92. The forward P/E is 40.
Can 2027 Earnings Catch Up to AMD’s $600 Price?
At $608.10, AMD’s valuation depends on executing the Helios ramp.
The path higher runs through the Helios ramp. Management said “Q4 is a step up” and “Q1 will be a further step up.” Anthropic’s first gigawatt is scheduled to start deploying in the first half of 2027. Each quarter that confirms the ramp should pull 2027 estimates higher and bring the multiple down.
Chair and CEO Lisa Su said, “We are still in the early stages of a multi-year AI adoption cycle.” AMD also expects to “significantly exceed our $20 annual EPS target.” If it gets there, the multiple on future earnings would contract (we reverse-engineered the traits the biggest chip winners shared before their runs in a free playbook here: The Next Nvidia Playbook).
The thesis breaks if Helios shipments slip, if gross margin falls below 56%, or if new export rules hit Instinct sales. Hyperscaler capex cuts would also force a review.
At 39x 2027 earnings, AMD’s run past $600 depends on Helios delivering that growth.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.