Prediction: AMD Could Be Closing the Gap in the AI Chip Race
AMD has doubled in months on the back of an AI accelerator story finally winning over hyperscalers, but a stretched valuation and lurking execution risks put the bull thesis on a razor's edge.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Our AMD (NASDAQ:AMD | AMD Price Prediction) call is one of the tougher ones we’ve made this quarter. The stock has done what few thought possible, doubling in months on the back of an AI accelerator story that is finally landing with hyperscalers.
The 24/7 Wall St. price target for AMD is $480.90 over the next 12 months, roughly 2.15% below the current quote of $485.51. That fair-value read pushes us to a hold rating with 90% confidence.
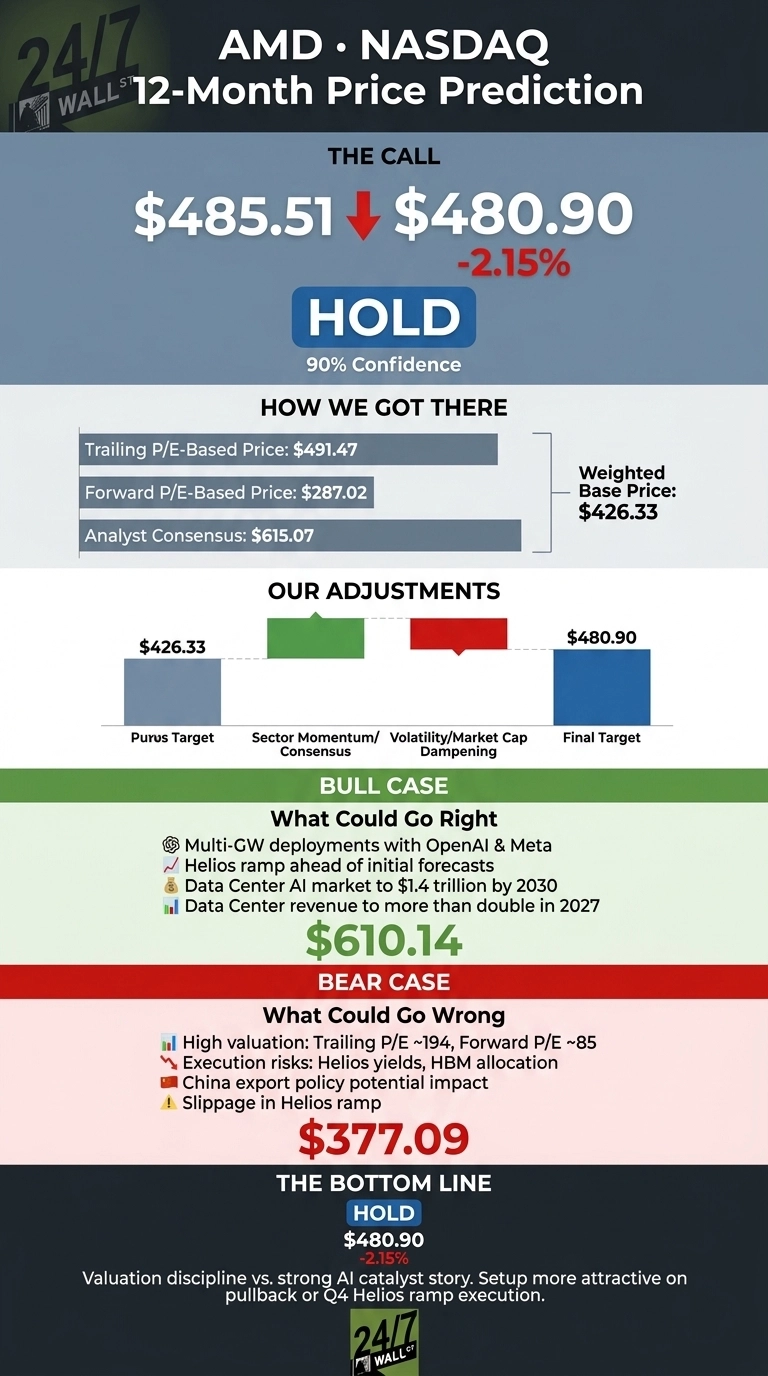

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $485.51 |
| 24/7 Wall St. Price Target | $480.90 |
| Upside/Downside | -2.15% |
| Recommendation | HOLD |
| Confidence Level | 90% |
Why We Could Be Wrong
Before diving in, we should note that our target sits just below where AMD trades today.
Bulls have real catalysts: the multi-generation gigawatt-scale deployments with OpenAI and Meta, the Anthropic commitment to deploy up to 2 GW of MI450 Series GPUs, and a Helios ramp management describes as tracking ahead of initial forecasts. Consider our target one datapoint among many. A full bull case appears below.
A Vertical Move Off the AI Accelerator Story
AMD is up 126.7% year to date and 211.88% over the trailing year, trading close to its 52-week high of $584.73.
Q2 FY26 was the catalyst: revenue of $11.54 billion, up 50.1%, with Data Center revenue of $6.72 billion, up 107%. Non-GAAP EPS of $1.66 beat, and Q3 guidance of approximately $13 billion implies another 41% growth quarter.

Bulls See a Path to $610
The bull thesis is clean. Lisa Su told investors AMD is in “the early stages of a multi-year AI adoption cycle” and sized the data center AI accelerator market at approximately $1.4 trillion by 2030.
Helios claims up to 30% more tokens per dollar than the competition, and AMD expects Data Center revenue to more than double year-over-year in 2027. Our bull case matches this trajectory at $610.14, roughly the Street’s target.

What Could Go Wrong
The bear case rests on valuation. AMD trades at a trailing P/E of 194 and an implied forward P/E near 85. Any slippage in Helios yields, HBM allocation, or China export policy could compress the multiple quickly.
Our bear scenario points to $377.09. Counterfactually, bulls will note that Q2 free cash flow fell 9.89% year over year only because capex jumped 186.52% to fund the very ramp powering the AI narrative.
How AMD Compares to Nvidia and Broadcom
NVIDIA (NASDAQ:NVDA) is the benchmark. Its Q2 FY27 Data Center revenue of $89.02 billion dwarfs AMD’s, yet NVDA trades at a P/E of just 44, versus AMD’s triple-digit multiple. NVDA is also up only 13.38% YTD, making AMD’s rally look extended on a relative basis.
Broadcom (NASDAQ:AVGO) is the custom-silicon counterpoint, with AI semiconductor revenue of $16.70 billion in Q3 FY26, up 221%. AVGO’s growth rate on a much larger AI base argues AMD’s target is not aggressive.
Intel (NASDAQ:INTC) is the turnaround comp. Its DCAI segment grew 59% in Q2 FY26, but the foundry still lost $2.1 billion. AMD’s execution premium looks earned. On balance, the peer group makes our $480.90 target look reasonable.
Hold for Now, With a Buyer’s Finger Ready
My final read: Hold, with a 24/7 Wall St. price target of $480.90 and 90% confidence. The scale tips on valuation discipline against a fundamentally strong story.
The setup would look more attractive if AMD pulls back into the low $400s or delivers a clean Helios ramp with margin expansion in Q4. The case weakens if Data Center growth decelerates below 60% or China export policy tightens further. (For readers hunting the next 100x chip story early, we reverse-engineered what past monster winners looked like before their runs in a free playbook here.)
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $478 |
| 2027 | $481 |
| 2028 | $503 |
| 2029 | $520 |
| 2030 | $534 |
These projections assume AMD executes on Helios and MI500. Significant upside or downside could result from OpenAI and Anthropic deployment velocity or a shift in China export policy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.