One Stock Could Benefit as AI Spending Moves Beyond Nvidia
Nvidia dominated the AI chip conversation for two years, but a quiet shift toward custom accelerators is reshaping where the real money flows, and one semiconductor company is booking orders deep into 2028 to prove it.


For two years, investors treated AI chips as a one-company story. Fresh results from Broadcom (NASDAQ:AVGO | AVGO Price Prediction) show the money now flowing into custom accelerators (XPUs) and the networking silicon that links them.
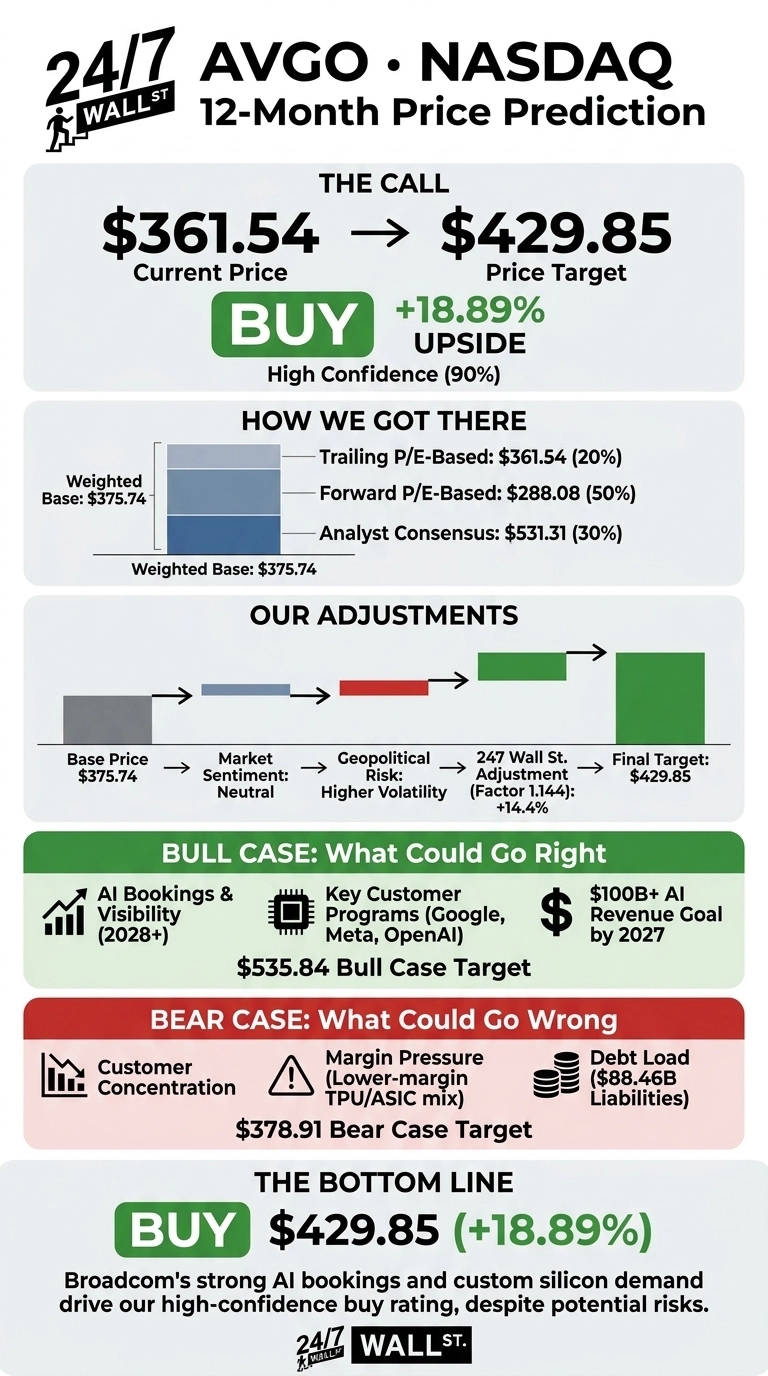
Broadcom last closed at $361.54. Our 24/7 Wall St. price target is $429.85 for the next 12 months, which implies 18.89% upside.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $361.54 |
| 24/7 Wall St. Price Target | $429.85 |
| Upside/Downside | 18.89% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our confidence is high. Analyst support is close to solid, and earnings are growing fast enough to justify a higher price. Shares changed hands at $356.88 at noon Monday, down 1.29%.
Record AI Revenue Runs Into an AI Credit Scare
The stock has gone nowhere lately even as the business has taken off. Shares are up 0.49% over the past week, down 1.88% over the past month and up only 3.68% year to date. That leaves them between a 52-week high of $493.28 and a low of $288.95.
Recent selling tracks concerns over AI-related borrowing, which MarketWatch described as a credit scare hitting Broadcom and Oracle.
Fundamentals are speeding up. Fiscal Q3 revenue came in at $29.59 billion, up 85.5% and ahead of the $29.44 billion consensus. Non-GAAP EPS of $3.32 beat estimates of $3.24, the 9th straight beat.
AI semiconductor revenue rose 221% to $16.70 billion. For Q4, management guided to $21.7 billion in AI revenue on total revenue of about $34.8 billion.
Why Bulls See $535 and Beyond
Order flow is running far ahead of shipments. On the fiscal Q2 call, management reported AI bookings of over $30 billion and said “our visibility runs all the way to 2028 right now.” Broadcom repeated AI revenue of in excess of $100 billion for fiscal 2027.
That rests on Google TPU programs, an OpenAI deal for 10 gigawatts by 2029 and a Meta Platforms (NASDAQ:META) commitment of 3 gigawatts through the end of 2028. Wall Street’s consensus target is $531.31, from 7 Strong Buy, 40 Buy and 3 Hold ratings, with no Sells. The bull case reaches $535.84.

What Could Derail the Rally
Customer concentration is the biggest risk. The chief executive said most demand “comes from those few large frontier model developers.” As lower-margin TPU and ASIC sales grow as a share of revenue, semiconductor margins could come under pressure. Management responded that AI networking carries “very rich margins.”
Debt from the VMware deal is another concern, with total liabilities at $88.46 billion. Cash generation offsets much of that worry. Quarterly free cash flow came to $13.66 billion, or 46% of revenue. Our bear case of $378.91 still sits above Friday’s close.

Broadcom Trades Cheaper Than NVIDIA and Marvell
The merchant GPU leader that hyperscalers are designing custom chips to complement is NVIDIA (NASDAQ:NVDA). Shares trade at 25x forward earnings on quarterly revenue growth of 105.9%.
Marvell Technology (NASDAQ:MRVL) competes directly in custom ASICs and optical interconnects. The stock trades at 62x forward earnings while growing revenue 36.5%.
| Company | Forward P/E | Quarterly Revenue Growth (YoY) |
|---|---|---|
| Broadcom | 19x | 85.5% |
| NVIDIA | 25x | 105.9% |
| Marvell | 62x | 36.5% |
At our target, Broadcom would trade at about 23x forward EPS of $18.373, which is still below both peers. Against this group, the 24/7 Wall St. price target looks conservative.
Why Our Model Rates Broadcom a Buy
Our 24/7 Wall St. price target of $429.85 comes with a buy rating and 90% confidence. Booked AI demand reaching into 2028, coupled with a discount to its peers, is what tips the balance (we reverse-engineered what the biggest tech winners looked like early and turned it into a free playbook here: The Next Nvidia Playbook).
Keep an eye on whether Q4 AI revenue hits the $21.7 billion guide. A key risk to monitor is whether the credit worries lead hyperscalers to delay orders.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $381.83 |
| 2027 | $429.85 |
| 2028 | $485.80 |
| 2029 | $534.43 |
| 2030 | $567.74 |
These projections assume Broadcom keeps executing on its XPU and networking roadmap. Reaching the $100 billion AI goal could drove results higher, while losing a major customer could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.