AMD’s Price Action Around $600 is Telling Investors Something Specific
AMD cleared $600 twice and failed twice, and that pattern is telling investors something the revenue growth numbers alone cannot explain. Two quarters of upcoming shipment data will determine whether the 2027 bull case survives or collapses.

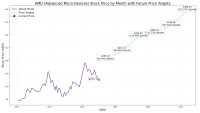
Advanced Micro Devices (NASDAQ:AMD | AMD Price Prediction) trades at $562.23. The stock’s failure to stay above $600 shows the market has stopped paying for AI potential and is waiting for proof.
AMD sells server CPUs, AI accelerators, PC chips and embedded processors. Data Center now accounts for 58% of revenue. Shares are up 162.53% year to date and reached a 52-week high of $658.52. In the past week they fell 9.42% from $620.68 as a global tech rout on AI funding worries spread across chip stocks.
Gigawatt Contracts Support the Bull Case After the Pullback
Second-quarter revenue rose 50.1% to $11.54 billion. Data Center sales jumped 107% to $6.72 billion. Guidance calls for about $13 billion in third-quarter revenue. AMD also has anchor deals for up to 2 gigawatts with Anthropic, 6 gigawatts with OpenAI and up to 6 gigawatts with Meta Platforms (NASDAQ:META). Management sized its revenue per gigawatt at “double digit billions”.
On a forward basis the valuation looks reasonable. The stock trades at a forward P/E of 40 with a PEG of 0.626. The 2027 EPS consensus has rose to $15.7219 from $13.2815 90 days ago, which puts the stock at roughly 36x next year’s earnings. CEO Lisa Su expects to “significantly exceed our $20 annual EPS target”.
A 154x Trailing Multiple Has No Cushion for AI Funding Doubts
AMD trades at 154 times trailing earnings and 22.56 times sales. Free cash flow fell 9.9% last quarter, while capital spending rose 186.52%. Gaming revenue dropped 31%. Management also expects data-center AI gross margins to run slightly below the corporate average.
The bigger threat is concentration. Most of the 2027 story rests on a small group of AI labs and hyperscalers. Headlines about cracks emerging in the AI trade go straight at that funding (we profiled seven suppliers supporting the AI expansion, from power to cooling, in a free report you can grab here). With a beta of 2.454, AMD is likely to fall harder than the market when mood sours.
Helios Shipments Will Settle What $600 Could Not
Revenue is growing and margins are expanding, which supports the case for upside. The valuation and the funding questions around AMD’s customers moderate it. The third-quarter guide implies growth of 41%, down from 50.1%. That gives bears a slowing story until Helios volumes show up in the numbers. Su said “Q4 is a step up and then Q1 will be a further step up.”
Analysts See Upside, but Momentum Has Stalled
The average price target of $636.21 implies about 13.2% upside from $562.23. Targets are estimates rather than guarantees. All 55 analysts covering the stock split as follows:
- Strong Buy: 5
- Buy: 39
- Hold: 11
- Sell: 0
Over one year AMD gained 135.64%, while the S&P 500 rose 16.03%. Last week AMD lost 9.42% as the index slipped just 0.28%. The stock still trades above its 50-day average of $534.75.
Helios Revenue Is the Catalyst AMD Investors Need to Track Now
At $562.23, AMD sits between its bull and bear cases.
The move around $600 shows buyers will pay for AMD’s AI growth, but only up to a point while the funding behind it is in question. The third-quarter report needs to beat the $13 billion guide and confirm that Helios shipments have started. Gross margin also needs to hold near 56%.
A fourth-quarter guide that shows the promised Helios step-up would support the bullish argument. Any delay from an anchor customer tied to financing would strengthen the bear case. Further drops remain possible in a volatile market, and the stock remains 14.6% below its high.
The next two quarters of Helios revenue will show whether the 2027 estimates are realistic, and they are the key data point for investors to keep an eye on.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.