Nvidia Stock Could Be Headed for a Significant Revaluation
Jensen Huang says compute is now revenue, and NVIDIA's latest numbers back him up. But whether Wall Street's already-aggressive targets actually undershoot where this stock is headed depends on a few catalysts that could change the math entirely.

NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) chief executive Jensen Huang sums up the moment in one line: “AI has reached its inflection point. It’s doing useful work. Its tokens are productive and profitable. Now, compute is revenue.”
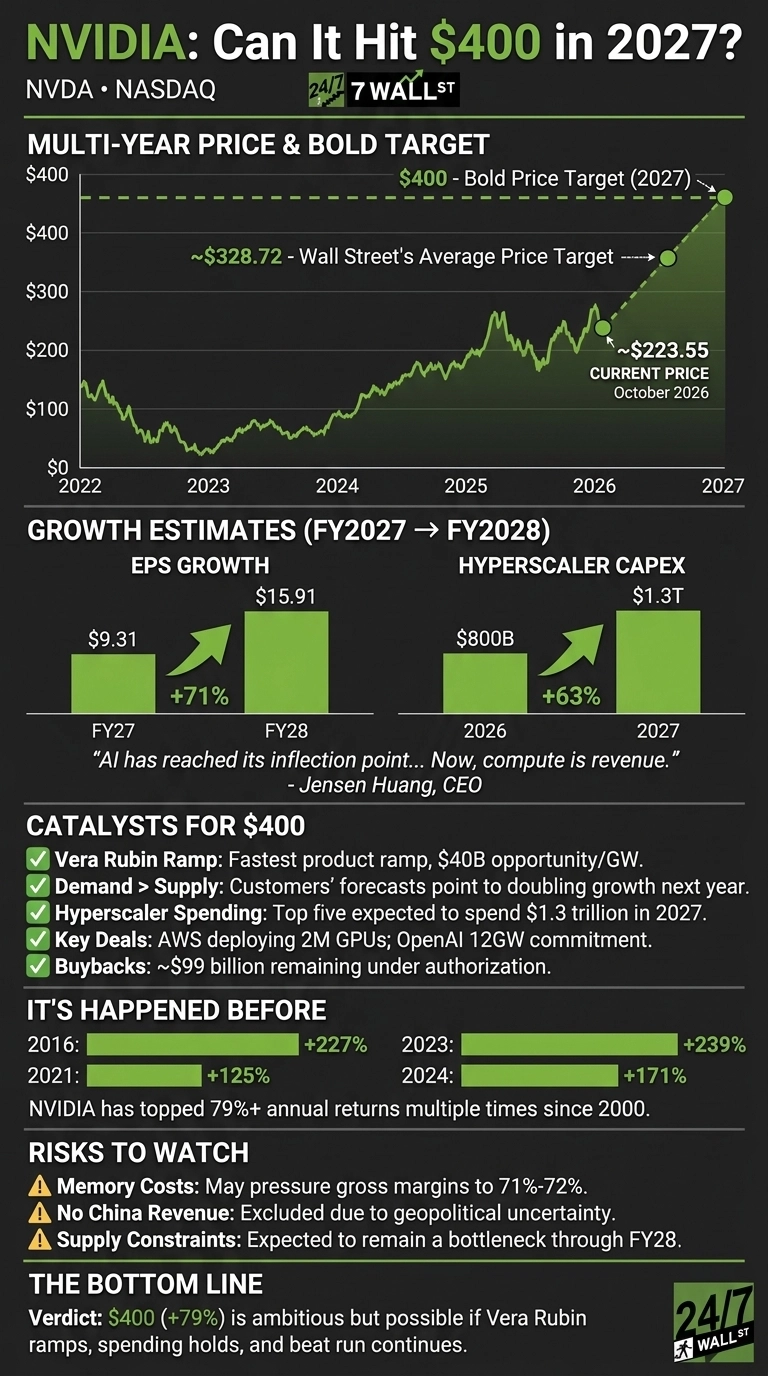
The latest quarter at NVIDIA supports him. Second-quarter fiscal 2027 revenue reached $96.22 billion, up 105.8% year over year, and Data Center sales rose 117% to $89.02 billion.
Shares are up 20.15% year to date at $223.55 and have gained 932.51% over five years. Earnings are growing faster than the stock price, though, which leaves room for a revaluation. Here’s how NVIDIA could hit $400 in 2027.

Wall Street Already Sees 47% Upside
The average analyst price target is $328.72, which means about 47% upside. Coverage has 10 Strong Buy and 49 Buy ratings against just one Sell.

Estimates keep rising. Consensus EPS for fiscal 2028 stands at $15.9146, compared with $12.7102 90 days ago. Over the past 30 days, analysts made 46 upward revisions and zero downward.
That works out to about 71% growth from the $9.3124 expected this fiscal year. NVIDIA has also exceeded EPS estimates for 6 consecutive quarters, most recently posting $2.22 against $2.0887 expected. A run like that suggests actual results could come in above forecasts.
Here’s the Math Behind $400 Per Share
At today’s price, NVIDIA trades at 14x fiscal 2028 estimates. The S&P 500 trades at roughly 21-23x forward earnings, so NVIDIA is cheaper than the average stock despite growing much faster.
At $400, shares would trade at about 25x forward earnings. That is a modest premium for a business expected to grow EPS by roughly 71%.
What Could Push NVIDIA to $400?
- Vera Rubin: Purchase orders have arrived from “every major hyperscaler, AI cloud, and system OEM,” and management expects it to be “the fastest product ramp in NVIDIA’s history.” Each gigawatt of Vera Rubin represents a $40 billion revenue opportunity, compared with $25 billion for Blackwell.
- Demand above supply: Management guides to roughly 70% revenue growth in fiscal 2028 and says “customers’ forecasts point to our growth doubling next year.”
- Hyperscaler spending: Capital spending by the top five hyperscalers is expected to rise from nearly $800 billion in 2026 to $1.3 trillion in 2027.
- Key deals: AWS is deploying an additional 2 million GPUs, and OpenAI’s commitments total about 12 gigawatts of NVIDIA computing power.
- Buybacks: NVIDIA returned $26 billion to shareholders last quarter and has about $99 billion left under its buyback authorization.

There are hurdles. Memory costs could push gross margin down to a 71% to 72% low, the outlook includes no China data center revenue, and supply stays tight through fiscal 2028.
NVIDIA Has Topped 79% in 10 Years Since 2000
Hitting $400 requires a gain of about 79%. Since 2000, NVIDIA has gained more than that in 10 calendar years.
Shares rose 239% in 2023, 171% in 2024, 227% in 2016 and 125% in 2021. At a market cap of about $5.395 trillion, repeating those gains is harder, but the record shows the stock can move this much.
$400 Is a Stretch, but Here’s Why It’s Possible
A move to $400 would take a 79% gain in 2027. Analysts already expect 47% upside, estimates are rising quickly, and the stock trades below the market multiple.
If Vera Rubin ramps as planned, hyperscaler spending holds up and the beat run continues, a 25x multiple is a reasonable outcome. Such returns are rare, yet this is how NVIDIA could deliver outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.