Home Sales Contracts Just Fell to a Record Low as Mortgage Rates Hit 7.4%
Pending home sales just cratered to a record low, yet homebuilder stocks surged the same day the data dropped. What traders are betting on reveals a split between what the housing market is showing and where some believe it is…

Contracts to buy existing homes fell 7.3% in September. That drop pushed the pending home sales index to 66.0, its lowest level since the series began in 2001, while economists expected a fall of only 0.5%.
Homebuilder stocks rose anyway on Oct. 20, 2026, the day the data came out. The iShares U.S. Home Construction ETF (BATS:ITB) closed at $87.32, up 2.80%. Lennar (NYSE:LEN | LEN Price Prediction) gained 3.66% to $78.65, and D.R. Horton (NYSE:DHI) rose 3.59% to $140.17.
The gap between the data and the stocks shows how much pressure builders face. The 30-year fixed mortgage averaged 7.40% for the week of Oct. 15, compared with 6.27% a year earlier, and builders are cutting prices to keep homes selling.
Contracts Fell in Every Region
The West had the steepest drop, down 9.2% for the month and 15.0% from a year earlier. The South fell 8.2%, the Midwest 6.5% and the Northeast 4.2%.
Rates climbed quickly during the month. One lender survey showed the 30-year average going from 6.8% to nearly 7.5% as Treasury yields rose and the war with Iran added to inflation. The 10-year Treasury yield was at 5.15% on Oct. 19.
National Association of Realtors chief economist Lawrence Yun said, “Market conditions weakened in September due to fast-rising mortgage rates.”
Builders Are Giving Up Margin on Every Sale
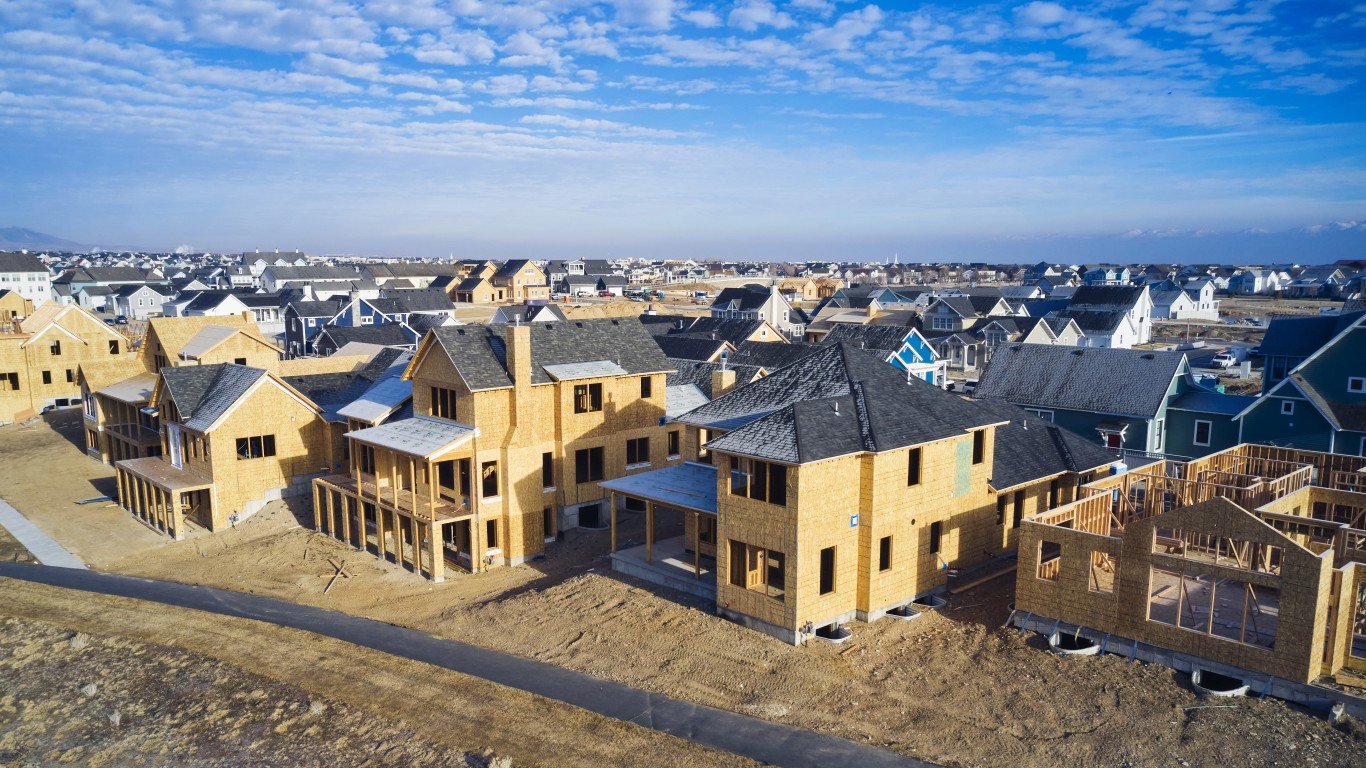
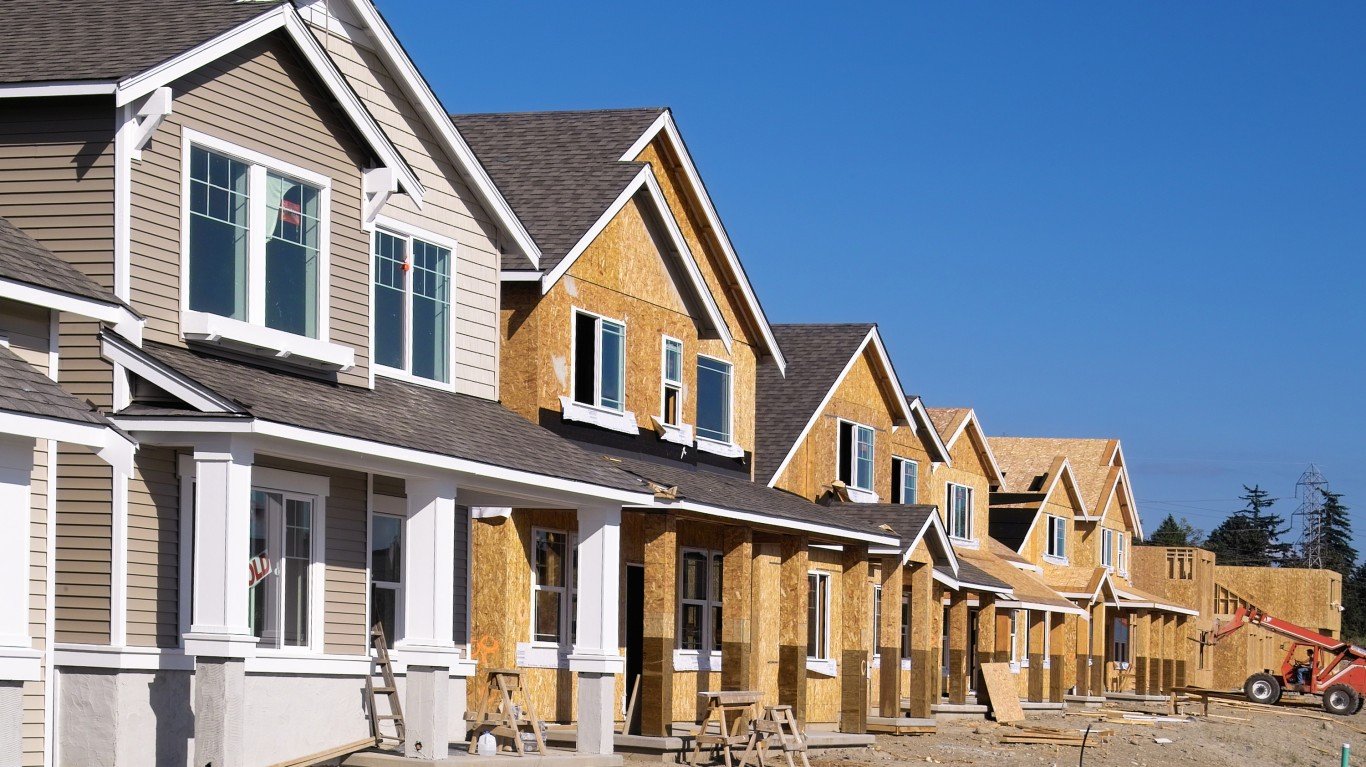
Housing starts fell 5.2% in September. The builder sentiment index dropped 3 points to 29, its lowest reading since June 2012, and 43% of builders cut prices by an average of 6%.
Land and construction costs are already paid by the time a house is sold, so every price cut or rate buydown comes straight out of gross margin. Lennar’s home sales gross margin was 15.8%, down from 17.5% a year earlier, with incentives at about 12.0%. The company also cut its full-year delivery target to 80,000 to 81,000 homes.


Possible Reasons for the Rally
No one has explained the rally. One likely reason is that much of the bad news was already priced in: ITB is down 14.79% over the past year, and Lennar is down 21.78% this year after reaching a 52-week high of $133.76.
Some traders may also think rates are close to peaking. Yun said rates “could be topping out”, but that is a forecast, and one mortgage data firm expects the rate to reach 7.8% within three months.
Builders also have a tool that people selling their own homes lack. As of June 30, D.R. Horton’s backlog buyers using its mortgage arm had a rate of 4.9%, which the company paid for.
D.R. Horton Faces the Next Test
D.R. Horton is trading near its 52-week low of $130.40, and its quarterly results are due soon. Its cancellation rate rose to 20% from 17%, but its 20.7% gross margin gives it more room to pay for incentives than Lennar.


What the Housing Data Means for ITB and Its Biggest Builders
The data points to continued pressure on ITB. A one-day rise on the weakest contract reading in the series’ history looks like relief, while the drivers of builder margins (rates, price cuts, and incentives) are still moving in the wrong direction.
ITB also holds the weaker-margin builders along with the stronger ones, and it charges an expense ratio of 0.37%. D.R. Horton looks better positioned than most of the group, because it has the widest margin buffer and planned buybacks of about $2.5 billion this fiscal year.
You can check this view yourself at the next pending home sales report on Wednesday, Nov. 18 at 10 a.m. ET. If the index stays near 66.0 and D.R. Horton closes below $130.40, the Oct. 20 rally will likely look early.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.