Can EPD’s $6.5B Growth Engine Defy a $34B Debt Cloud on Oct. 29?
Enterprise Products Partners (NYSE:EPD | EPD Price Prediction) reports third-quarter results on Oct. 29. Units have gained 21% year to date. The report should demonstrate that a $6.5 billion project backlog can exist alongside with about $34 billion of debt.…

Enterprise Products Partners (NYSE:EPD | EPD Price Prediction) reports third-quarter results on Oct. 29. Units have gained 21% year to date. The report should demonstrate that a $6.5 billion project backlog can exist alongside with about $34 billion of debt.

A Record Quarter Fueled Partly by a Geopolitical Windfall
Last quarter brought EPS of $0.84 and revenue of $18.27B, up 60.8% year over year. Adjusted EBITDA hit a record $2.83B, and distributable cash flow covered the distribution 1.9x. Marine terminals handled 2.8 MMBPD, up 33%.
Middle East disruption caused much of that strength. Management tied about $200 million to April and May export demand and said those cash differentials have largely normalized. Marine volumes returned to normal by June and July.
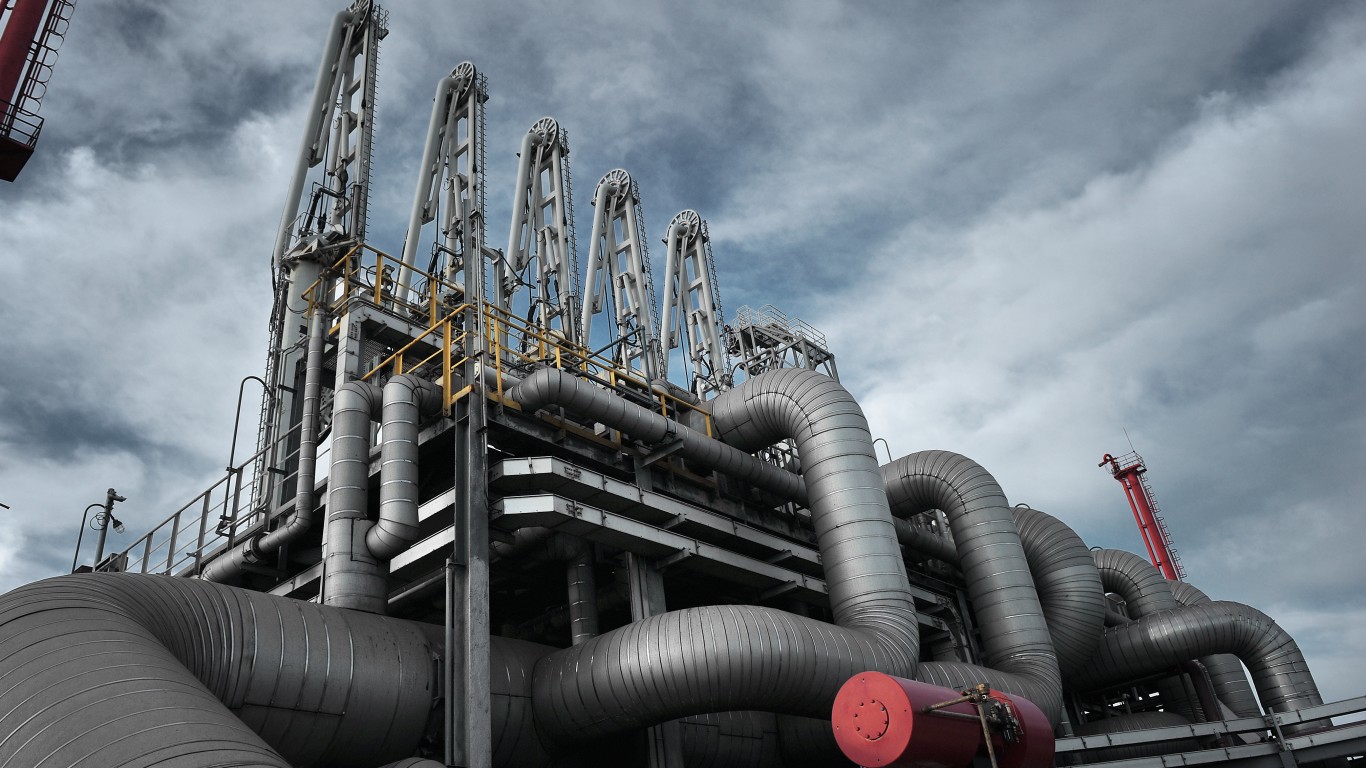
Meanwhile, the backlog grew from $5.3B to $6.5B with two new Permian plants and a new Mont Belvieu fractionator. Units sit at $37.08, down 1.3% over the past month.
Consensus Points to Double-Digit Growth
| Metric | Estimate | Prior-Year Actual | Implied Growth |
|---|---|---|---|
| Q3 2026 EPS | $0.7344 | $0.61 | 20.4% |
| Q3 2026 Revenue | $14.98B | $12.02B | 24.6% |
| FY2026 EPS | $3.065 | $2.66 | 15.2% |
| FY2026 Revenue | $62.80B | $52.60B | 19.4% |

Permian Throughput and Capex Discipline Will Set the Tone
Volumes come first for me. Permian inlet volumes rose 14% to 4.3 Bcf/d last quarter, and basin NGL pipelines run at 86% of capacity. Management noted about 2 Bcf/d of cutback gas that could return. The EIA expects Permian gas output to grow 6% this year on rising gas-to-oil ratios.
Next, the LPG export expansion is due by year-end and is about 90% signed. I’ll be watching for timing confirmation, since new industry export capacity could pressure terminal fees over the next 12 to 18 months.
The balance sheet matters just as much. Total debt was $34.0B at June 30 versus $34.9B at year-end 2025, with net leverage at the 3.0 target. About 97% of that debt is fixed rate at a 4.7% average cost, which cushions rate pressure. 2026 growth capex guidance stands at $2.9-$3.4B.

You should also look at capital returns. Buybacks totaled $159M in Q2, using 34% of the $5.0B authorization, alongside a $0.56 quarterly distribution. Co-CEO Jim Teague announced his retirement on the July 30 call, so leadership tone carries extra weight.
Free Cash Flow Promises Face a $3 Billion Spending Reality
A year ago, management called 2026 a “free cash flow inflection point.” Since then, growth capex rose by over $700 million, and co-CEO Randy Fowler said $3 billion might be the new level. Discretionary free cash flow could still approach the $1 billion area. If third-quarter EBITDA holds up without the spring windfall while debt remains flat, the volume-driven growth story behind 27 straight years of distribution increases looks durable heading into 2027.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.