McDonald’s Just Became a Dividend King. Is It Still a Buy for Retirement?
Fifty years of dividend hikes sound bulletproof, but McDonald's U.S. traffic is sliding while debt costs climb. The cash coverage numbers and one balance sheet cushion reveal how much room retirees really have.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

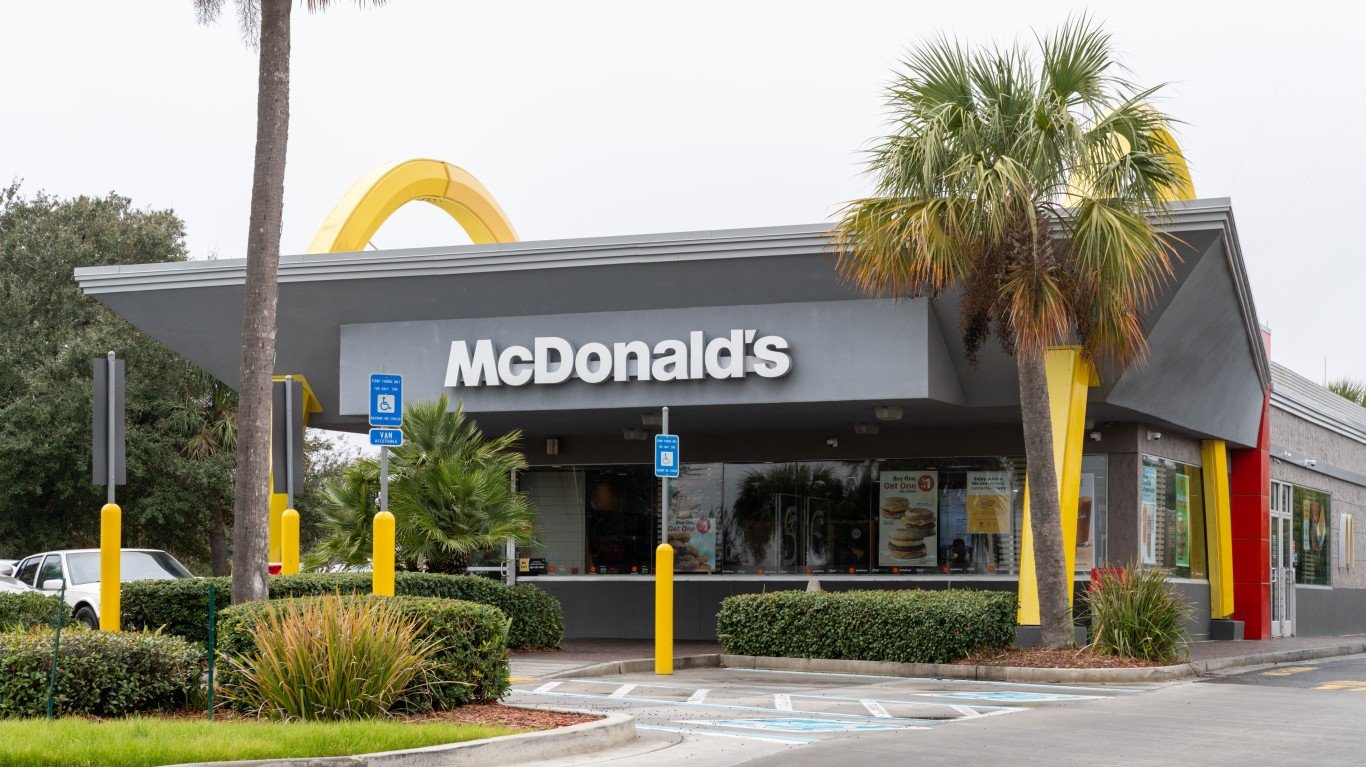
Income investors just got a new data point. McDonald’s (NYSE:MCD | MCD Price Prediction) raised its quarterly dividend 4% to $1.93 per share, payable December 15, 2026. A September 17, 2026, company release marked 50 consecutive years of dividend increases, putting McDonald’s among the Dividend Kings. At $276.47, the stock yields 2.61%. Retirees need to know whether a softer U.S. business can keep paying for that run.

Franchise Model Turns Rent Into Dividend Checks
McDonald’s makes most of its money from franchisees, who pay it rent and royalties. Running few restaurants itself helps the company post a 46.1% operating margin. It is also driving toward 98% of its global restaurant portfolio franchised by 2028. On the third-quarter call, CFO Ian Borden explained the trade-off:
“Obviously, as you know, in the model, that has an impact on revenue, which is one of the reasons why our revenue was a bit down in Q3, because we moved that 100% revenue to obviously a franchised contribution of revenue.”
The company books less revenue under this setup, but the cash it does collect is steadier and carries higher margins. That is the kind of cash a dividend needs.
Coverage Numbers Every Retiree Should See
In 2025, McDonald’s produced $7.19B in free cash flow and paid out $5.115B in dividends. The dividends represent roughly 71% of free cash flow. Over the first three quarters of 2026, operating cash flow minus capex came to about $5.85 billion, while dividends amounted to $3.95 billion. The forward annual dividend of $7.72 is about 60% of adjusted EPS for the trailing four quarters. At the new rate, the yearly dividend bill comes to roughly $5.46 billion.
Capex is also tracking below plan. Borden said:
“We now expect 2026 capital expenditures of about $3.7 billion, which is at the low end of our previously guided range of $3.7 to $3.9 billion.”
Balance Sheet Leverage Deserves Attention
Net debt is 3.70 times EBITDA, and interest coverage is 7.83x. Interest expense is guided up 4% to 6% for 2026. Shareholders’ equity showed a $1.79B deficit at the end of 2025, mostly because of buybacks. Those buybacks act as a cushion for income investors. McDonald’s spent $2.0B on repurchases in 2025, and that money could be redirected to the dividend before the payout itself came under pressure.

How Yum! Brands and Starbucks Stack Up
Yum! Brands (NYSE:YUM) raised its quarterly payout to $0.75 from $0.71, an increase of about 5.6%. It also carries -$6.165 billion in shareholders’ equity and lists high debt as a risk. Starbucks (NASDAQ:SBUX) raised its dividend just 1.6% to $0.63. It yields 2.35% and trades at 48 times earnings, compared with 23 for McDonald’s. Next to these two, McDonald’s offers the longest run and the cheapest earnings multiple.
Traffic Is the Risk to Track
U.S. comparable sales slipped 0.2% on negative guest counts. Comps also fell in France and China. Management expects mid-single-digit food and paper inflation in 2027. CEO Chris Kempczinski struck a hopeful tone on the U.S. business:
“In the U.S., we’re encouraged by improvement as the quarter progressed following our intervention on value.”
A new U.S. value program is set to roll out nationally in early 2027. Investors seem to agree with Kempczinski. The stock is still down 7.75% year to date but has climbed 19.77% over the past month.
Verdict: McDonald’s Is Still a Retirement Staple
Yes. Free cash flow covers the dividend with room to spare, the payout ratio sits near 60% of earnings, and the business runs on franchise rent. That combination is why McDonald’s has raised its dividend for five decades. Weak traffic and rising leverage could slow future increases, but neither puts the payout itself at risk. For investors searching for reliable income, McDonald’s dividend record and cash coverage remain key data points.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.