This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
This article is updated throughout the trading day. Check back for more.
Applied Materials (NASDAQ: AMAT | AMAT Price Prediction) is expected to report fiscal fourth-quarter 2026 results today at around 4:00 PM ET. The chip equipment leader guided to its strongest growth of the year, and its stock has been sliding since August. That makes its 2027 commentary the key number tonight.
Record Quarters Meet a Retreating Stock
Fiscal Q3 revenue reached $9.115B, up 24.83% year over year. Non-GAAP EPS of $3.50 exceeded estimates by 3.11%. Semiconductor Systems non-GAAP operating margin expanded to 38.0% from 33.2%, and free cash flow came in at $2.330B.
Shares stood at $552.70 when the company filed its Q3 report and now trade near $391.86, though they remain up 53.02% year to date. On the Q3 call, CEO Gary Dickerson raised the calendar 2026 Semiconductor Systems outlook and said: “Based on the increased demand visibility we are receiving from our customers, we expect another strong growth year for Applied Materials in 2027.”
AMAT’s Consensus Estimates Sit Just Above Guidance
| Metric |
Q4 FY2026 Estimate |
YoY Change |
FY2026 Estimate |
FY2027 Estimate |
| Revenue |
$10.30B |
+51.46% |
$34.25B |
$46.38B |
| EPS (Normalized) |
$4.0558 |
+86.90% |
$12.7938 |
$18.5565 |
Consensus sits slightly above the midpoint of company guidance of $4.02 +/- $0.20. The Q4 EPS estimate rose from 3.6446 90 days ago but had two down revisions over the last 30 days. FY2027 estimates collected five up revisions in that window, so the outlook for next year carries more weight than tonight’s quarter.
What to Watch Tonight: DRAM, Packaging and Clean-Room Limits
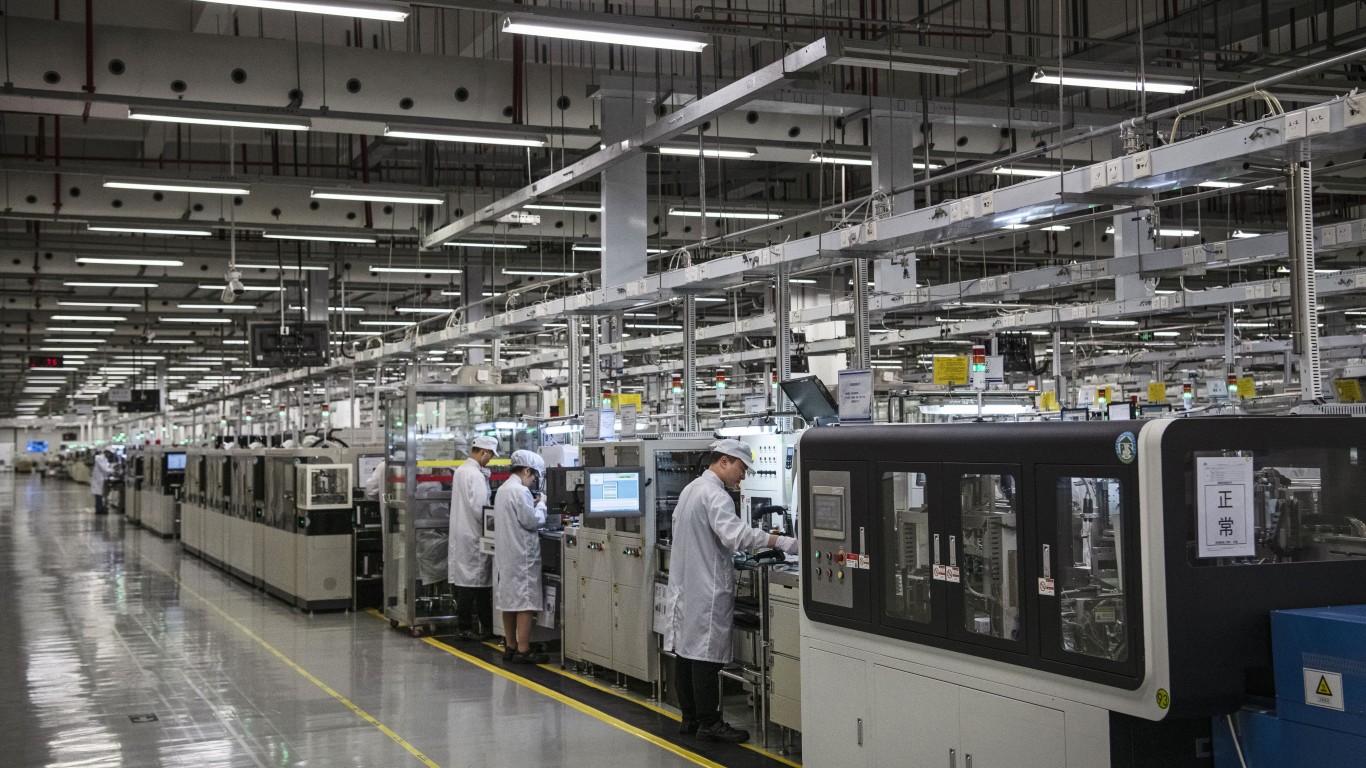
My first focus tonight will be on Semiconductor Systems. Management guided that segment to around $7.9 billion, up 62%, after Q3 DRAM revenue grew 52% to a record.
Packaging is the second catalyst. Applied estimated packaging revenue growth above 70% in calendar 2026, with process diagnostics and control exceeding 50%.
Margins deserve close attention. The Q4 gross margin guide is about 50.4%, with operating expenses near $1.58 billion. Display-heavy Other revenue of roughly $510 million weakens the mix, and that segment’s operating loss widened to $118M from $4M in Q3.
Capacity will be important for framing 2027. CEO Gary Dickerson warned that “clean room availability at a high level will determine what we can ship next year.” China is also worth watching after its share fell to 28% from 35% amid export controls.
AMAT’s Earnings History Shows Muted Follow-Through
| Quarter |
EPS Surprise |
Earnings-Day Move |
1-Day Move |
7-Day Move |
30-Day Move |
| Q3 FY2026 |
+3.11% |
-5.12% |
+5.55% |
-2.93% |
-18.1% |
| Q2 FY2026 |
+6.56% |
-0.89% |
-5.28% |
-1.02% |
+35.8% |
| Q1 FY2026 |
+7.84% |
+8.08% |
+1.19% |
+5.25% |
-1.53% |
| Q4 FY2025 |
+2.36% |
+1.25% |
+1.19% |
-0.88% |
+9.85% |
On average, shares moved 0.105% seven days after earnings over the past year.
Contact [email protected] for any questions or corrections.