2 Defense Dividend Stocks Backed by Years of Pentagon Contracts

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
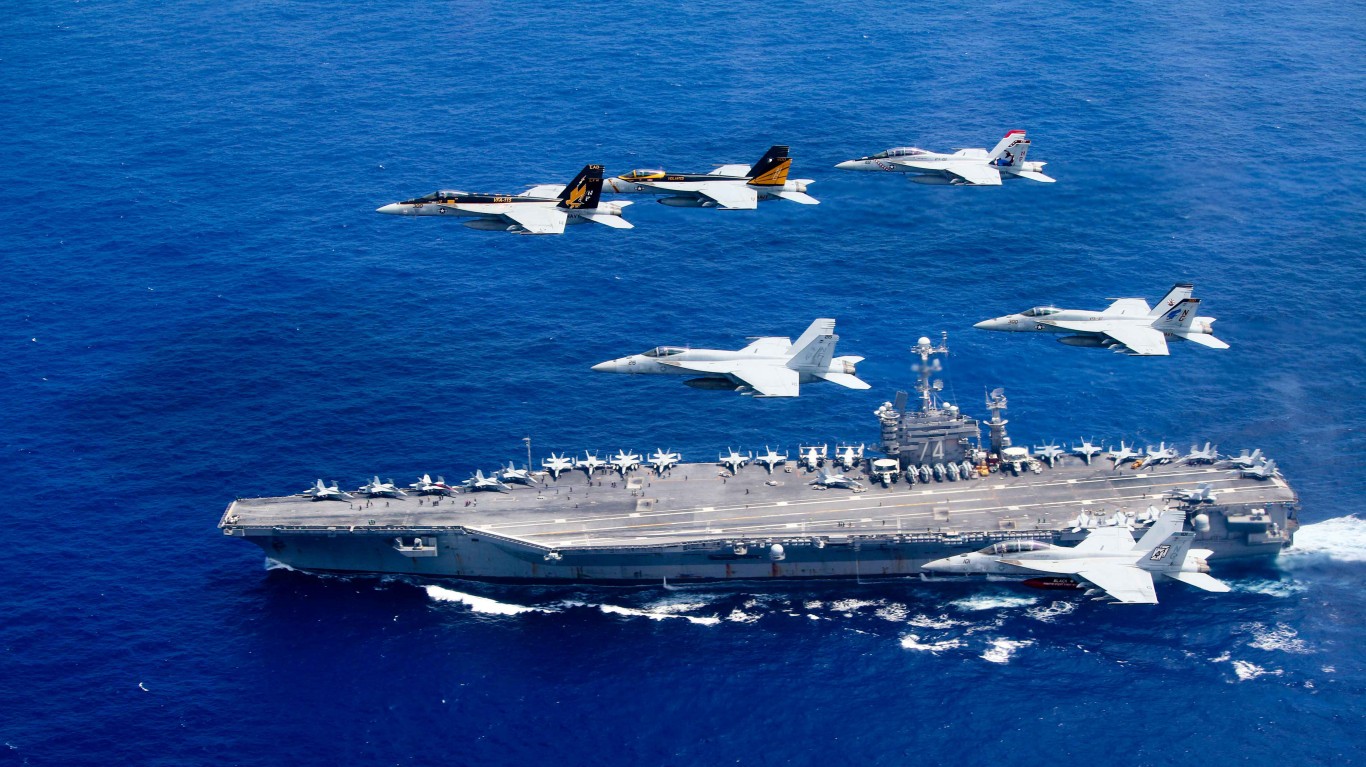
Defense contractors answer to customers that plan years. Pentagon programs run on multi-year contracts, order books stretch for years, and the budgets behind them don’t rise and fall with consumer spending or mortgage rates. That steady flow of cash is what pays a growing dividend, and two NYSE-listed primes show it right now: L3Harris Technologies (NYSE:LHX | LHX Price Prediction) and Huntington Ingalls Industries (NYSE:HII). Both yields are modest, so the case rests on durable payouts that keep rising. Huntington Ingalls says approximately 90% of expected shipbuilding revenue through 2030[1] is already under contract, and L3Harris just posted a record backlog of its own.
L3Harris Technologies
L3Harris makes the electronics, communications, and propulsion hardware the military runs on. It reports three segments: Space & Mission Systems, Communication & Spectrum Dominance, and Missile Solutions. The products range from tactical radios and the Navy’s Next Gen Jammer electronic warfare system to the solid rocket motors inside PAC-3 and THAAD interceptors. Shares trade at $262.76, down 9.39% year to date, and recent headlines tied a pullback to consequences from the FAA’s nationwide ground stop after a travel meltdown. The stock yields 1.82% on a trailing dividend of $4.95 per share, with the next $1.25 quarterly payment scheduled for December 18 to holders of record on December 4.

Dividend Safety Check
Earnings cover the payout comfortably. Against trailing diluted EPS of $10.74, the dividend uses about 46% of profits, and management’s raised full-year GAAP EPS guidance of $12.25 to $12.35[2] points to more room ahead. Cash coverage looks even better. At the trailing rate, the dividend costs roughly $922 million a year, about 31% of the company’s free cash flow guidance of approximately $3.0 billion[2]. Third-quarter free cash flow alone came in at $1.260 billion[2], up 195.1% from a year earlier.
The balance sheet is getting cleaner. L3Harris carries $11.0B of total debt, but net debt leverage has fallen from 4.3x to approximately 1.9x[3], and the CFO said the company plans to repay $800 million of debt in the fourth quarter. Management places the dividend second among capital priorities, right after investing in the business. As the CFO put it on the call: “Second, we remain committed to our dividend.”[3]
History backs that up. Dividend records show payments going back to 1999, and the quarterly rate rose every year from 2021 through 2026, from $1.02 to the current $1.25. The latest increase, from $1.20, worked out to roughly 4.2%.
Bull Case for Income Investors
The order book is the main attraction. Third-quarter orders hit $19.3 billion[3] for a book-to-bill of 3.2x, raising the backlog to a record $53.2 billion, up 47% year over year. Of that, $31 billion is funded[3]. The anchors are a $6.3B[2] seven-year THAAD propulsion contract and a $4.7B seven-year PAC-3 propulsion contract, which management says include protective provisions if volumes fall short. Multi-year deals like these are exactly what Washington uses to steady production. The White House budget office notes that multi-year contracts are implemented “to promote production stability and achieve cost efficiencies,” and procurement funds stay available for obligation for three years.
The valuation looks reasonable for that visibility. Shares trade at 25 times trailing earnings and 21 times forward estimates, below the analyst consensus target of $336.33. Management also expects more than $5 billion[3] in excess cash after funding its missile capacity build-out, capital spending, and dividends. That should support future dividend increases.

Risk to Watch
Fixed-price exposure is the pressure point. Per management, the vast majority of the backlog[3] sits on firm-fixed-price contracts, so cost overruns on a rocket motor ramp come out of L3Harris’s margin rather than the government’s pocket. The company already trimmed its 2028 free cash flow expectation to $3 billion[3] from $3.5 billion, citing lower segment margin among other factors.
Huntington Ingalls Industries
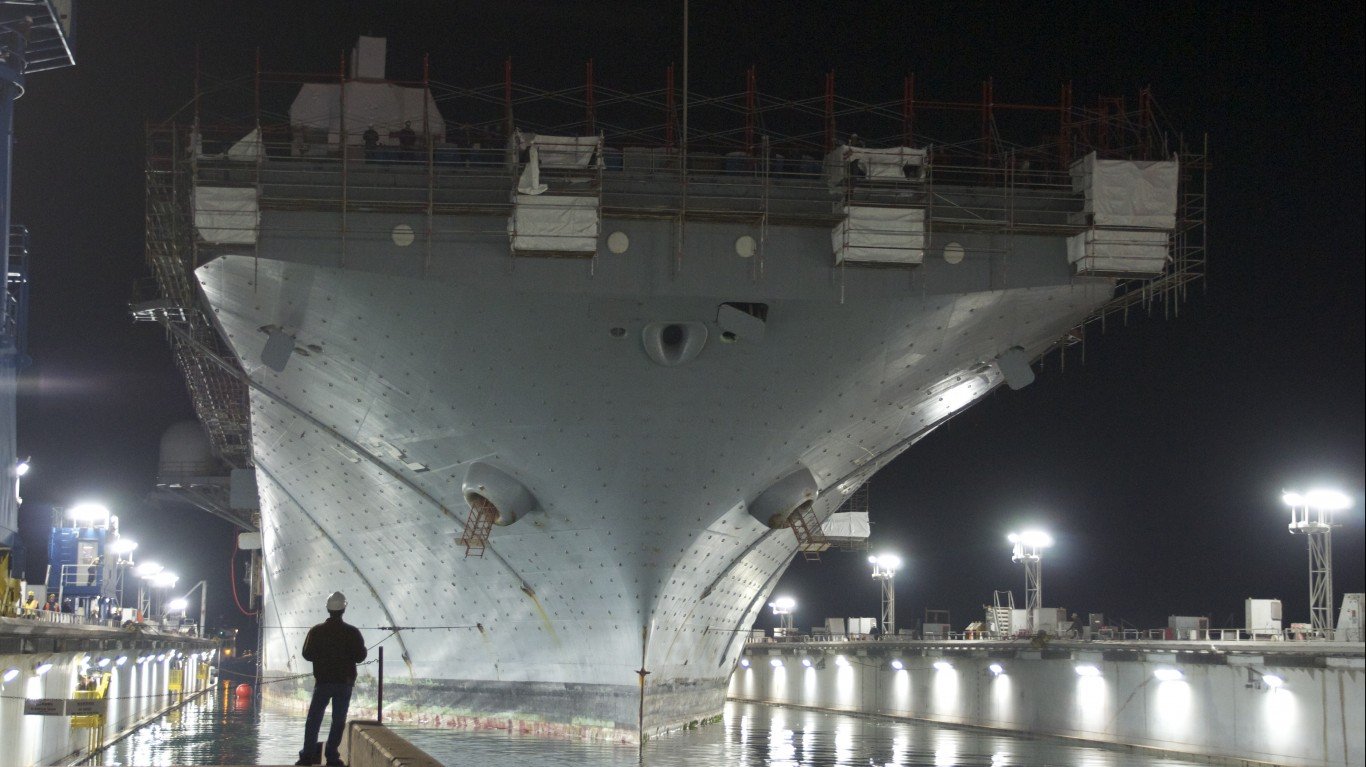
Huntington Ingalls is the largest military shipbuilding company in the United States. Its Newport News yard builds aircraft carriers and nuclear submarines; Ingalls builds amphibious ships and destroyers; and Mission Technologies supplies uncrewed vessels, surveillance, and AI work. Shares sit at $296.74, down 11.67% year to date, and the stock yields 1.8% on a trailing dividend of $5.52. The board just raised the quarterly payout to $1.41 from $1.38, an increase of about 2.2%, payable December 11 to holders of record on November 27.

Dividend Safety Check
Earnings coverage is the strongest in this pair. Trailing diluted EPS of $18.57 means the dividend takes only about 30% of profits. Last year, dividends took $213M[4] against $800 million of free cash flow, roughly 27% of cash generated.
Cash flow this year is lumpier. Free cash flow through the first three quarters stood at -$182M[5] because of seasonal working capital swings, though the third quarter produced $429M. The full-year target of $500M to $600M[5] still stands, and the trailing dividend run rate of about $218 million would use roughly 44% of even the low end. The third quarter “helped de-risk fourth-quarter expectations,” and management repeated cumulative 2026 and 2027 free cash flow of $1.2 billion to $1.3 billion. The company ended the quarter with $387 million[1] in cash and about $2.1 billion of liquidity, and it skipped buybacks during the quarter.
The dividend history is a steady staircase. Records show the quarterly payout climbing from $0.10 in its earliest entries to $1.24 in the 2023 cycle, $1.30 in 2024, $1.35 in 2025, and now $1.41.
Bull Case for Income Investors
Few companies have revenue this locked in. Huntington Ingalls booked $32.4 billion[1] of new awards in the third quarter, including Block VI Virginia-class submarines and the second Columbia-class boat, raising total backlog to $86.2 billion. That figure excludes the $5.1 billion[1] USS Harry S. Truman overhaul contract, which lands in fourth-quarter results. Chief executive Chris Kastner put it simply: “Our focus is squarely on execution, growing our workforce, improving throughput, and delivering the ships and technologies our nation needs.”[1]
Results are improving too. Third-quarter EPS of $5.48[5] beat the $4.43 consensus, and shipbuilding revenue guidance rose to $10.5 billion to $10.7 billion[1]. Shipbuilding margins are tracking near 6.2%[1] this year versus a long-term target of 9% to 10%, leaving real upside for earnings and future increases. The stock trades at just 16 times trailing and 14 times forward earnings, with an analyst consensus target of $356.08.

Risk to Watch
Execution at the yards remains the soft spot. Ingalls struggled with a slower labor recovery and weaker surface-combatant performance, and shipbuilding throughput grew about 9%[1] year to date, short of the 15%[6] goal management laid out earlier. Delays on complex ships push out cash milestones, which is why this year’s free cash flow has been so uneven.
Two Payouts Funded by Washington’s Long-Term Commitments
L3Harris and Huntington Ingalls both pay dividends that use well under half of trailing earnings, and both just raised them. Each sits on a backlog of contracted government work that runs years past the next budget fight. L3Harris offers the faster recent raise and a stronger free cash flow cushion, while Huntington Ingalls offers the lower payout ratio and the cheaper multiple. For income investors who prioritize dividend safety over headline yield, these two names fit the theme (the broader setup makes a dividend ladder you never have to sell out of; it’s the whole subject of our free guide here: Never Touch the Principal).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.