Gladstone Land Stock Has Fallen 29% in a Month as Its Dividend Faces Pressure

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
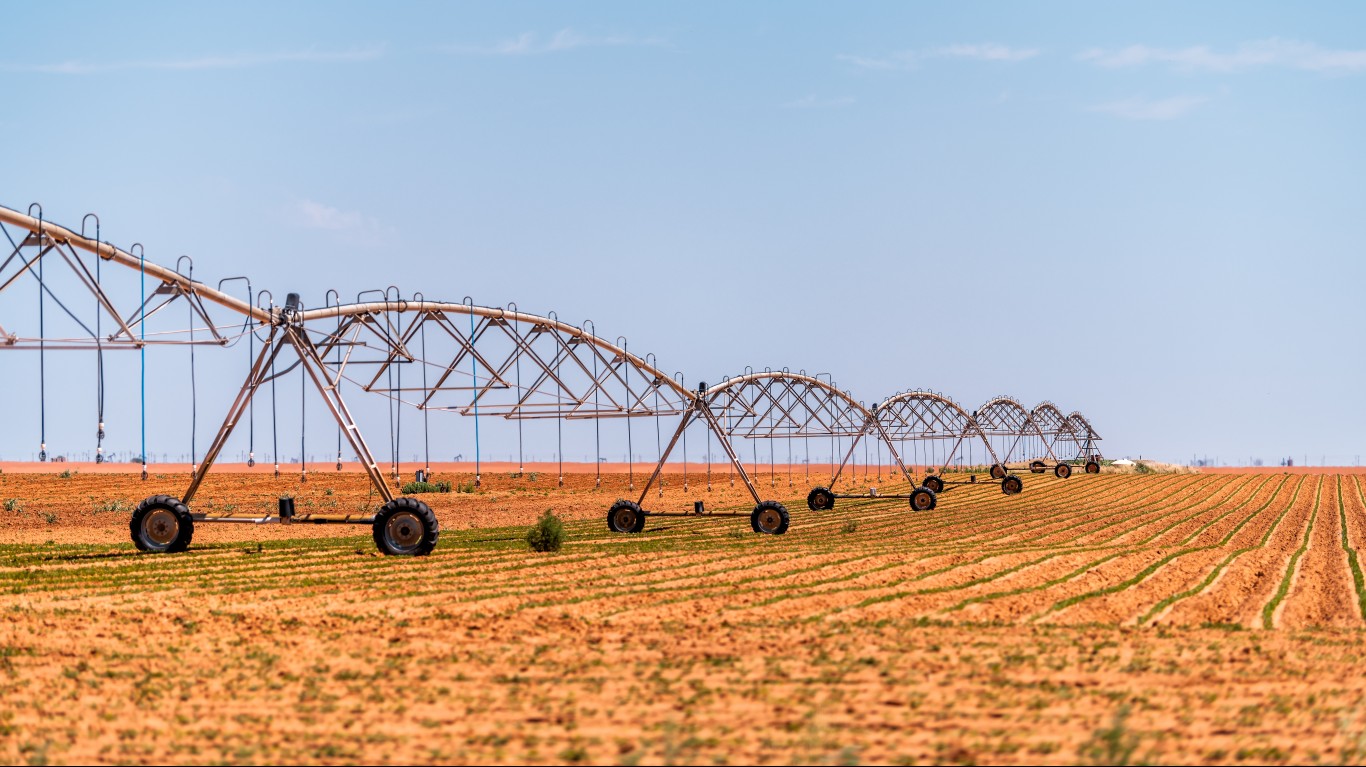
An outside manager just gave up its own incentive fee so a farmland REIT could keep paying its dividend. Investors have been selling anyway. Gladstone Land (NASDAQ:LAND) shares are down 25% year-to-date and 29.26% over the past month. A high yield is worth only as much as the company’s ability to keep funding it, and when a manager has to waive fees to protect the payout, that ability deserves a hard look.
Quick test for any dividend: recurring cash earnings (AFFO for REITs, net investment income for BDCs) should cover the payout with room to spare, operating cash flow should fund it, and debt should not be rising to fill the gap.
Gladstone Land (LAND): A Fee Waiver Is Holding Up the Monthly Check
Gladstone Land pays $0.0467 per share every month, or $0.5604 a year. At $6.53, that works out to a yield of about 8.6%. The payout has stayed at that level in every listed record from 2024 through 2026, after years of small increases, and the dividend history shows no cut. The stock goes ex-dividend on Thursday, so anyone considering it for income should understand the risks before then.
The company itself issued the warning. In its third-quarter release, Gladstone Land said: “Given the uncertainty around the 2026 crop results, which will impact our 2027 earnings, our Adviser decided to voluntarily waive the incentive fee earned in this third quarter, as we remain committed to preserving the dividend for our shareholders during this period of uncertainty.”[1] The plain-English reading: management expects the farms on their own may struggle to cover the dividend, so the external adviser stepped in. A payout held steady through obvious stress like this is a red flag. It signals strain on the underlying business.
For a REIT, the right coverage measure is adjusted FFO. Full-year 2025 AFFO came to $0.39 per share[2], which covers only about 70% of the current annualized dividend. Third-quarter AFFO jumped to $0.35 per share[3] against $0.14 in common dividends declared, but that figure was raised by early recognition of the 2025 pistachio bonus. A year earlier, AFFO was just $0.04[3]. Operating cash flow in the third quarter was negative $5.616 million[1], GAAP losses hit -$0.24[4] and -$0.32[5] per share in the first two quarters, and the share count rose 19.3% year over year. The 2026 pistachio crop was an off year made worse by spring heat. Executive Vice President William Reiman warned of “much lower trailing revenue numbers for us over the next 12 to 15 months.”[3]
Debt is the next pressure point. About 92%[3] of borrowings carry fixed rates averaging 3.57%, but roughly $130 million of MetLife loans reset in January 2027, and management said current conditions could mean an increase of about 250 basis points. The bull case: over $105 million[3] of available capital, almond prices running 18%–25%[1] higher, initial 2026 pistachio pricing up 67%, and about $30 million of property sales under contract. What to watch: when fourth-quarter crop insurance gets recognized, the MetLife reset terms, and whether the adviser has to waive fees again.
BCP Investment Corp. (BCIC): Merger Accretion Is Flattering the Payout
BCP Investment Corp. (NASDAQ:BCIC) is the BDC formerly known as Portman Ridge Finance, which traded as PTMN. It pays $0.09 a month ($1.08 annualized), which is roughly 20.7% at $5.22. Most of that yield comes from the share price, which is down 49.84% year to date. The payout has also been reset once already. Quarterly distributions of $0.69 in 2024 fell to $0.47 in late 2025 and then to the current monthly schedule.
For a BDC, net investment income is the coverage figure that matters. Headline NII of $0.37 per share[6] includes $1.657 million of purchase discount accretion from earlier mergers, which is non-cash help similar to sponsor support. Strip it out and core NII was $0.24[6], below the $0.27 quarterly base distribution. Management acknowledged it: “Core NII of $0.24 per share is below the $0.27 quarterly base distribution.” NAV per share slid from $17.55 to $13.13[6] over four quarters, non-accruals reached 6.0% of amortized cost, leverage rose to 1.7x, and asset coverage fell to 157%. The portfolio is also contracting: the company deployed $3.1 million[6] against $8.9 million of repayments and sales. CEO Ted Goldthorpe said the company expects “to favor debt repayment and share repurchases as we receive repayments over new investments in the coming quarters.”[6]
The bull case: the KeyBank facility doubled to $150 million[6] at SOFR+2.50% with maturity extended to August 2031, and the pending acquisition of Investcorp Credit Management BDC (NASDAQ:ICMB) at 90% of adjusted NAV is expected to add to earnings. What to watch: whether core NII gets back to $0.27 once the accretion ends, and whether NAV markdowns stop.
Coverage Decides Whether a High Yield Survives
Both of these stocks are paying out more than their underlying businesses currently earn, and each is leaning on help that may not last: a waived fee in one case, accounting accretion in the other. A cut remains uncertain for both, and when dividends do get reduced, the share price usually falls with them. Check coverage, cash flow, and debt before you trust the yield (we broke down the seven warning signs that a big yield is about to be cut in a free Dividend Traps report).
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.