4 Insurance Dividend Stocks to Buy in December for High Yields and Staying Power

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
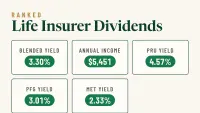
Life insurers have had a strong 2026. Higher-for-longer interest rates are raising investment income, and the big carriers are returning cash to shareholders through dividends and buybacks. Prudential Financial (NYSE:PRU | PRU Price Prediction) leads the group with a 4.49% dividend yield, and its regular quarterly payout has increased each year since 2020. Dividend safety depends on more than yield, though. Below, each pick starts with how well the payout is covered and how strong the financial position is, then moves to income.
How Life Insurers Turn Interest Rates Into Dividends
A life insurer makes money in two ways. It takes in premiums from customers today, and it invests that money until claims and annuity payments come due years or decades later. The gap between what the portfolio earns and what the insurer has promised policyholders is called the spread, and it pays for the dividend. When rates rise, new money goes into higher-yielding bonds, so that gap broadens.
Markets matter too. Asset-management fees rise and fall with stock prices, and private equity and real estate holdings can produce uneven “variable” investment income. Lincoln National (NYSE:LNC) shows the trend: its new money yield reached 6.1%[1] in the third quarter, compared with a total portfolio yield of 4.93%.
Prudential Financial: Top Yield Backed by AA Capital
Yield and payout: Prudential pays $1.40 per quarter, a 4.49% yield at a share price of $122.87. The next ex-dividend date is November 24, 2026, and payment follows on December 10.
Dividend safety: Third-quarter after-tax adjusted operating income came to $3.77 per share[2], so the quarterly dividend used about 37% of operating earnings. On a trailing GAAP basis, dividends of $5.55 per share against EPS of $10.98 work out to a payout ratio of about 51%. Prudential ended the quarter with $4 billion[2] of cash and highly liquid assets, above its $3 billion minimum. The regular quarterly dividend went from $1.10 in 2020 to $1.15 in 2021, $1.20 in 2022, $1.25 in 2023, $1.30 in 2024, $1.35 in 2025, and $1.40 in 2026. Yanela del Carmen Frias, Prudential’s CFO, put the capital order: “It starts with maintaining our AA financial strength and strengthening the balance sheet, investing in our organic growth in the business, and then deployment to buybacks and dividends.”[2]
Bull case: PGIM, the asset manager, posted a pre-tax adjusted operating margin of 26.5%[2] and third-party net flows of $9 billion, its best in 10 quarters. Retail annuity sales hit $3.9 billion[2], the highest quarterly level since 2013. Prudential is also selling its Brazil and Mexico units for $4.025 billion[2], with expected net proceeds of about $3.1 billion to put into growth businesses. The stock trades at about 11 times trailing earnings.
Risk: Japan. Prudential expects the sales suspension there to shrink its Japanese in-force book by about 15%[2]. Third-quarter operating EPS slipped to $3.77[2] from $4.05 a year earlier. Analysts are cool on the stock: 14 rate it hold, 3 sell and 1 strong sell. Their consensus target of $115.27 sits below the current price.
MetLife: Fast Dividend Growth, Modest Starting Yield
Yield and payout: MetLife (NYSE:MET) pays $0.5925 per quarter, up from $0.5675. At $101.13, that’s a 2.26% yield, which is below high-yield territory. MetLife’s income case depends on dividend growth and total capital return more than on the current yield. The latest ex-dividend date was November 3, with funds coming December 8.
Dividend safety: MetLife has the most cushion of the four. Third-quarter adjusted EPS of $2.78[3] covers the quarterly dividend with only about 21% paid out, and the trailing GAAP payout ratio is about 30%. Management targets a free cash flow ratio of 65% to 75%[3]. Holding company cash stood at $3.4 billion[3], inside its $3 billion to $4 billion range. The quarterly dividend has risen each year from $0.44 in 2019 to $0.5925 today. Total capital returned this year is about $3.5 billion, including $2.4 billion in buybacks through October.
Bull case: Adjusted EPS excluding notable items reached $2.85[3], up 22% from a year ago, on an adjusted return on equity of 19.6%. Chief Executive Michel Khalaf called MetLife “a quality compounder”[3]. Wall Street largely agrees: 5 strong buy and 8 buy ratings, with a $111.12 consensus target.
Risk: The stock has already gained 31.6% this year and trades at 2.902 times book value, leaving late arrivals with a thinner yield. Tariffs, currency swings, and a VAT change in Mexico are the operating risks to watch in 2027.
Principal Financial Group: Quarterly Raises That Keep Coming
Yield and payout: Principal Financial Group (NASDAQ:PFG) declared a fourth-quarter dividend of $0.85[4], up 8% year over year. It yields 2.89% at $111.46, which also falls below high-yield territory. Its appeal is a payout that rises almost every quarter. The stock goes ex-dividend on December 2, and payment follows on December 18.
Dividend safety: The new $0.85[4] dividend uses about 38% of third-quarter non-GAAP EPS of $2.22, and the trailing GAAP payout ratio is about 36%. In 2026, the dividend went from $0.80 to $0.82, $0.84, and $0.85. Before that, it was $0.56 through 2020 and $0.64 through 2022. Principal Financial returned $429 million[4] to shareholders in the third quarter, including $250 million of buybacks.
Bull case: In the second quarter, Specialty Benefits pre-tax operating earnings rose 25%,[5] and retirement transfer deposits grew 30%. International Pension assets climbed 10%[4] to $166 billion. At about 9 times forward earnings, it’s the cheapest of the group on that measure.
Risk: Third-quarter EPS of $2.22[4] missed expectations of $2.43. Investment Management had $10.7 billion[4] of net outflows, and its assets slipped 3%. The consensus target of $109.42 sits below the share price.
Lincoln National: Turnaround Yield With a Frozen Payout
Yield and payout: Lincoln National pays $0.45 per quarter, a 4.29% yield at $41.52. The next ex-dividend date is January 11, 2027. Lincoln cut its dividend to $0.01 during the 2009 financial crisis, and the payout has stayed at $0.45 since January 2022.
Dividend safety: Third-quarter adjusted EPS was $1.72[1], after a $0.48 hit from the annual assumption review, so the dividend used about 26% of operating earnings. Ignore the trailing P/E of about 3: annuity accounting swings inflated GAAP results. Its finances have changed a lot. The Talcott reinsurance deal closed October 1[1], and together with Fortitude Re it moved about 60%[6] of guaranteed universal life reserves to reinsurers. Leverage is at the 25%[6] target, and the risk-based capital (RBC) ratio sits well above 400%. Subsidiaries have sent $990 million[6] up to the holding company so far this year, tracking toward the high end of the $1.2 billion to $1.3 billion outlook.
Bull case: Lincoln trades at 0.901 times book and about 5 times forward earnings. It resumed buybacks with $50 million[1], and interim CFO Adam Cohen said the fourth-quarter pace “would imply about double what we did this quarter.”[6]
Risk: Management plans to return extra capital mainly through buybacks, and the earnings call included no dividend increase. Group Protection’s loss ratio rose to 87.8%[1] from 73.8%, and the shares remain down 24.22% over five years.
Best Income Case for Retirees in This Group
All four insurers cover their dividends comfortably and are returning cash through buybacks as well. Prudential has the strongest income case for a retiree: it pairs the highest yield in the group with seven consecutive years of dividend increases in the data, about 37% operating-earnings coverage, and liquidity above its minimum. MetLife and Principal Financial suit investors who want fast dividend growth and can accept a smaller starting yield. A fixed balance sheet backs Lincoln’s high yield, but until the board raises the $0.45 payout, it looks more like a turnaround play than a reliable income stock. If you are stitching names like these into an actual monthly paycheck, we walked through the mix, the payout calendar, and the withdrawal order in a free guide here: The Paycheck Portfolio Method. Next, watch for February 2027, when Prudential and Lincoln will lay out next year’s capital plans.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.