Can You Borrow Against Your Bitcoin Without Selling It? Costs and Risks You Should Know
Using your Bitcoin as loan collateral sounds like a way to get cash without giving up your coins, but a price drop can trigger a chain of forced sales and unexpected tax bills that leaves you worse off than if…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Yes, you can borrow against your Bitcoin (CRYPTO:BTC) without selling it. Companies like Coinbase (NASDAQ:COIN | COIN Price Prediction), Ledn, Arch, and Nexo allow you to use your Bitcoin as collateral for a loan. However, if Bitcoin’s price falls significantly, lenders can sell your coins to recover their funds.
According to Himanshu Sahay, co-founder and chief revenue officer at Arch Lending, retail borrowers can secure loans for up to 60% of their Bitcoin’s value, with interest rates starting at 7.25% per year. If you take out a loan at this level, Bitcoin could drop about 25% before Arch steps in and sells any of your collateral.
In the current market, this safety buffer is thinner than it seems. As of October 9, Bitcoin is trading around $82,581, down 4% over the past week and 32% since last year, about 35% below its all-time high of $126,080. So, how secure is a loan backed by an asset that has lost a third of its value over the past year?
How a Bitcoin Loan Turns Price Drops Into Margin Calls
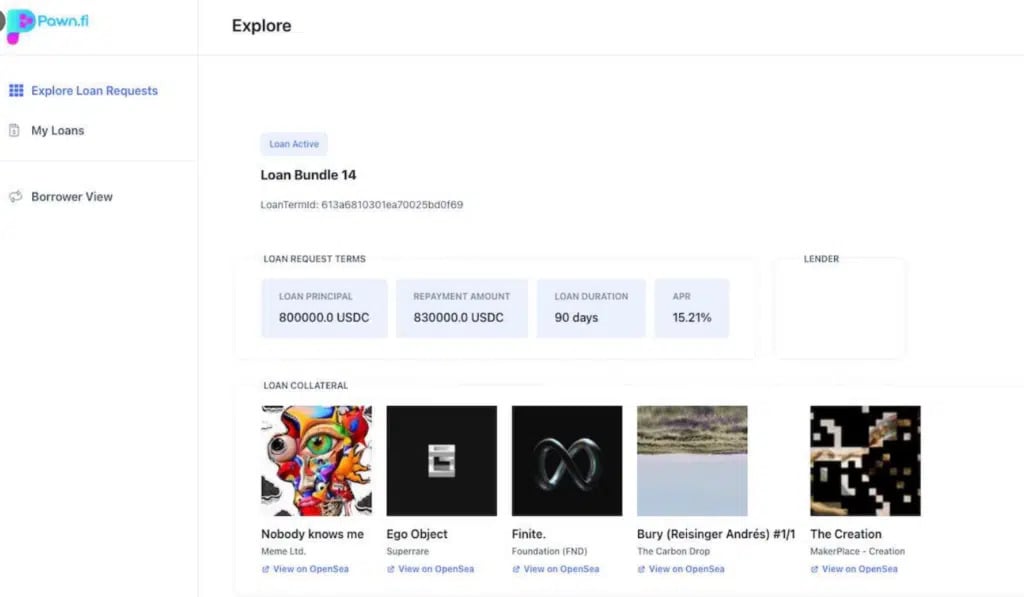
When you borrow against Bitcoin, you use the coins as collateral. You receive cash, while the lender holds the Bitcoin. When you repay the loan, you get your coins back.
Loan-to-Value (LTV) is an important metric that compares the size of your loan to the current value of your Bitcoin. If Bitcoin’s price drops, your LTV increases, even if you don’t borrow more money. For example, if you take out a $60,000 loan against $100,000 worth of Bitcoin, your initial LTV is 60%. If Bitcoin’s price falls by 25%, your LTV jumps to 80%.
At Arch, Sahay said a margin call occurs at 70% LTV, and partial liquidation starts at 80% LTV. A margin call is a lender request for additional Bitcoin or a partial loan repayment. If you opened a loan at 60% LTV, you would receive a margin call after a 14% price drop. If the LTV reaches 80%, Arch sells only enough Bitcoin to bring it back to a healthy level, letting you keep the loan intact.
You should also consider the tax implications. While borrowing against Bitcoin is generally not taxable, a forced liquidation counts as a sale for tax purposes, which could trigger a tax bill on top of your losses.
Bitcoin Lenders Have Lost Borrowers’ Coins Before
Lenders like Celsius and BlockFi have faced significant issues after mishandling customer assets. This practice, known as rehypothecation, involves lending out a borrower’s coins to others, which can put customer funds at risk if those trades go wrong.
Sahay reassured that Arch maintains its collateral in qualified custody at Anchorage Digital and never rehypothecates it. This means a regulated third party holds the assets, following standards the SEC is currently considering in its custody proposal for advisers. However, custody practices can differ across the lending industry.
How Bitcoin’s 54% Drop Would Have Hit a 60% Loan

Bitcoin has experienced significant price swings. For instance, it dropped approximately 54%, falling from its all-time high of $126,080 in October 2025 to $57,717 by June 30, 2026. Although Bitcoin has since bounced back above $80,000 due to ETF demand, a loan opened at Arch’s 60% limit near the top would have hit the 80% liquidation threshold about halfway through this decline. Each partial sale of collateral would also have been considered a taxable event.
Despite these risks, Sahay said Arch has continued to grow its lending business. “Our book grew through the drawdown,” he said, noting that most existing clients remained, and Arch has issued over $750 million in loans. This shows strong demand for Bitcoin loans, but it doesn’t reduce the risk of rapid liquidation at the maximum allowable limit.
Is Borrowing Against Bitcoin Right for You?
Borrowing against Bitcoin may work well for certain individuals. It can be a good option for those who plan to hold their coins through a market downturn, need cash for specific purposes, and have extra Bitcoin or cash on hand to cover a margin call if needed. However, it’s not advisable if you rely on the lender never having to sell your Bitcoin, especially given Bitcoin’s steep declines in past cycles.
A smaller loan gives you more room for price fluctuations. For example, a loan at 40% LTV instead of 60% can withstand a 50% price drop before hitting the 80% liquidation threshold, while a loan at the 60% maximum offers only a 25% buffer. If Bitcoin experiences another significant downturn like it has in the past, a loan at the higher end of the range could lead to liquidation and a possible tax bill on top of that.
Contact [email protected] for any questions or corrections.
Sam Daodu is a crypto analyst and the editor of 24/7 Wall St.'s Crypto Desk, where he covers Bitcoin, XRP, Ethereum, Solana and the altcoins investors search for most. His work focuses on price levels, spot ETF flows, on-chain data and the regulatory decisions that move crypto markets, written so a first-time buyer and a seasoned trader can both use it.
Sam has written about crypto professionally since 2019 and has published more than 2,000 articles. Before joining 24/7 Wall St., he wrote for crypto media outlets and Web3 companies and ghostwrote for crypto founders and token launches. His analysis is syndicated on Yahoo Finance, MSN and AOL and has been cited by other crypto news sites. He also founded MacLabs Marketing, a content and personal branding agency for crypto founders and executives.
When he isn't reading charts, Sam is usually at the gym or watching One Piece, a series he maintains has better tokenomics than most altcoins.