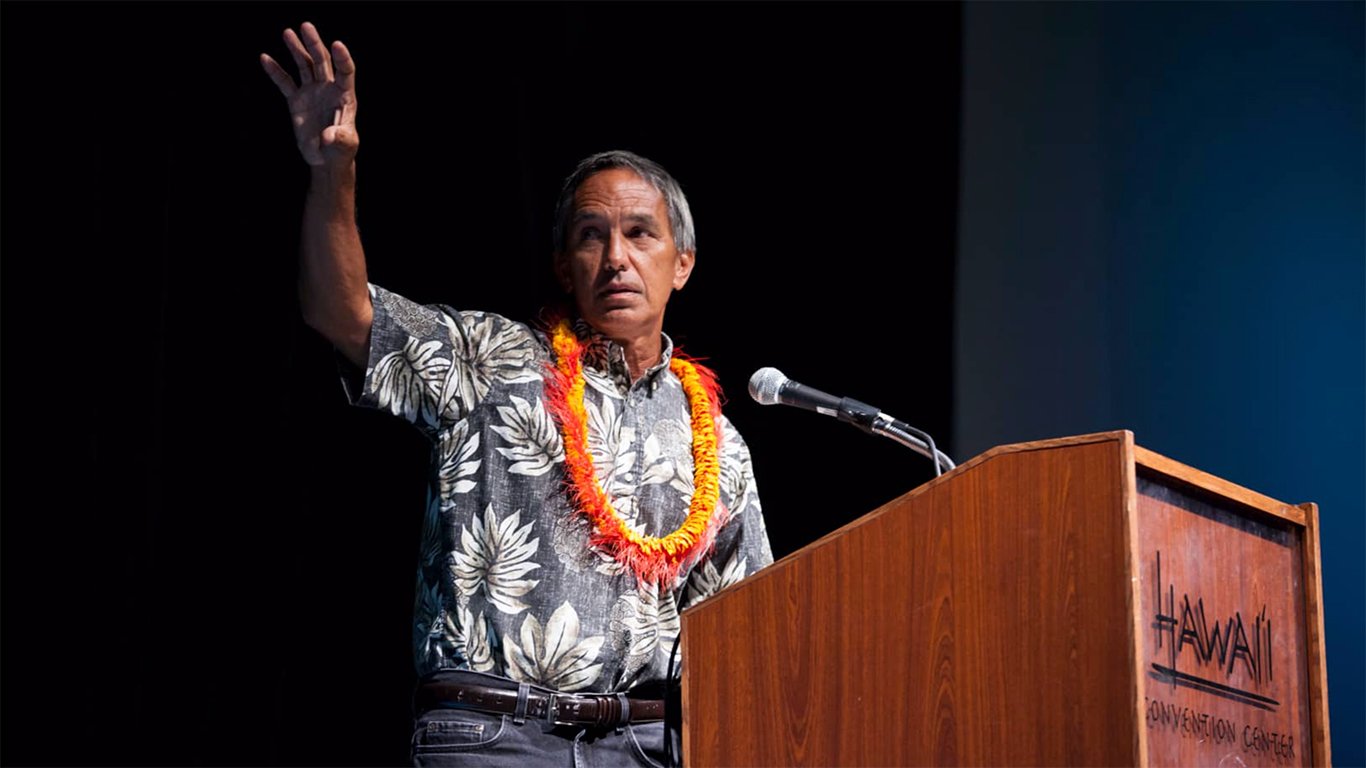
Clark Howard explains how if you save a dollar in a Roth IRA you save $1 but it’s not the case if you do the same in a 401(k)
Saving for retirement is something every worker should take seriously. Social Security is under financial strain, and the program's trustees project that its combined trust fund reserves will run out in 2034, after which payroll tax income would cover only…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Saving for retirement is something every worker should take seriously. Social Security is under mounting financial strain. The Social Security Board of Trustees’ 2026 annual report, released on June 9, 2026, projects that the combined trust fund reserves will be depleted in 2034, at which point payroll tax income would cover only about 83% of scheduled benefits. The OASI retirement fund alone faces an even sharper deadline: trustees now project it will be depleted in the fourth quarter of 2032, one quarter earlier than last year’s estimate. That shift was driven in part by provisions in the One Big Beautiful Bill Act that reduced the flow of income-tax revenue into the program. Looking further out, the 75-year actuarial deficit has risen 16% to 4.42% of taxable payroll, the largest such shortfall in nearly half a century.
Even under the most optimistic scenario, Social Security was designed to replace only about 40% of the average worker’s pre-retirement earnings. Most financial advisors recommend targeting 70% to 80% of pre-retirement income to maintain your standard of living in retirement. Personal savings must close a gap that Social Security simply was not built to fill on its own.
When it comes to retirement savings, most workers have choices. A traditional 401(k) is the most common employer-sponsored option. Ask author, radio host, and podcast host Clark Howard, and he will tell you that a Roth IRA or a Roth 401(k) makes far more sense for most people. He has specific, well-reasoned arguments for that position.
Why Howard loves Roth accounts
On a recent show, Howard said, “I’m obsessed with the Roth as a way to save for retirement.” His core argument is straightforward: save $1 in a Roth IRA and you keep $1 in retirement. Save that same dollar in a traditional 401(k) and you will keep something less, because every withdrawal will eventually face income tax. The real question is not when you start saving, but whether you pay taxes on that money now or pay them later in retirement.
Congress permanently extended the Tax Cuts and Jobs Act individual income tax rates when President Trump signed the One Big Beautiful Bill Act on July 4, 2025, locking in today’s seven brackets. The law also added temporary deductions for tips and overtime pay that apply from 2025 through 2028. Howard’s core point holds even with current rates now codified into law: future Congresses can always raise rates, and contributing to a Roth at a known rate today insulates savers from that uncertainty.
Howard also argues that savers accumulate more spendable wealth inside a Roth over a full career because investment gains are never taxed. Contribute the same dollar amount each year to a traditional account versus a Roth, and the Roth produces more after-tax retirement income, since withdrawals come out completely tax-free. That advantage compounds dramatically over a multi-decade savings horizon. In 2026, workers can contribute up to $24,500 to a Roth 401(k), or up to $7,500 to a Roth IRA. Savers aged 50 and older can add a $1,100 catch-up to the Roth IRA, raising the total IRA ceiling to $8,600 for that group. Both limits apply equally to the traditional versions of each account, so the only difference is when the tax bill arrives.
Roth accounts also shield savers from a less obvious retirement cost. Required Minimum Distributions (RMDs) from traditional 401(k)s push up taxable income, which can trigger Medicare Income-Related Monthly Adjustment Amount (IRMAA) surcharges on Part B and Part D premiums. Roth withdrawals do not count toward those IRMAA thresholds, keeping healthcare costs lower in retirement. SECURE 2.0 also eliminated RMDs from Roth 401(k)s during the owner’s lifetime, aligning those accounts with long-standing Roth IRA rules and preserving the tax-free growth advantage for as long as the money stays invested.
Howard has sharpened his message in more recent appearances. On his April 2026 podcast, he told a caller that about 95% of wage earners would be better off directing all retirement contributions into Roth accounts rather than traditional ones. He has suggested that only households earning $500,000 or more annually might benefit from blending Roth and traditional contributions, since their current marginal rate could realistically exceed what they will face in retirement.
Higher earners can use a Roth, too
For years, many higher earners faced a practical barrier: their 401(k) plans simply did not offer a Roth option. That landscape has changed substantially. Howard has said that roughly 90% of companies offering a 401(k) now give employees the choice between traditional and Roth contributions. More recent data from the Plan Sponsor Council of America puts the figure even higher: about 96% of plans permitted Roth savings in 2024, up from 93% the prior year and roughly 60% back in 2015. Under SECURE 2.0, employers can also optionally direct matching contributions straight into a Roth account rather than a tax-deferred one.
A significant rule that took effect in January 2026 adds another wrinkle for high earners. Workers who earned more than $150,000 in Social Security wages the prior year must make all age-based catch-up contributions on a Roth basis. High earners may find themselves shifted into Roth catch-ups automatically, and plans that do not offer a Roth option cannot accept catch-up contributions from affected employees until the plan is amended.
Higher earners face a separate obstacle with the Roth IRA specifically, because income phaseouts apply to direct contributions. For 2026, the phaseout range runs from $153,000 to $168,000 for single filers and from $242,000 to $252,000 for married couples filing jointly. The standard workaround is the backdoor Roth: contribute to a nondeductible traditional IRA, then convert those funds to a Roth. The strategy works cleanly for many savers, but requires careful attention to the pro-rata rule for anyone who holds other pre-tax IRA balances.
High earners with access to an after-tax 401(k) have another path available: the Mega Backdoor Roth. The employee deferral limit is $24,500, but the Section 415(c) total plan contribution ceiling sits at $72,000 for 2026. After-tax dollars can fill the gap between those two figures, and then be converted to Roth status through an in-plan conversion or in-service distribution. Workers ages 60 through 63 have an extra lever: the SECURE 2.0 super catch-up of $11,250 applies to those four specific birth years, pushing the theoretical total ceiling to $83,250. The standard catch-up for workers aged 50 through 59 rose to $8,000 for 2026, up from $7,500 in 2025.
Consulting a qualified financial advisor is wise before choosing a strategy, since the right answer depends on your current tax bracket, income trajectory, and overall financial picture.
One more option is worth knowing: you do not have to pick just one account type. Using both a traditional and a Roth account in tandem gives you the near-term tax deduction from traditional contributions alongside the long-term benefit of tax-free gains and withdrawals from the Roth. That combination of tax diversification acts as a hedge against whatever the future tax code looks like when you retire, preserving a flexibility that no single account type can provide on its own.
Editor’s note: This pass verified all contribution limits against IRS Notice 2025-67 and the official IRS 2026 retirement plan announcement, confirming the $24,500 401(k) deferral ceiling, the $72,000 Section 415(c) total limit, the $7,500 Roth IRA base limit with a $1,100 catch-up (total $8,600 at age 50), and Roth IRA phaseout ranges of $153,000 to $168,000 for single filers and $242,000 to $252,000 for married couples filing jointly. Social Security figures were confirmed against the 2026 SSA Trustees Report, including the OASI depletion date of Q4 2032, the combined OASDI depletion date of 2034, the 83% of benefits payable upon combined fund depletion, and the 75-year actuarial deficit of 4.42% of taxable payroll. The 96% Roth 401(k) plan availability figure was confirmed via CNBC’s reporting on the Plan Sponsor Council of America’s 68th Annual Survey.
Contact [email protected] for any questions or corrections.
Maurie Backman has more than a decade of experience writing about financial topics, including retirement, investing, Social Security, and real estate. Her work has appeared on sites that include The Motley Fool, USA Today, U.S. News & World Report, and Kiplinger.
Prior to becoming a full-time financial writer, Maurie worked in the financial industry trading distressed debt. She then changed course and spent a few years designing electronic toys. After a stint in content marketing and UX, she shifted back into writing and has since covered everything from the housing market to estate planning to Medicare.
When she's not busy writing, Maurie can be found hiking, walking her dogs, driving her kids to their various sports practices and games, and curling up with a good book. She cooks on occasion and bakes way too often.