3 Ways Baby Boomers are Setting Themselves Up for Retirement Disaster
Baby Boomers are approaching or already in retirement, and for many, those golden years look far less golden than expected. Too many members of this generation are making decisions right now that could create serious financial problems down the road.…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Baby Boomers are approaching or already in retirement, and for many, those golden years look far less golden than expected. Too many members of this generation are making decisions right now that could create serious financial problems down the road, and the data tells a sobering story.
Here are three ways Boomers are setting themselves up for a painful retirement.
1. Their work plans aren’t realistic
One of the most damaging miscalculations Boomers make is assuming they can simply work longer to close any savings gap. According to the Transamerica Center for Retirement Studies’ 25th Annual Retirement Survey, released in June 2025, 57% of Boomer workers expect to retire at age 70 or older, or do not plan to retire at all. That sounds like a reasonable cushion, but the actual retirement age data tells a very different story.
Research from the Center for Retirement Research at Boston College puts the average retirement age at 65 for men and 63 for women. People stop working far earlier than they plan, typically because health problems, disability, or caregiving obligations force the issue. Nationwide, roughly 31% retire earlier than planned due to health issues alone. A Boomer counting on a decade of additional earnings to fund retirement could find that runway suddenly cut short, leaving a nest egg that was never ready to support two or more decades of withdrawals.
The Transamerica survey underscores just how acute this vulnerability really is. Fewer than four in 10 Boomer workers have contingency plans in the event of unexpected job loss or a health crisis. Most have no fallback when their extended career plan unravels, and that is a serious blind spot.
2. They’re planning to over-rely on Social Security
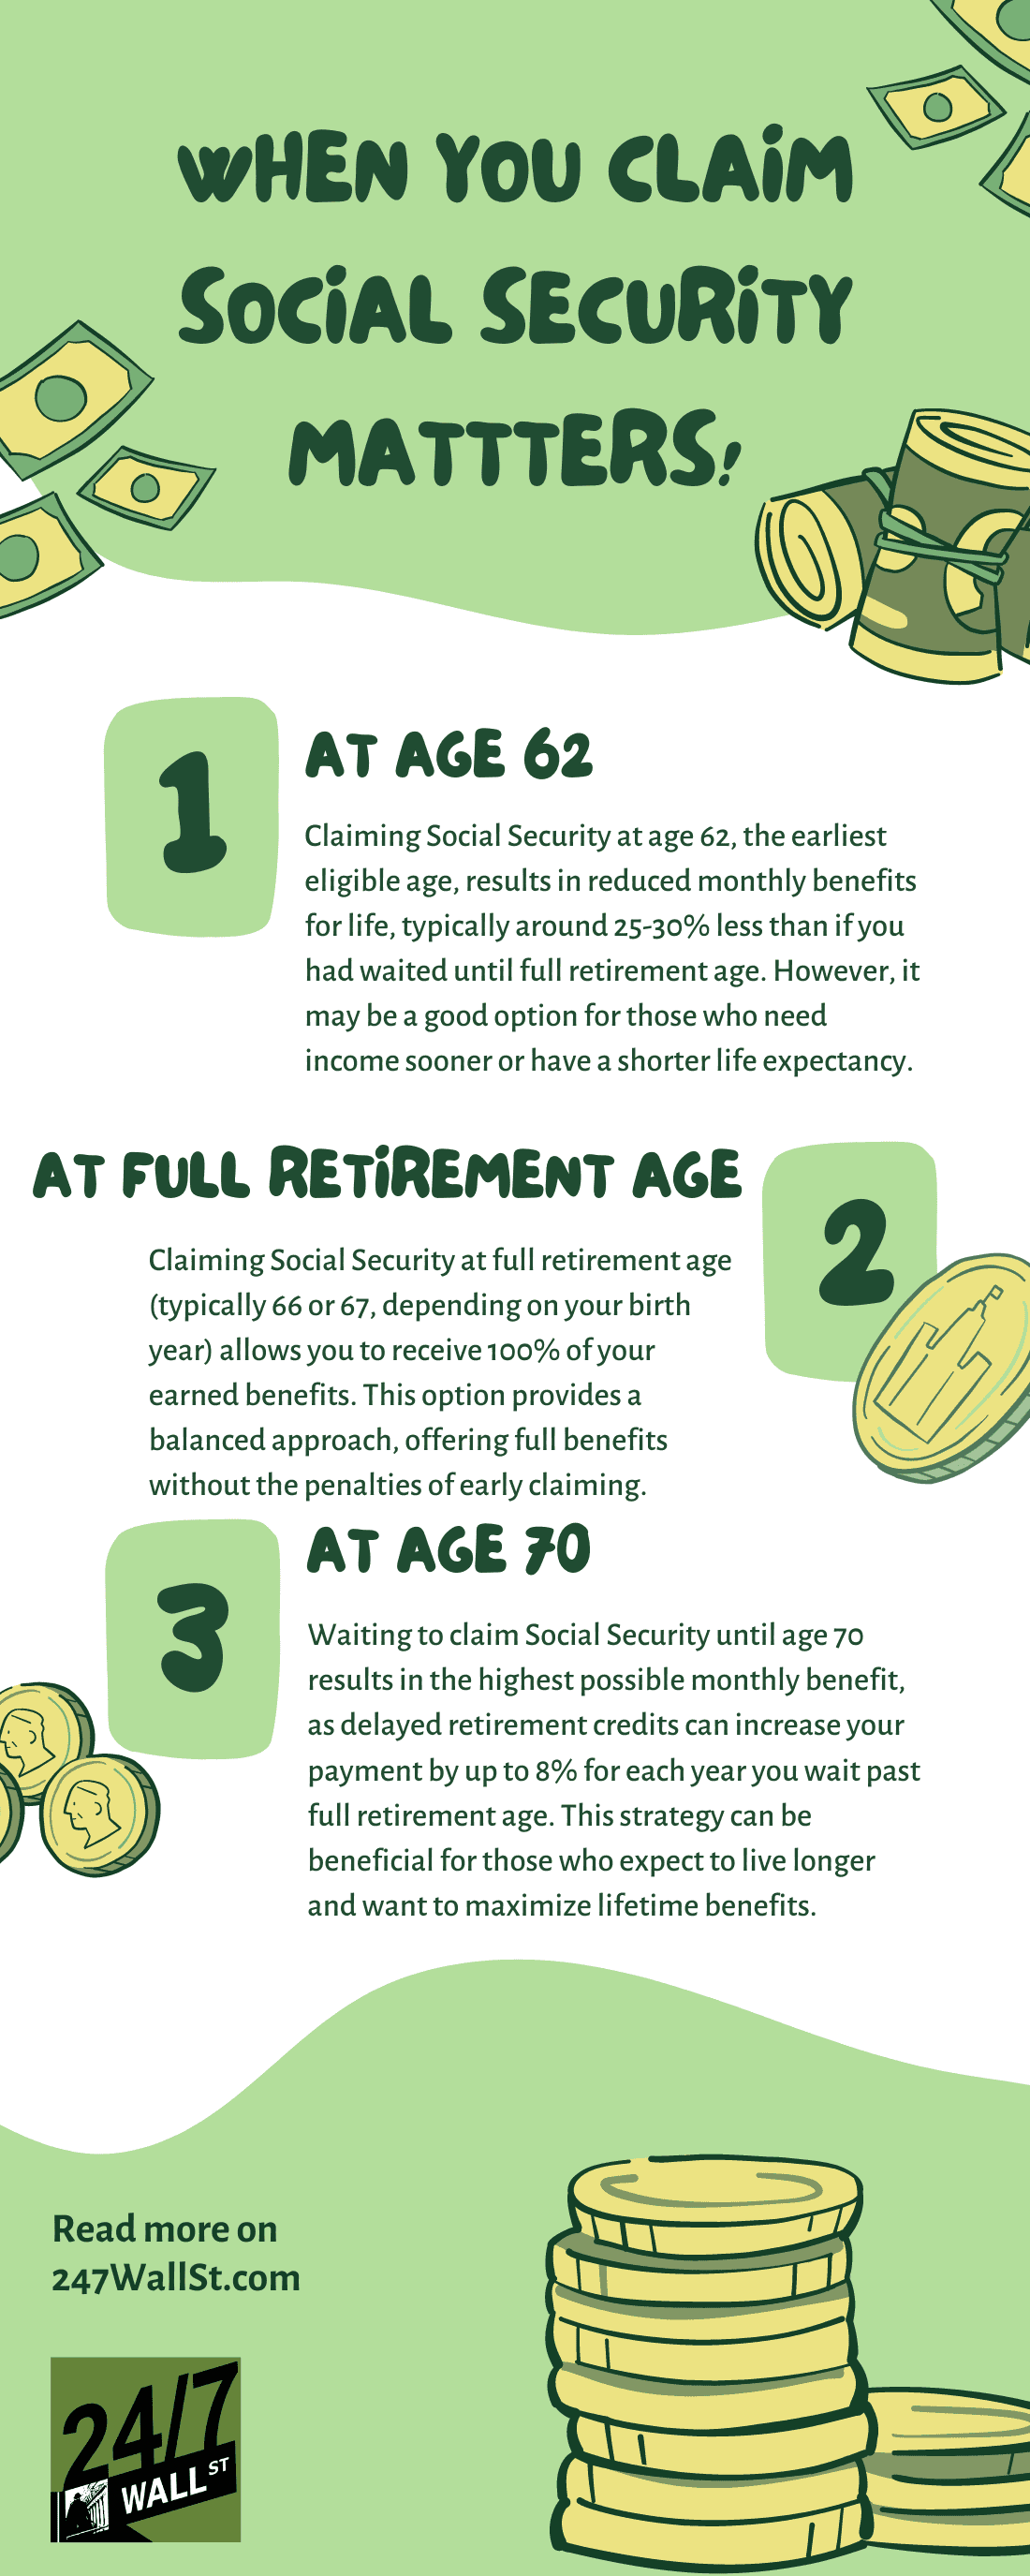
Social Security was never designed to be a full income replacement. Boomers who treat it as one are in for a rude awakening. The Transamerica 25th Annual Survey found that 39% of Boomers expect Social Security to be their primary source of retirement income, even though the Social Security Administration says the program is designed to replace roughly 40% of pre-retirement income for the average worker. That figure falls even shorter for higher earners.
The math got considerably harder in 2026. The 2.8% Cost of Living Adjustment (COLA) added around $56 per month to the average Social Security check, but that raise was largely absorbed by a nearly 9.7% jump in Medicare Part B premiums, which rose to $202.90 per month. According to research from the Center for Retirement Research at Boston College, that Part B increase will eat up more than a quarter of the COLA for most beneficiaries. The same research notes that Part B premiums as a share of the average Social Security benefit will reach an all-time high of 9.4% in 2026, marking the third consecutive year that Medicare premium growth has outpaced the COLA.
There is a partial offset available. The One Big Beautiful Bill Act, signed into law on July 4, 2025, created a new senior bonus deduction worth up to $6,000 per person ($12,000 for married couples when both spouses qualify) for taxpayers age 65 and older. The IRS confirms this deduction applies to tax years 2025 through 2028 and phases out for single filers with modified adjusted gross income above $75,000 and joint filers above $150,000. By lowering taxable income, the deduction can help some Boomers reduce the portion of their Social Security benefits subject to federal tax. Even so, Social Security alone cannot sustain a comfortable standard of living without a pension or substantial personal savings behind it.
3. They aren’t saving enough
The savings picture is the most troubling piece of the puzzle. According to Federal Reserve Survey of Consumer Finances data compiled by NerdWallet, the median household retirement savings for Americans aged 55 to 64 is approximately $185,000, while households headed by someone at or near retirement age hold a median of around $200,000. Fidelity’s Q2 2026 retirement analysis of more than 25.6 million 401(k) participants found that Boomers carried an average 401(k) balance of $260,300, a rebound from the first-quarter dip caused by early-year market volatility. Averages, however, are skewed sharply upward by wealthier savers. The median tells a harder truth.
Using the traditional 4% withdrawal guideline, a $185,000 nest egg generates roughly $7,400 per year in retirement income, or about $617 per month. Many financial planners now advocate a more conservative 3.7% withdrawal rate for new retirees, to reduce the risk of depleting accounts too quickly in a volatile market. At that rate, the same $185,000 produces just under $6,850 annually. Combined with a typical Social Security benefit, that figure still falls well short of most retirees’ actual spending needs.
The longevity risk compounds everything else. The Northwestern Mutual 2025 Planning and Progress Study found that roughly 40% of Boomers say it is at least somewhat likely they will outlive their savings. A broader concern runs across all generations: the Northwestern Mutual 2026 Planning and Progress Study found that 48% of Americans overall think it is likely they will outlive what they have set aside. Boomers who are behind have limited but real options. Delaying retirement even by one or two years can meaningfully improve outcomes. Under SECURE 2.0’s “super catch-up” rules, savers aged 60 to 63 can contribute up to $35,750 to a 401(k) in 2026, combining the $24,500 base limit with an $11,250 enhanced catch-up. Diversifying into assets that move less in tandem with equity markets can also reduce the damage a downturn inflicts in the critical early years of retirement. The window to act is narrow, but it has not closed yet.
Editor’s note: This article was updated to reflect Fidelity’s Q2 2026 retirement analysis showing a Boomer average 401(k) balance of $260,300 across more than 25.6 million participants, and to add the Northwestern Mutual 2026 Planning and Progress Study finding that 48% of Americans overall believe they are likely to outlive their savings. The SECURE 2.0 super catch-up figures were also verified against current IRS limits, confirming the $35,750 total for savers aged 60 to 63 in 2026.
Contact [email protected] for any questions or corrections.
Christy Bieber has been a personal finance and legal writer since 2008. She has a JD from UCLA School of Law and a BA in English, Media and Communications with a certification in business from the University of Rochester.
Christy has been published by a wide variety of sites, including WSJ Buy Side, Forbes, Kiplinger, Fox Business, Credit Karma, Insurify, and Annuity.org. In addition to writing for the web, she has also ghostwritten textbooks on business and law and served as a subject matter expert for course design.