Dave Ramsey to Caller: ‘You Didn’t Live in a Mercedes, Don’t Die in One’ Over $25K Funeral
Jeff from Austin called The Ramsey Show in April with a problem that is more common than most families want to admit: his mother is on $1,600 a month in Social Security, has no funeral plans, and a funeral home…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Jeff from Austin called The Ramsey Show in April with a problem that is more common than most families want to admit: his mother is on $1,600 a month in Social Security, has no funeral plans, and a funeral home just quoted her $25,000 to $26,000, with financing available at $600 a month for five years. Jeff told Ramsey he was not even sure how long his mother had left.
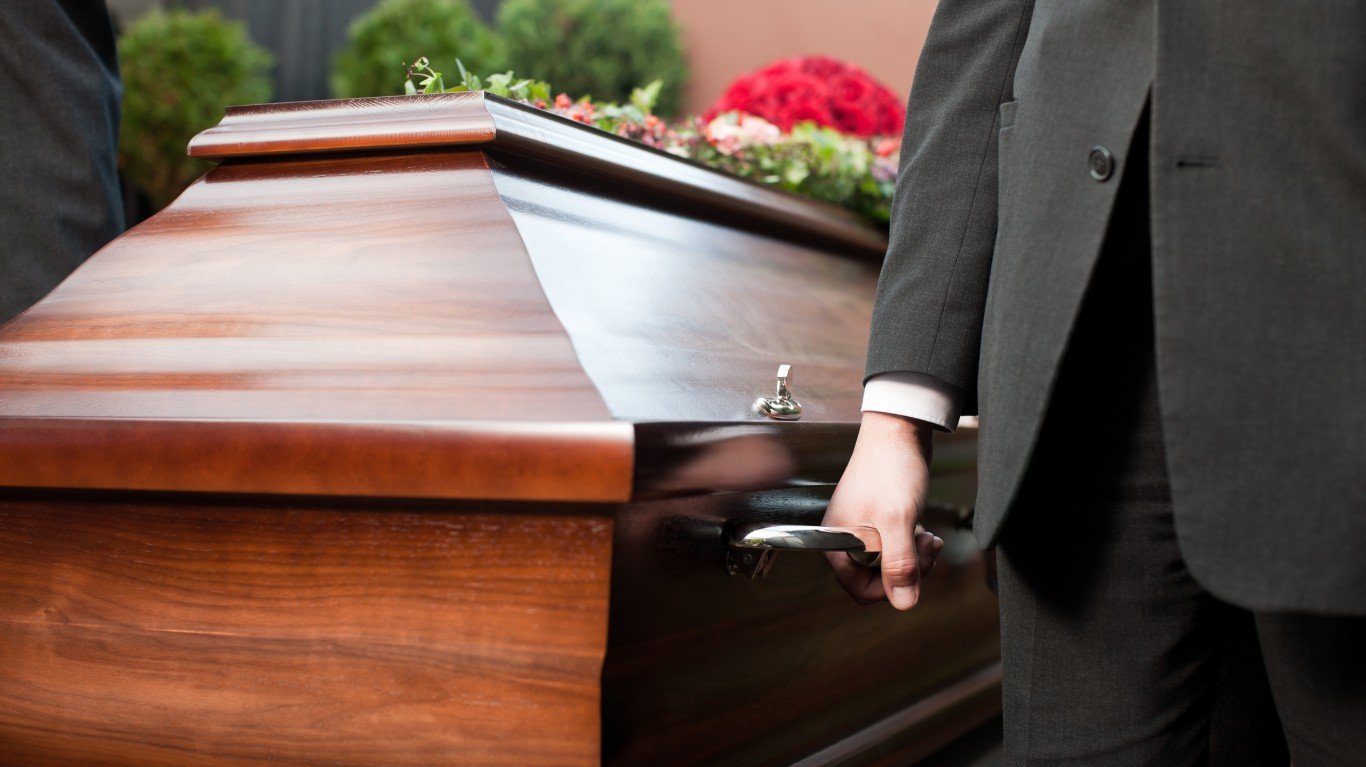
Dave Ramsey’s response was blunt: “So, Mom, you did not live your life in a Mercedes, and you shouldn’t die in a Mercedes.” He called the funeral home operator a “slickster” and told Jeff his mother got sold. The math behind Ramsey’s verdict is worth walking through carefully.
What a $25,000 Funeral Actually Costs Someone on Social Security
The caller’s mother brings in $1,600 a month. A $25,000 funeral exceeds her entire income for the year. The financing offer makes things worse: $600 a month for five years consumes more than a third of her Social Security check, every single month, for half a decade. That is not a funeral plan. It is a financial trap built around grief.
The national savings picture sharpens the point. The U.S. personal saving rate stood at 3.0% in July 2026, according to the Bureau of Economic Analysis, having dipped as low as 2.6% in June. For seniors living entirely on Social Security, even that thin cushion is largely irrelevant because there is no wage income to save from. A $25,000 obligation at $600 a month leaves almost nothing for housing, food, or medication.
Ramsey put his budget target at $5,000 to $6,000, citing a national average around $7,000 and pointing out that caskets are available at Costco. Current data puts the real cost higher. The National Funeral Directors Association’s most recent complete survey, covering 2023, pegged the median for a traditional burial with viewing at $8,300 before cemetery fees, a vault, or a headstone. Adjusted for the roughly 10% rise in funeral-expense prices since that study, the 2026 equivalent runs closer to $9,200. Add a cemetery plot, vault, and headstone and the all-in total commonly reaches $14,000 to $18,000. The gap between a $6,000 budget and a $25,000 quote is not about dignity. It is markup, upsells, and financing interest stacked on top of a family’s worst day. The quote Jeff described included extras like a $400 photo video, which are optional add-ons, not essentials.
Why Prepaying a Funeral Is Almost Always the Wrong Move
Ramsey’s advice extends beyond simply finding a cheaper provider. He advises against prepaying any funeral at all. The financial logic is straightforward: money paid to a funeral home years before death stops working for the family. Kept in a dedicated savings account or a payable-on-death account instead, that same $5,000 to $6,000 stays available for any emergency rather than locked into a contract with a specific funeral home that may change ownership, raise prices, or close. Pre-need plans can also lock in arrangements at a facility that becomes inconvenient if the family later relocates.
Consumer confidence has reflected the same financial pressure the caller’s family is navigating. The University of Michigan Consumer Sentiment Index fell to 51.7 in August 2026, a 6.3% drop from July and the second consecutive monthly decline, according to the university’s final August reading. That reading sits roughly 38% below the index’s long-run historical average of 83.7 and is now below the first percentile in the series’ entire history. Inflation remains the dominant concern: the university’s survey director noted that consumers expect prices to stay elevated for the foreseeable future, and year-ahead inflation expectations held at 4.0% in August. Families under that kind of pressure are precisely the population funeral upselling targets, because grief creates urgency and urgency suppresses comparison shopping.
Who Is Vulnerable and What to Do Instead
The profile most at risk combines three things: a fixed-income senior with no liquid savings, a family member handling arrangements under emotional duress, and a funeral home that leads with financing rather than price transparency. Jeff’s mother owns a house, though in poor condition. Ramsey’s suggestion to auction the property quickly to cover costs addresses the liquidity problem directly. Even a distressed-sale price on real property will typically cover the cost of a reasonable funeral several times over.
Families that are least vulnerable have done their homework before the phone call they dread. They have identified a low-cost provider in advance, agreed on a written budget ceiling, and committed to making no major financial decisions while sitting across from a salesperson at the worst moment of their lives. One structural fact makes early action more valuable each year: funeral service prices have risen faster than general consumer prices for decades, a pattern the Bureau of Labor Statistics documented from 1986 through 2017, and one the NFDA’s own pricing studies confirm has continued. The overall CPI ran at 3.4% for the 12 months ending August 2026, per BLS data released September 11, 2026, but funeral-specific inflation has historically outpaced that headline figure.
A significant shift in available options is also worth understanding. Cremation accounted for roughly 63.4% of all dispositions in the United States in 2025, according to the NFDA’s 2025 Cremation and Burial Report, more than double the burial rate of 31.6%. That rate has risen from around 47% as recently as 2014 and is projected to reach 82.3% by 2045. A cremation with services runs roughly $6,940 in 2026 dollars based on the NFDA’s 2023 median adjusted for inflation, and direct cremation starts around $1,000 to $1,200 in most markets. For families that want a dignified goodbye without the cost of traditional burial, cremation is now the mainstream choice, not the alternative.
The Action Steps Before the Phone Call You Dread
- Get itemized price lists from at least three funeral homes before any arrangements are needed. Federal law requires funeral homes to provide these on request, a right established under the FTC’s Funeral Rule.
- Set a firm budget ceiling in writing and share it with whoever will handle the actual arrangements.
- If setting money aside feels necessary, use a dedicated savings account or a payable-on-death account rather than a funeral home contract. The money stays liquid and the family retains full control.
- Check Costco, Sam’s Club, and direct-to-consumer casket retailers before accepting a funeral home’s casket price. Federal law requires funeral homes to accept a casket purchased elsewhere without charging a handling fee.
Ramsey’s underlying point is not about being cheap. The amount spent on a funeral is not a measure of love or respect. A $6,000 funeral arranged with intention is a complete and dignified goodbye. A $25,000 one, financed at $600 a month, can leave a grieving family in debt for years.
Editor’s note: This pass updates the U.S. personal saving rate to the BEA’s July 2026 reading of 3.0%, corrects the NFDA funeral cost figure to reflect the 2023 survey median of $8,300 (the most recent complete NFDA data) with an inflation-adjusted 2026 equivalent of approximately $9,200, refreshes the University of Michigan Consumer Sentiment reading to the August 2026 final of 51.7 (about 38% below the long-run average of 83.7), updates the CPI annual rate to 3.4% through August 2026, and replaces the cremation rate figure with the NFDA 2025 Cremation and Burial Report’s projection of 63.4% for 2025 alongside a corrected historical baseline.
Contact [email protected] for any questions or corrections.
Austin Smith is a financial publisher with over two decades of experience as an investor, analyst, and advisor. He covers stocks, ETFs, Artificial intelligence and personal finance for 24/7 Wall St. Previously, he spent over a decade at The Motley Fool as a senior editor for Fool.com, portfolio advisor for Millionacres, and launched The Ascent to help reader take control of their personal finances.
His work has been featured on Fool.com, NPR, CNBC, USA Today, Yahoo Finance, MSN, AOL, Marketwatch, and many other publications. He is as an advisor to private companies, and co-hosts The AI Investor Podcast with Eric Bleeker.
When not looking for investment opportunities, he can be found skiing, running, or playing soccer with his children. Learn more about Austin's investment approach here.