The Roth Conversion Strategy Affluent Couples Over 60 Are Using to Drain a $1.4 Million 401(k) Before RMDs Begin

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
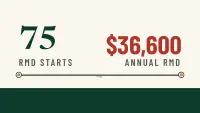
A married couple, both 61, just walked away from W-2 income with $1.4 million in a traditional 401(k). They plan to defer Social Security until 70. That decision, combined with required minimum distributions that do not begin until age 75 for anyone born in 1960 or later, gives them roughly 14 years in which their taxable income is largely whatever they choose it to be.
Couples in this position are using that window to move pre-tax money into a Roth in planned installments, paying tax voluntarily at today’s rates instead of waiting for forced withdrawals that could land at higher ones. The math has long favored this approach, and two recent developments strengthen the case. The 2026 brackets are indexed for inflation, and the One Big Beautiful Bill Act, signed into law on July 4, 2025, made the lower TCJA income tax rates permanent. Multi-year conversion plans now rest on more certainty than they have had in years.
The bracket-fill math on a $1.4 million balance
Start with the 2026 numbers for a married couple filing jointly. The standard deduction is $32,200. The 22% bracket covers taxable income up to $211,400, the 24% bracket runs to $403,550, and the 32% rate applies to income above that $403,550 level.
With no wages, no Social Security yet, and only modest brokerage income, this couple can convert roughly $240,000 per year and keep taxable income near the top of the 22% bracket. Pushing to the 24% ceiling lifts the annual conversion to somewhere between $375,000 and $435,000, which would clear the balance in about three to four years. At the 22% pace, the full balance takes roughly six to seven years. That still finishes well before RMDs begin at 75, and each dollar is taxed at 22% to 24% rather than the 32% or higher rates a large RMD could force later.
There is also a senior deduction to size before either spouse reaches 65. The OBBBA created a $6,000 deduction for each eligible person age 65 and older, covering tax years 2025 through 2028, so a couple where both spouses qualify can claim up to $12,000. The benefit phases out at 6% of income above $150,000 for joint filers and disappears at $250,000. A large conversion that pushes income into that band raises the real cost of each converted dollar above the posted bracket rate, so couples in their mid-60s should test the conversion amount against the phaseout before setting an annual figure.
The core point holds regardless of the bracket math: the tax on that pre-tax balance is coming in some form, and timing and rate are the only variables that matter. Financial commentator Wes Moss made a similar point on the Clark Howard Podcast, warning that retirees with pensions and large IRAs may “find yourself today in the 15% tax bracket, but in retirement you’re going to be in the 20% bracket” once Social Security and RMDs stack together.
Pay the tax from the brokerage, not the IRA
Conversion taxes are calculated bracket by bracket, so the total federal bill on a $240,000 conversion comes to less than 22% of the amount, even though the top slice is taxed at 22%. Paying that bill out of the 401(k) defeats much of the purpose, because it shrinks the balance that would otherwise grow tax-free inside the Roth. Many couples pay the tax from a taxable brokerage account instead, often holding six-month Treasury bills. The six-month bill yielded 4.26% as of November 9, 2026, according to Federal Reserve data, so that cash keeps earning while it waits for quarterly estimated payments. A reserve held in short-term Treasuries or a money market fund also keeps the tax bill separate from market swings.
The IRMAA trap, and why timing matters
Conversions collide with Medicare, and the rules reach back two years into income history. Premiums in a given year are based on income from two years earlier. A large conversion at 63 therefore feeds into the IRMAA surcharge at 65, and a large conversion at 73 feeds into premiums at 75, the same year RMDs begin on top of it.
In 2026, IRMAA uses 2024 income, and the first threshold for joint filers is $218,000 of modified adjusted gross income. Above that line, the standard Part B premium of $202.90 per month rises by bracket, reaching $689.90 per month at the top tier. The standard premium itself climbed from $185.00 in 2025, so each surcharge now sits on a higher base. The surcharge works as a cliff, not a slope: one dollar over a threshold triggers the full step-up for the year.
That creates a planning tension. The joint threshold of $218,000 sits inside the 22% bracket, which runs to $243,600 of gross income. A $240,000 conversion crosses the IRMAA line on its own, before any other income is counted. Clearing the balance before the 63rd birthday would require conversions well above the 22% pace, pushing the couple into the 24% bracket and deeper into IRMAA. Because premiums are reset each year from income two years earlier, conversions made after 65 can also raise premiums in later years.
Two more rules carry real weight. Each conversion starts its own five-year clock, and the converted amount can be withdrawn without the 10% penalty only after that clock runs. Suze Orman has explained that a Roth 401(k)’s time clock does not come along when the money moves into a Roth IRA. Roth IRAs also carry no RMDs during the original owner’s lifetime, which is the main reason this strategy pays off.
Three moves to make this quarter
- Model the 22% versus 24% fill, accounting for the senior deduction. Run both scenarios against your actual 2026 income. The 22% plan takes roughly six to seven years, while the 24% plan finishes in about three to four years and may suit a couple where one spouse has a pension starting at 65. If either of you turns 65 by 2028, factor in the phaseout: income above $150,000 of MAGI reduces that benefit by 6%, which raises the true marginal cost above the posted bracket rate.
- Set aside the tax-payment reserve now. A reserve in six-month Treasuries or a money market fund, sized to cover about two years of conversion taxes, keeps payments separate from market swings. At 4.26% as of November 9, 2026, the reserve earns income while it waits for each tax due date.
- Review the conversion size in the year you turn 63. The two-year IRMAA lookback means income in that year sets Medicare premiums at 65. If your combined income will exceed the first IRMAA threshold of $218,000, the full surcharge applies for the year, so the conversion amount that year carries a fixed, predictable cost. A fee-only CPA review before December 31 is worth scheduling.
Editor’s note: The required minimum distribution start age is now listed as 75 for anyone born in 1960 or later, which extends the conversion window to about 14 years. The six-month Treasury bill yield is 4.26% as of November 9, 2026, and the IRMAA section now notes that a $240,000 conversion alone exceeds the $218,000 first threshold.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.