This $2.4 Million Portfolio Pays $16,000 a Month From Four Income Buckets
Replacing a high-earning professional salary with portfolio income sounds like a simple math problem, but the yield tier you pick changes both the capital required and the risk that quietly eats it alive.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
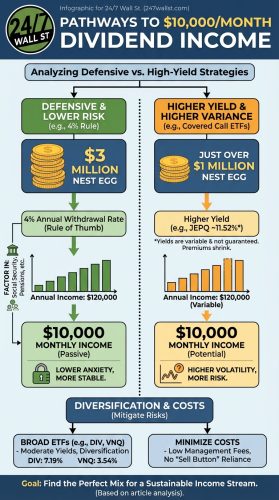
Sixteen thousand dollars a month is what a senior software engineer, an experienced litigator, or a two-earner professional household pulls down in a high-cost metro. Replacing that paycheck through investment income is a math problem, and the answer changes based on how capital is deployed.
At an 8% blended yield, a $2.4 million portfolio hits the target. That number is achievable only by mixing tiers. Four real tickers map to four distinct income profiles.
The Yield Math Behind $192,000
$192,000 divided by 0.035 equals roughly $5.49 million. Divided by 0.06 equals $3.2 million. Divided by 0.08 equals $2.4 million. Divided by 0.12 equals $1.6 million. The lower the yield, the more capital required; the higher the yield, the more risk to that capital.
The 10-year Treasury sits near 4.68% and Core PCE inflation is running at elevated levels versus the Fed’s 2% target. A yield below the 10-year is a losing proposition after tax and inflation. That reality shapes the buckets.
Bucket One: The Utility Anchor (Conservative)
NorthWestern Energy Group (NASDAQ:NWE) is the sleep-at-night sleeve. The regulated electric and gas utility pays $0.67 quarterly, or $2.68 annualized, for a yield near 3.8%. Q2 adjusted EPS came in at $0.50, beating the $0.43 estimate, and management guides to 4% to 6% long-term EPS and rate base growth. The quarterly dividend has climbed from $0.33 in 2008 to $0.67 today. The pending Black Hills merger to form Bright Horizon Energy adds scale. At $192,000 divided by 3.8%, you would need about $5.05 million of NWE alone. That is why it works as one sleeve within a larger allocation.
Bucket Two: The Insurance Compounder (Moderate)
Selective Insurance Group (NASDAQ:SIGI | SIGI Price Prediction) pairs a $0.43 quarterly common dividend with a 4.60% Non-Cumulative Preferred Series B that pays $0.28750 per depositary share quarterly. The common yields under 2%, but the preferred lands in the moderate tier. The P&C insurer trades at roughly 12 times earnings with a $140 million buyback remaining and a 12% operating ROE. Combining the common with the preferred lets one holding serve double duty.
Bucket Three: The BDC Yield Engine (Aggressive)
Capital Southwest (NASDAQ:CSWC) does the heavy lifting on current income. The BDC yields roughly 9.8%, with a 99% first-lien senior secured portfolio and a 10.81% weighted average yield on debt investments. Monthly payments run $0.1934 regular plus $0.0600 supplemental in enhanced months. Non-accruals sit at 1.1% and NAV per share is $16.69. Principal erosion risk is real: BDC dividends can be cut in credit downturns, and NAV can grind lower even as distributions land.
Bucket Four: The Lumpy Special (Total Return)
John B. Sanfilippo & Son (NASDAQ:JBSS) is the wildcard. The nut and snack processor pays a modest 1.1% base yield but layers on special dividends: $1.50 in April 2026, $1.05 in August 2026, $2.10 in August 2024. Q3 EPS of $1.43 beat the $1.16 estimate by 24%. Special dividends show up alongside price appreciation: JBSS is up roughly 23% year to date.
Why Lower Yields Often Win
CSWC pays out cash, but its 10-year price return of 391% is unusual for a BDC and reflects skilled origination. NWE delivered a 75% 10-year return plus a rising dividend. A 3.5% yield growing 5% a year doubles the income stream in roughly 14 years while principal grows. A 10% yield with flat or declining distributions pays more today and often less tomorrow. Over a 20-year retirement, that gap swamps the starting-yield advantage.
Consumer sentiment is at 49.5, in the bottom 10% of historical readings. Predictable cash flow matters more when the macro feels shaky, which is exactly when yield-chasing tempts investors into the wrong tier.
Three Actions Before Committing Capital
- Recalculate the target against actual spending. $16,000 a month is gross. If your true annual burn is $130,000, a $2.4 million portfolio at 5.5% clears it with a far safer risk profile.
- Model the tax hit by bucket. BDC distributions are ordinary income. Qualified common dividends from NWE and SIGI get preferential rates. In a taxable account, that gap can swing net income by five figures on a $192,000 gross.
- Weight buckets so the aggressive sleeve cannot break the plan. If CSWC-style holdings exceed roughly a third of the portfolio, a dividend cut plus NAV compression can force selling into weakness. Cap the aggressive tier and let the utility and insurance sleeves carry the compounding.
An 8% blended yield is achievable. Keeping it there for 20 years is the actual job.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.